Textron stock forecast 2027–2029
MyStockButler's October 2026 analysis: The probability-weighted price is $91.45 in October 2027, including dividends, and rises to $116.92 in October 2029. It hinges on stronger Aviation, aftermarket and Bell execution, while weaker deliveries and MV-75 costs define the downside.
Where could Textron's shares be by October 2029?
The probability-weighted price is $91.45 in October 2027, including dividends, a 6% return from today. It rises to $102.68 in October 2028, or 19%, and $116.92 in October 2029, or 36%.
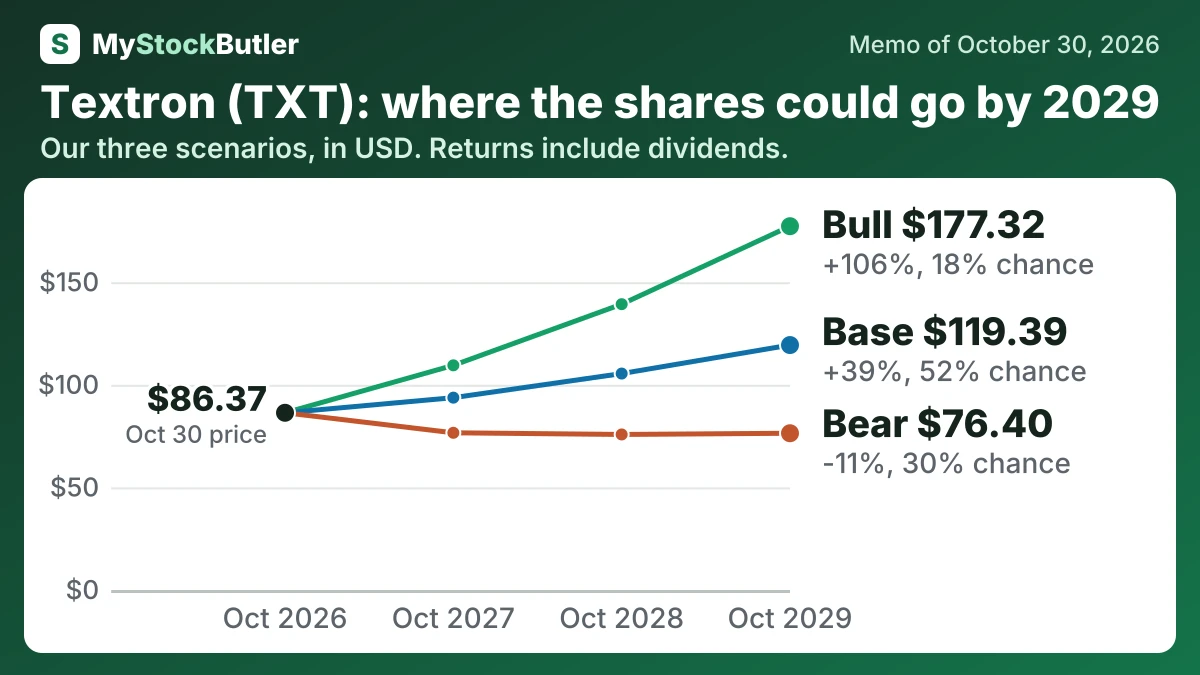
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 30% | 76.62 (-11%) | 75.81 (-12%) | 76.40 (-11%) |
| Base | 52% | 93.75 (+9%) | 105.49 (+22%) | 119.39 (+39%) |
| Bull | 18% | 109.51 (+27%) | 139.31 (+61%) | 177.32 (+106%) |
| Weighted | 100% | 91.45 (+6%) | 102.68 (+19%) | 116.92 (+36%) |
What this means. The weighted row is the probability-based average of the bear, base, and bull cases, not a separate forecast.
What has to go right or wrong for Textron?
The base case assumes equity rises each year as earnings exceed dividends and repurchases. The bear case assumes weaker deliveries and MV-75 costs, while the bull case assumes stronger Aviation, aftermarket and Bell execution. These paths reflect equity’s general rise despite large buybacks, but also its decline in one reported year and the company’s mixed guidance record.
How much cash does Textron really make?
Manufacturing operating activities generated $1.33 billion in 2025. Capital equipment took $383 million, while research and development cost $521 million as an expense. Manufacturing cash flow before pension contributions was $969 million, compared with $692 million in 2024. The measure subtracts capital spending and adds pension contributions back, so it is useful for comparison but does not necessarily show cash freely available for dividends or acquisitions.
Textron repurchased 10.7 million shares for $822 million in 2025. That supports remaining shareholders, but it is a capital-allocation decision rather than evidence that the factories became equally more profitable. The company also recorded $81 million of share-based compensation expense, which is a cost and can add shares over time. The dividend remained $0.08 per share, so the next question is how much cash the business must retain to support growth.
What does an investor pay for Textron today?
The forward P/E divides the share price by expected earnings per share. Applied to Textron, it implies about $7.20 of earnings over the next twelve months. That is higher than the company’s 2026 GAAP outlook of $5.64–$5.74 per share, but closer to its adjusted outlook of $6.55–$6.65. The difference may reflect a later forecast period, adjusted earnings, or both; the denominator is probably adjusted, but not confirmed as such.
| Today (Oct 30, 2026) | |
|---|---|
| Share price | 86.37 |
| Market value (every class) (calculated) | 14,631.08 |
| Price to book (calculated) | 1.8x |
| P/E, next 12 months (calculated) | 12.0x |
| Dividend yield (calculated) | 0.1% |