Northern Trust earnings date and guidance
MyStockButler's October 2026 analysis: Northern Trust's next results are expected on January 21, 2027. Northern Trust's key watch is whether Q4 2026 delivered promised growth and positive operating leverage as the tax rate moved toward management's expectation.
What has Northern Trust guided for Q4 2026?
For Q4 2026, management guides to 8%–9% net interest income growth year over year, assuming broadly stable markets and rates. It guides to 6%–7% total revenue growth under the same conditions. Medium-term targets include a 33.0% pretax margin and mid-teens return on equity. The expense-to-trust-fee target is 105%–110%. Management expects positive operating leverage and a 100% total payout ratio for 2026.
| Period covered | Low | High | Date given | |
|---|---|---|---|---|
| Pre-Tax Margin | Medium term | 33.0% | 33.0% | 2026-01-22 |
| Expenses to Trust Fees | Medium term | 105.0% | 110.0% | 2026-01-22 |
| Return on Equity — Mid-teens | Medium term | 2026-01-22 | ||
| Total Payout Ratio | Year to Dec 2026 | 100.0% | 2026-01-22 | |
| Net Interest Income Growth — +Low to mid-single digits | Year to Dec 2026 | 2026-01-22 | ||
| Total Revenue Growth | Quarter to Dec 2026 versus Dec 2025 | 6.0% | 7.0% | 2026-10-21 |
What this means. The 500 basis point operating leverage target means expenses should grow five percentage points more slowly than revenue, not by 500 percent.
Has Northern Trust kept its past promises?
Management also made progress on its operating promise. It set a medium-term ambition for a pretax margin above 30% in January 2025. Pretax margin is the share of revenue left after expenses but before tax: if $100 of revenue leaves $35 after costs, the margin is 35%. In the third quarter of 2026, Northern Trust reported a 34.9% pretax margin, while revenue growth exceeded expense growth by more than six percentage points.
What is Northern Trust's eight-quarter results trend?
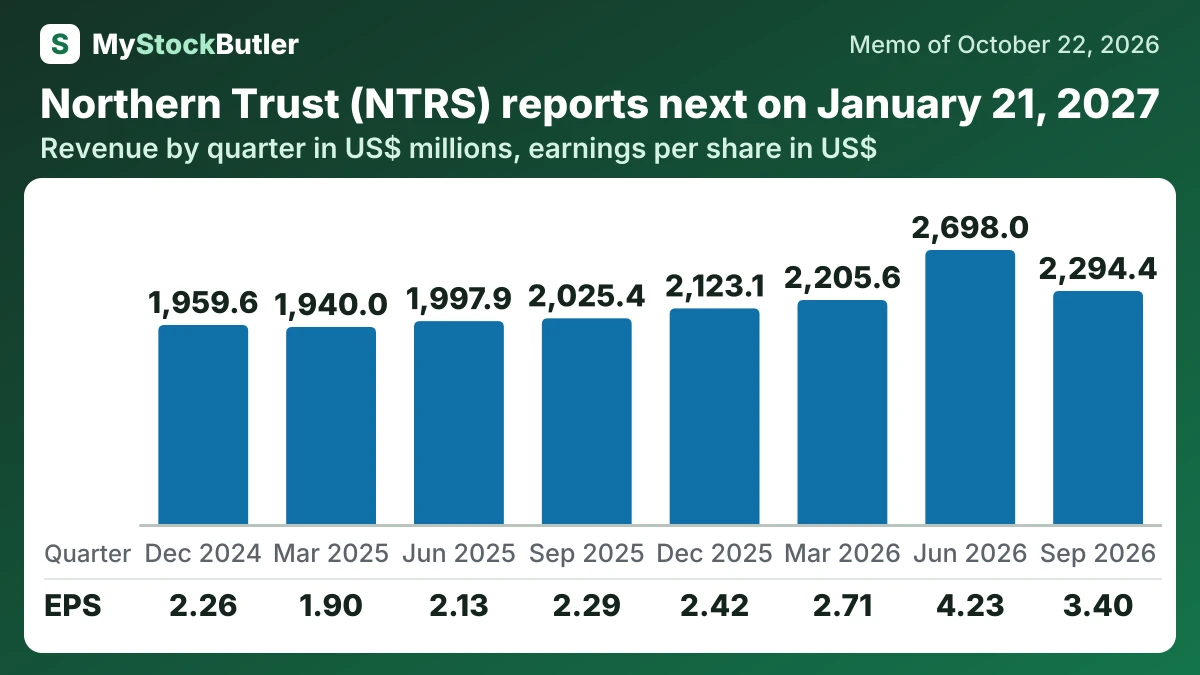
September 2026 showed stronger underlying earnings than a year earlier, although gains and a lower tax rate enlarged the improvement.
Revenue rose 13.3% year over year, while net income rose 40.5%. Diluted EPS increased faster still because profit improved and the share count declined. The sequential comparison was less useful because June included a $525.4 million Visa-exchange gain.
| Sep 2026 | Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 2,294.4 | 2,698.0 | 2,205.6 | 2,123.1 | 2,025.4 | 1,997.9 | 1,940.0 | 1,959.6 |
| Net interest income | 671.4 | 675.5 | 654.0 | 641.6 | 590.8 | 610.5 | 568.1 | 563.8 |
| Net income | 642.9 | 792.2 | 525.5 | 466.0 | 457.6 | 421.3 | 392.0 | 455.4 |
| EPS, diluted | 3.40 | 4.23 | 2.71 | 2.42 | 2.29 | 2.13 | 1.90 | 2.26 |
| Net interest margin | 1.8% | 1.8% | 1.7% | 1.8% | 1.7% | 1.7% | 1.7% | 1.7% |
| Pretax margin | 34.7% | 39.5% | 31.8% | 29.9% | 30.6% | 28.3% | 26.9% | 30.3% |
What this means. Each column covers one three-month quarter, so the amounts are not for the whole year.
What should investors watch in Northern Trust's next results?
Northern Trust’s next scheduled results call is January 21, 2027. It should show whether Q4 2026 delivered the promised growth and positive operating leverage, and whether the tax rate moved toward management’s expectation. The combination matters more than earnings per share alone because stronger operations with higher taxes tell a different story from weaker underlying growth.