FIS earnings
MyStockButler's October 2026 analysis: FIS's next results are expected on November 3, 2026. Watch whether acquired customers stay and contracts become live revenue.
What has FIS guided for 2026?
The guidance in force on October 23, 2026, was issued on August 4, 2026. It calls for full-year revenue of $13.63 billion–$13.695 billion and adjusted earnings per share of $6.15–$6.24. Adjusted earnings per share means profit per share after FIS removes specified expenses, including acquisition-related costs and purchase-accounting amortization. That helps compare operations, but those costs can still require cash.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Revenue — full year | Year to Dec 2026 | 13,630 | 13,695 | Aug 4, 2026 |
| Adjusted EBITDA (Non-GAAP) — full year | Year to Dec 2026 | 5,730 | 5,785 | Aug 4, 2026 |
| Adjusted EPS (Non-GAAP) — full year | Year to Dec 2026 | 6.15 | 6.24 | Aug 4, 2026 |
| Adjusted revenue growth (%) | Year to Dec 2026 | 29.0% | 30.0% | Aug 4, 2026 |
| Free Cash Flow | Year to Dec 2026 | 2,150 | 2,250 | Aug 4, 2026 |
| Pro Forma revenue growth (%) | Year to Dec 2026 | 4.5% | 5.0% | Aug 4, 2026 |
Has FIS kept its past promises?
The promise-keeping record is mixed. Across five checked years, adjusted EPS finished above the initial range three times, within it once and below it once. Misses against later raised targets and the large 2022 shortfalls keep the record from being strong.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Revenue | 5 years | 3 | 1 | 1 |
| Adjusted EBITDA | 5 years | 1 | 3 | 1 |
| Adjusted EPS | 5 years | 3 | 1 | 1 |
What this means. Revenue growth looks unusually high because the company bought Issuer Solutions, so newer figures include its sales while older figures do not.
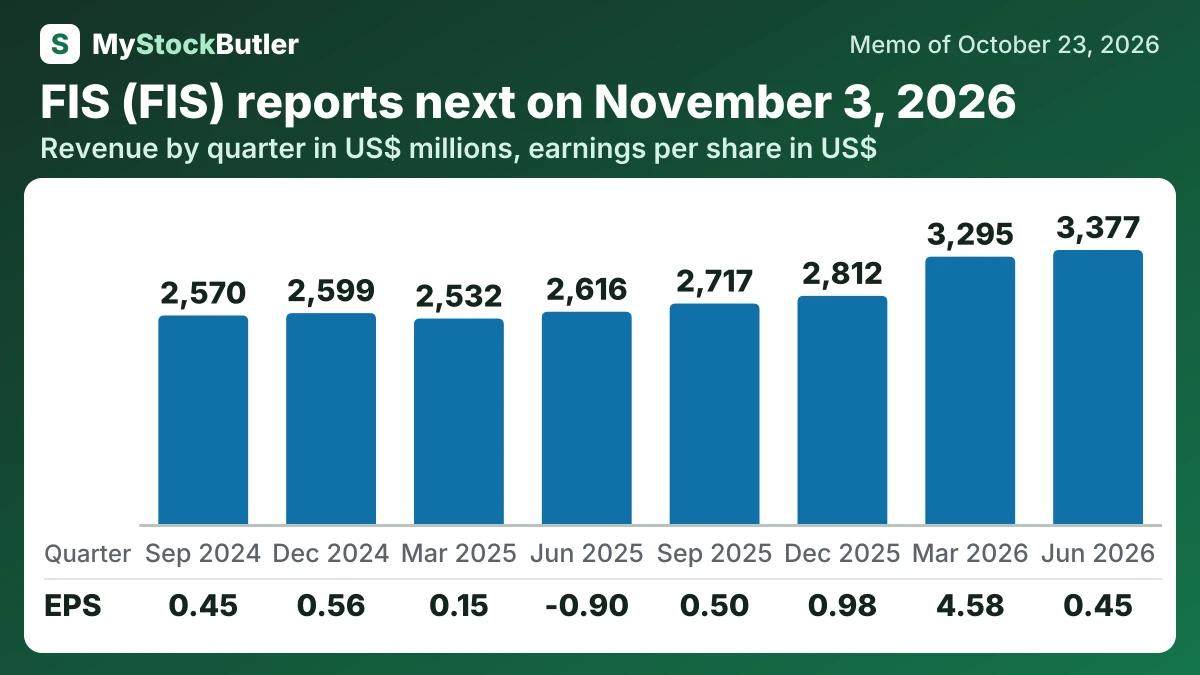
What has FIS's revenue and profit trend been over the last eight quarters?
Reported revenue rose 29% from the June 2025 quarter, while pro forma growth was 5.3%. The first figure reflects the enlarged business; the second asks how the combined company itself performed. That is evidence of continued growth, not a sudden acceleration to the reported rate.
Operating income improved, but gross and operating margins weakened. At the same time, pro forma adjusted EBITDA margin expanded. The acquisition changed the business mix, while adjusted measures excluded selected costs. The useful question is which accounting and business bridges explain the difference.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 3,377 | 3,295 | 2,812 | 2,717 | 2,616 | 2,532 | 2,599 | 2,570 |
| Gross margin | 34.8% | 33.6% | 38.3% | 37.8% | 36.4% | 34.7% | 37.6% | 38.0% |
| Operating income | 507 | 423 | 529 | 457 | 408 | 347 | 494 | 490 |
| Net income | 231 | 2,366 | 511 | 264 | -470 | 77 | 304 | 246 |
| EPS, diluted | 0.45 | 4.58 | 0.98 | 0.50 | -0.90 | 0.15 | 0.56 | 0.45 |
| = Free cash flow | 237 | 452 | 433 | 798 | 164 | 224 | 593 | 398 |
What this means. Net income was unusually high in March 2026 because it included a one-time gain from selling part of the Worldpay investment, not just profit from normal business.
What should I watch before FIS's next results?
The first checkpoint is November 4, 2026, when FIS reports third-quarter results. Management says 72% of the acquired portfolio is contracted through 2029 or beyond. That protects relationships better than an unsigned prospect, but it does not guarantee revenue: volumes, prices, products purchased and service quality can change. FIS should report renewals, account migrations, revenue per client and transaction activity.