Antofagasta earnings
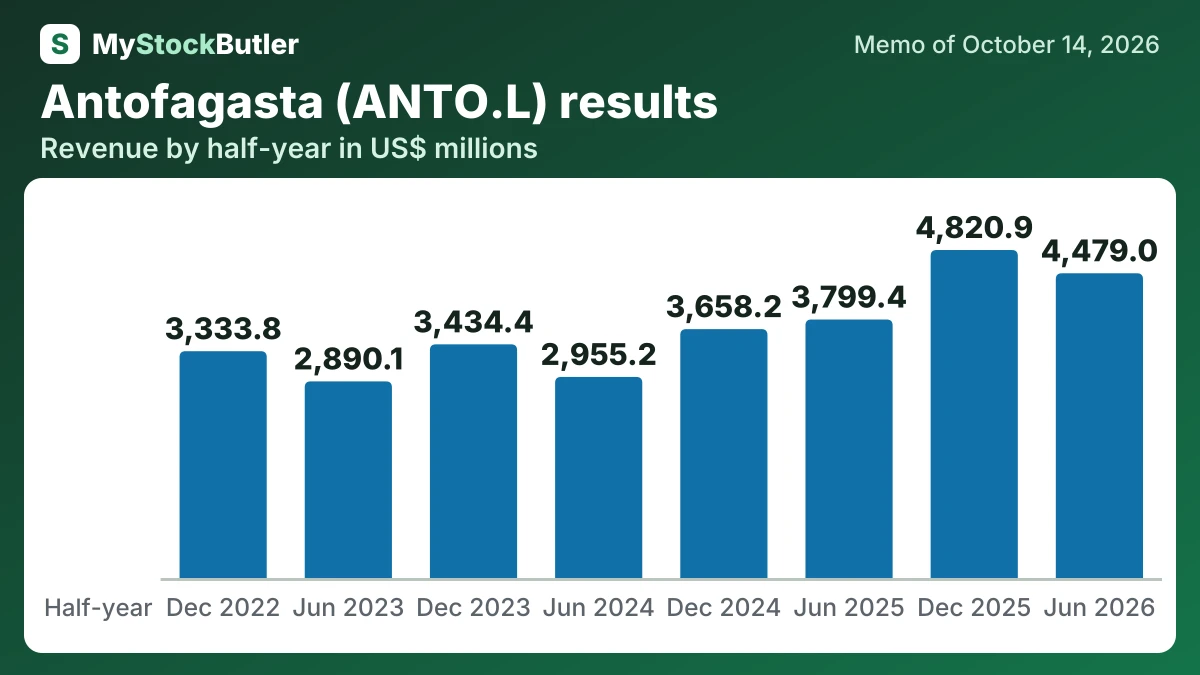
MyStockButler's October 2026 analysis: For the six months to June 2026, revenue rose to $4,479.0 million from $3,799.4 million a year earlier, operating income reached $1,896.5 million and net income reached $847.3 million. The next release should show whether inventory catches up and grades recover.
What has Antofagasta guided for 2026?
Management guides copper production to 625,000–655,000 tonnes for 2026. Cash cost guidance is $2.40–$2.60 per pound before by-product credits and $1.15–$1.35 after them. Group capital expenditure is guided at $3.4 billion.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Group copper production (tonnes) | 2026 | 625,000 | 655,000 | 13 August 2026 |
| Group-level cash cost before by-product credits (US$/lb) | 2026 | 2.40 | 2.60 | 15 July 2026 |
| Group-level cash cost guidance after by-product credits (US$/lb) | 2026 | 1.15 | 1.35 | 15 July 2026 |
| Group capital expenditure (US$ billions) | 2026 | 3.4 | 3.4 | 13 August 2026 |
Did Antofagasta keep its past promises?
The record on promises is mixed. Management first guided to 660,000–700,000 tonnes of copper for 2025, but delivered 653,700 tonnes. The 2026 forecast was later cut from 650,000–700,000 tonnes to 625,000–655,000 tonnes after severe weather affected Los Pelambres.
What has Antofagasta reported over the last eight periods?
For the six months to June 2026, revenue rose to $4,479.0 million from $3,799.4 million a year earlier. Gross margin widened, operating income reached $1,896.5 million and net income reached $847.3 million. But revenue was below the preceding half-year, so the improvement was not a straight upward sequence.
| 6 months to Jun 2026 | 6 months to Dec 2025 | 6 months to Jun 2025 | 6 months to Dec 2024 | 6 months to Jun 2024 | 6 months to Dec 2023 | 6 months to Jun 2023 | 6 months to Dec 2022 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 4,479.0 | 4,820.9 | 3,799.4 | 3,658.2 | 2,955.2 | 3,434.4 | 2,890.1 | 3,333.8 |
| Gross margin | 53.8% | 53.8% | 45.0% | 38.3% | 37.3% | 42.1% | 42.0% | 41.7% |
| Operating income | 1,896.5 | 2,098.8 | 1,274.8 | 1,337.4 | 671.3 | 1,009.1 | 773.7 | 993.0 |
| Net income | 847.3 | 807.3 | 521.6 | 569.8 | 259.6 | 504.7 | 330.4 | 1,272.7 |
What this means. The six months to December are calculated as the full-year results minus the first six months, not separately reported six-month results.
What should I watch in Antofagasta's next release?
A later weather shutdown belongs outside the June accounts. The next evidence must show whether inventory catches up and grades recover, rather than assuming that higher prices prove an operating recovery.
Production updates should distinguish ore movement, grade, processing and shipments. A shipment of stored concentrate can lift sales without proving that the mine’s ongoing rate has recovered. The 2027 commissioning milestones will then test whether construction is becoming usable capacity.