WTW earnings: guidance and results
MyStockButler's October 2026 analysis: WTW's next results are expected on October 29, 2026. Watch organic growth, margin improvement and cash conversion.
What has WTW guided for 2026?
For 2026, management expects mid-single-digit organic growth in HWC and Risk & Broking. Risk & Broking guidance calls for 100 basis points of adjusted operating margin expansion. Propel targets $400 million of annual gross savings, with about $50 million reinvested for growth.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Risk & Broking, annual adjusted operating margin expansion (basis points) | Year to Dec 2026 | 100 | 100 | Jul 30, 2026 |
| Share repurchases | Year to Dec 2026 | 1,000 | Jul 30, 2026 | |
| Additional capital expenditures for fixed assets and software | Remainder of 2026 | 110 | 135 | Jul 30, 2026 |
| Health, Wealth & Career, Segment organic revenue | Year to Dec 2026 | Jul 30, 2026 | ||
| Risk & Broking, Segment organic revenue | Year to Dec 2026 | Jul 30, 2026 | ||
| R&B, margin expansion to 2027 (basis points) | Year to Dec 2027 | 100 | 100 | Jul 30, 2026 |
What this means. A basis point is one hundredth of one percentage point, so 100 basis points means a 1 percentage point increase.
Has WTW kept its past promises?
Management has delivered one clear commitment. It targeted US$450 million of annualised transformation savings by the end of 2024 and reported US$473 million. Annualised savings mean an expected yearly benefit once changes are fully operating, not cash already collected.
What is WTW's revenue and profit trend?
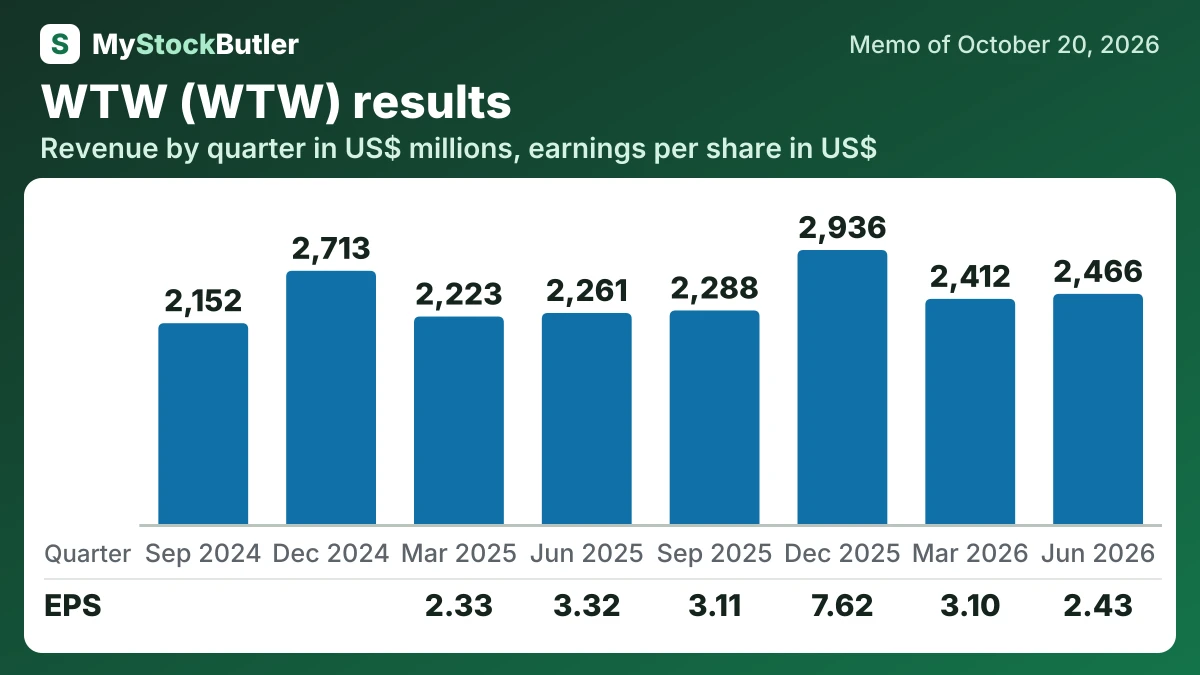
Revenue rose from $2,261 million in June 2025 to $2,466 million in June 2026. WTW’s bridge attributed the increase to 5% organic growth, approximately three percentage points from acquisitions and roughly one from currency. That improved on March 2026 organic growth of 3%.
Net income fell from $331 million to $229 million, but June 2025 included a $74 million tax benefit. Removing that comparison effect makes the underlying decline less severe. Cash gives a steadier signal: March and June free cash flow together improved from $217 million to $360 million.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 2,466 | 2,412 | 2,936 | 2,288 | 2,261 | 2,223 | 2,713 | 2,152 |
| Operating margin | 14.8% | 18.6% | 34.6% | 18.3% | 16.3% | 19.4% | ||
| Operating income | 364 | 448 | 1,016 | 418 | 368 | 432 | ||
| Net income | 229 | 297 | 735 | 304 | 331 | 235 | ||
| EPS, diluted | 2.43 | 3.10 | 7.62 | 3.11 | 3.32 | 2.33 | ||
| = Free cash flow | 425 | -65 | 708 | 621 | 303 | -86 | 598 | 442 |
What this means. The older earnings figures are blank because the company changed what it kept and republished only revenue and free cash flow, not those profit figures.
What should people watch in WTW's next results?
WTW will release third-quarter results before the market opens on October 29, 2026, followed by a call at 9 a.m. Eastern time. Investors should look for organic growth, margin improvement and cash conversion, meaning how much accounting profit becomes cash. An unchanged outlook will be more convincing if WTW explains Propel’s spending and early implementation clearly.