WTW stock forecast 2027–2029
MyStockButler's October 2026 analysis: WTW's weighted price is $420.49 in October 2029. WTW's outcome hinges on durable growth, margin expansion and cash savings from Propel.
Where could WTW's shares be by 2029?
The weighted price is $328.61 in October 2027. That represents a 4% total return including dividends. It reaches $420.49 in October 2029. That represents a 36% total return including dividends. The bear case carries 25% probability. The base case carries 55%. The bull case carries 20%.
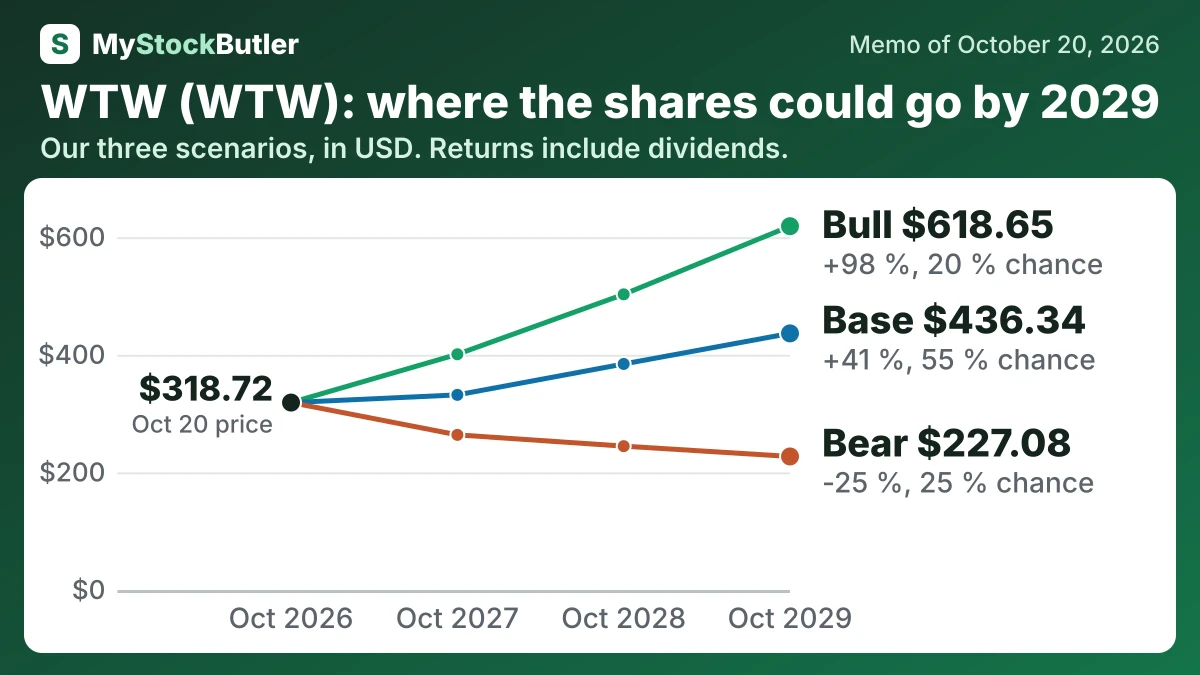
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 25 % | 263.77 (-16 %) | 244.60 (-21 %) | 227.08 (-25 %) |
| Base | 55 % | 331.82 (+5 %) | 384.38 (+23 %) | 436.34 (+41 %) |
| Bull | 20 % | 400.85 (+27 %) | 502.77 (+60 %) | 618.65 (+98 %) |
| Weighted | 100 % | 328.61 (+4 %) | 373.11 (+20 %) | 420.49 (+36 %) |
What has to go right or wrong for WTW?
The bear case gives $1,737 million in 2027 and $1,720 million in 2028. It ends at $1,712 million in 2029, using 2% growth and margins falling from 17.2% to 16.3%. Soft insurance pricing can pressure commission revenue, while Propel’s $625 million of expected cash costs may arrive before savings.
The bull case gives $1,993 million in 2027 and $2,290 million in 2028. It reaches $2,597 million in 2029, using 8% growth and margins rising from 18.8% to 21%. The evidence is WTW’s prior delivery of $473 million of transformation savings against a $450 million target, plus the possibility that automation creates lower payroll or more paid work.
How much cash does WTW really make?
Using adjusted net income, free-cash-flow conversion was 91.7%. Using adjusted operating income, it was 63.1%, because operating income comes before interest and tax. After allowing for $153 million of share-based compensation, analytical “real free cash flow” was $1,393 million. That is an allowance for employee compensation and dilution, not a deduction made in WTW’s cash-flow statement.
| 2025 | 2024 | |
|---|---|---|
| Cash from operations | 1,775 | |
| − Capital spending | 229 | |
| = Free cash flow | 1,546 | 1,282 |
| − Stock pay | 153 | |
| = Real free cash flow | 1,393 |
What this means. The company's own free cash flow matches ours at 1,546 million dollars, but we subtract 153 million dollars of share-based pay because giving employees shares still reduces shareholders' ownership.
What does an investor pay for WTW today?
P/E, or price-to-earnings, says how much investors pay for each dollar of annual profit. WTW trades at 19.6 times trailing earnings and 16.1 times next-12-month earnings. The lower forward multiple assumes earnings will rise; it does not prove that the shares are cheap.
| Today (Oct 20, 2026) | |
|---|---|
| Share price | 318.72 |
| P/E, last 12 months (calculated) | 19.6x |
| P/E, next 12 months (calculated) | 16.1x |
| Free cash flow yield (calculated) | 5.2% |
| Real free cash flow yield (calculated) | 4.7% |
What this means. The enterprise value is higher than the market value because it also includes the company's debt after subtracting its cash.