SWK stock forecast 2027–2029
MyStockButler's October 2026 analysis: The weighted forecast puts SWK at $101.65 in October 2027, $112.46 in October 2028 and $125.80 in October 2029, with the base case at 53% probability. It hinges on recurring cash conversion after inventory benefits fade.
Where could SWK's shares be in October 2027, October 2028 and October 2029?
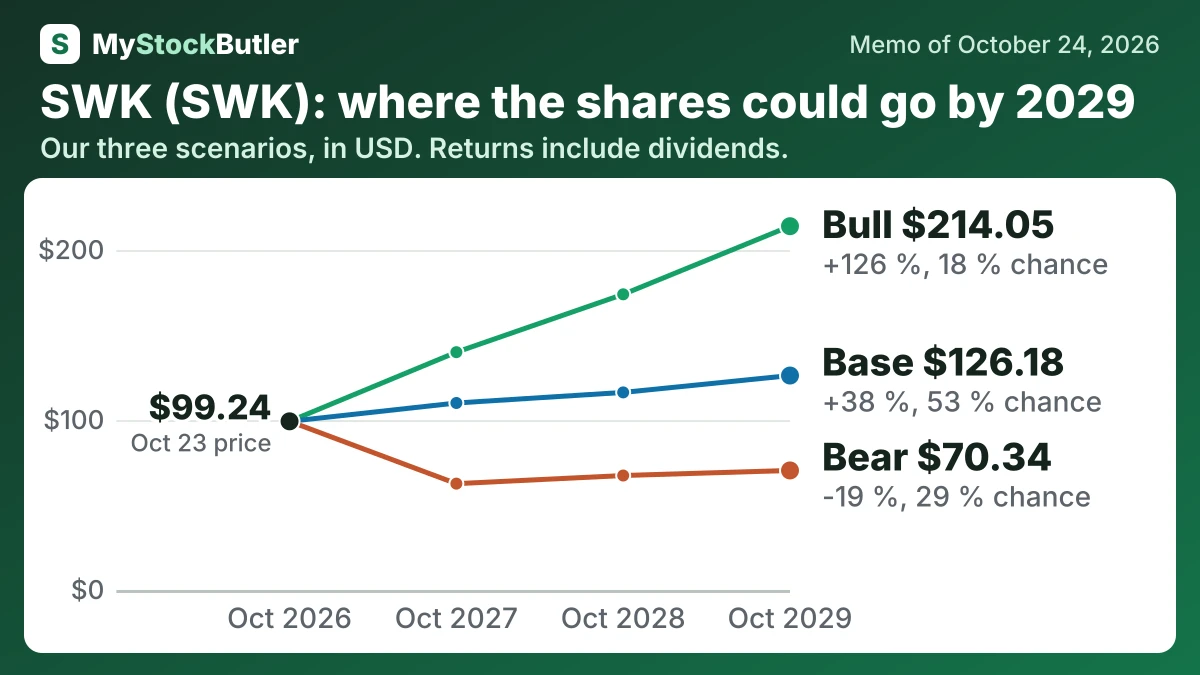
The forecast's central answer is a modestly positive weighted return, with substantial downside and upside around it. The weighted price is $101.65 in October 2027 and $112.46 in October 2028. It reaches $125.80 in October 2029. Including dividends, those prices represent returns of 6% and 20% at the first two dates. The final return is 37%.
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 29 % | 62.58 (-34 %) | 67.36 (-25 %) | 70.34 (-19 %) |
| Base | 53 % | 110.03 (+14 %) | 116.26 (+24 %) | 126.18 (+38 %) |
| Bull | 18 % | 139.93 (+44 %) | 173.96 (+82 %) | 214.05 (+126 %) |
| Weighted | 100 % | 101.65 (+6 %) | 112.46 (+20 %) | 125.80 (+37 %) |
What this means. The weighted row is the average value after giving each case importance based on its probability, not a separate prediction.
What has to go right for SWK, and what could go wrong?
The base reflects Q2 Tools & Outdoor volume growth of 3% and a 10.9% segment margin, but it excludes the assumption that tariff refunds permanently lift profitability. The bear case follows the history of Tools & Outdoor profit falling from $1,985.4M in 2021 to $687.6M in 2023. The bull case requires DEWALT demand, productivity and the 2028 gross-margin goal of 35%–37% to become durable.
How much cash does SWK really make?
Free cash flow is operating cash flow less capital and software spending. In FY2025, operating cash flow was $971.2 million. Capital and software spending was $283.3 million, leaving $687.9 million of free cash flow. That was close to adjusted net earnings, but it does not show whether the cash came from durable profit or from releasing money tied up in inventory and receivables.
Free cash flow also excludes dividends, acquisitions and debt service. Approximately $501 million of FY2025 dividends left only about $187 million before other financing uses. Cash then determines how much debt the balance sheet can safely carry.
What does SWK's share price imply?
At $99.24 a share on the October 24, 2026 valuation snapshot, the market values all SWK shares at $14,986.9 million. Enterprise value is $19,152.4 million because the business carries more financing claims than cash. The CAM sale changed this calculation because Howmet paid SWK, which then reduced debt and repurchased shares.
| Today (Oct 24, 2026) | |
|---|---|
| Share price | 99.24 |
| Market value (calculated) | 14,986.891453 |
| Enterprise value (calculated) | 19,152.391453 |
| P/E, next 12 months (calculated) | 15.7x |
| Price to book (calculated) | 1.7x |
| Dividend yield (calculated) | 3.4% |
What this means. Enterprise value is higher than market value because it adds debt and subtracts cash, showing what buying the whole business would cost.