Spirax earnings
MyStockButler's October 2026 analysis: Spirax reported six-month revenue of £863.8 million, higher operating income and 5.0% organic growth, while adjusted operating profit rose 6% organically. Watch for orders becoming shipments, especially in STS, and for pharmaceutical and biotechnology demand to move into WMFTS revenue.
What has Spirax guided for 2026?
For 2026, management guides to mid-single-digit organic revenue growth and uses 20.0% as its adjusted operating-margin reference point. Organic growth measures the existing business without acquisitions, disposals or currency effects. Adjusted margin is adjusted operating profit as a share of sales, although the reported pound margin can still move with exchange rates.
Cash conversion was 54% in the first half against an 89% full-year guide. Spirax built inventory against possible disruption and expects to use it later, so the key test is whether stock leaves the warehouse and customers pay without a fresh cash drain. Its 3/5 record on comparable promises is useful, but the guidance was often cautious.
| Period | Low | High | Given on | |
|---|---|---|---|---|
| Organic growth in Group revenues | Year to Dec 2026 | Aug 11, 2026 | ||
| Group adjusted operating profit margin | Year to Dec 2026 | 20.0% | Aug 11, 2026 | |
| STS sales growth | 6 months to Dec 2026 | 1.0% | Aug 11, 2026 | |
| ETS sales growth | 6 months to Dec 2026 | Aug 11, 2026 | ||
| WMFTS sales growth | 6 months to Dec 2026 | Aug 11, 2026 | ||
| Cash conversion | Year to Dec 2026 | 89.0% | 89.0% | Aug 11, 2026 |
What this means. Some numbers in the low and high columns are comparison figures from an earlier period, not exact targets for 2026.
Has Spirax kept its past promises?
Management guides to mid-single-digit organic revenue growth, a 20.0% adjusted operating-margin reference point and 89% cash conversion for 2026. Its comparable-promise record is 3/5. Cash conversion was within or above guidance in all five years reviewed.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Adjusted cash conversion | 5 years | 1 | 4 | 0 |
| Group adjusted effective tax rate | 4 years | 1 | 1 | 2 |
What this means. The company met its forecasts in three of five years, but its tax rate was below management's forecast in two years.
What is Spirax's revenue and profit trend?
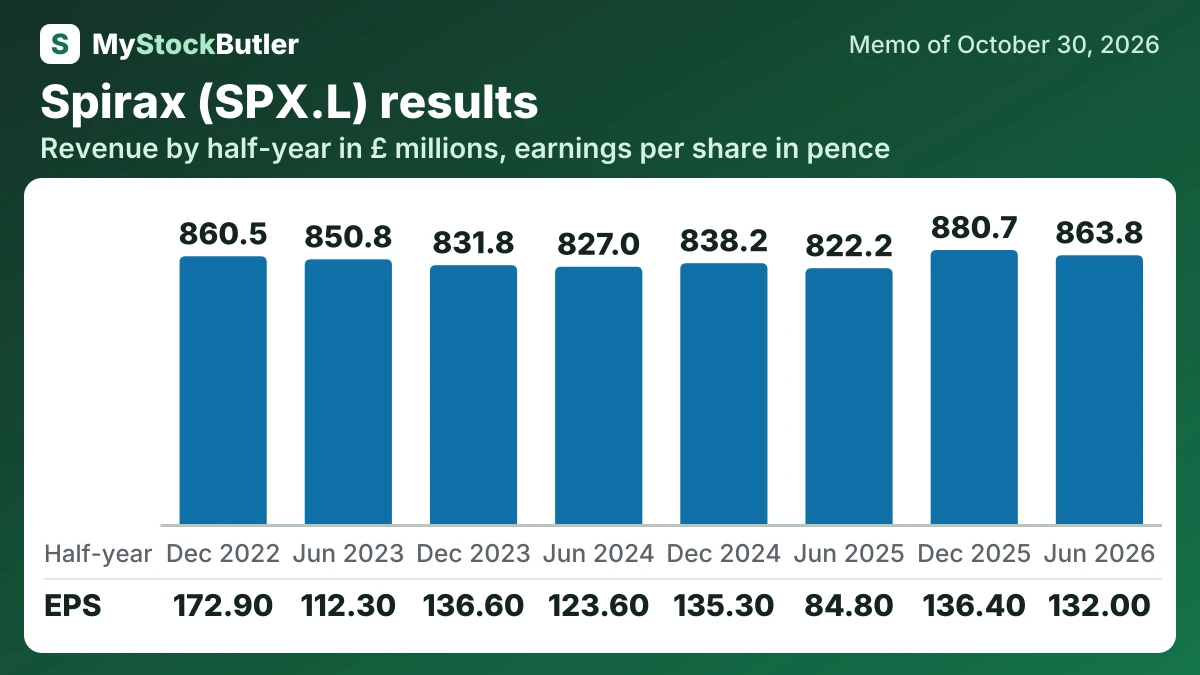
Spirax reported six-month results to June 2026, rather than a separate quarter. Revenue was £863.8 million, up from £822.2 million in the comparable period. Organic growth was 5.0%. Electric Thermal Solutions grew 11% organically, Watson-Marlow grew 7% and Steam grew 1%.
Reported operating income rose from £106.8 million to £154.2 million. Much of that apparent leap reflects the restructuring charge in the earlier comparison period. Adjusted operating profit rose 6% organically, while the adjusted margin improved by 0.1 percentage points organically. That is more modest, but still a genuine step forward.
| 6 months to Jun 2026 | 6 months to Dec 2025 | 6 months to Jun 2025 | 6 months to Dec 2024 | 6 months to Jun 2024 | 6 months to Dec 2023 | 6 months to Jun 2023 | 6 months to Dec 2022 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 863.8 | 880.7 | 822.2 | 838.2 | 827.0 | 831.8 | 850.8 | 860.5 |
| Operating income | 154.2 | 158.6 | 106.8 | 157.4 | 147.2 | 152.2 | 132.2 | 176.7 |
| Net income | 97.5 | 100.7 | 62.7 | 100.0 | 91.2 | 100.7 | 82.9 | 127.6 |
| EPS, diluted | 132.00 | 136.40 | 84.80 | 135.30 | 123.60 | 136.60 | 112.30 | 172.90 |
| = Free cash flow | 41.0 | 147.0 | 38.1 | 143.4 | 23.7 | 135.4 | 14.0 | 71.7 |
What this means. The table's free cash flow is lower because it also subtracts lease payments and interest paid, even though the definition says it only subtracts spending on equipment.