Spirax stock forecast 2027–2029
MyStockButler's October 2026 analysis: The weighted scenario is 7,434.58 GBp in October 2027, using the stated price on 30 October 2026. It hinges on whether growth becomes durable cash recovery without another margin setback.
Where could Spirax's shares be by 2029?
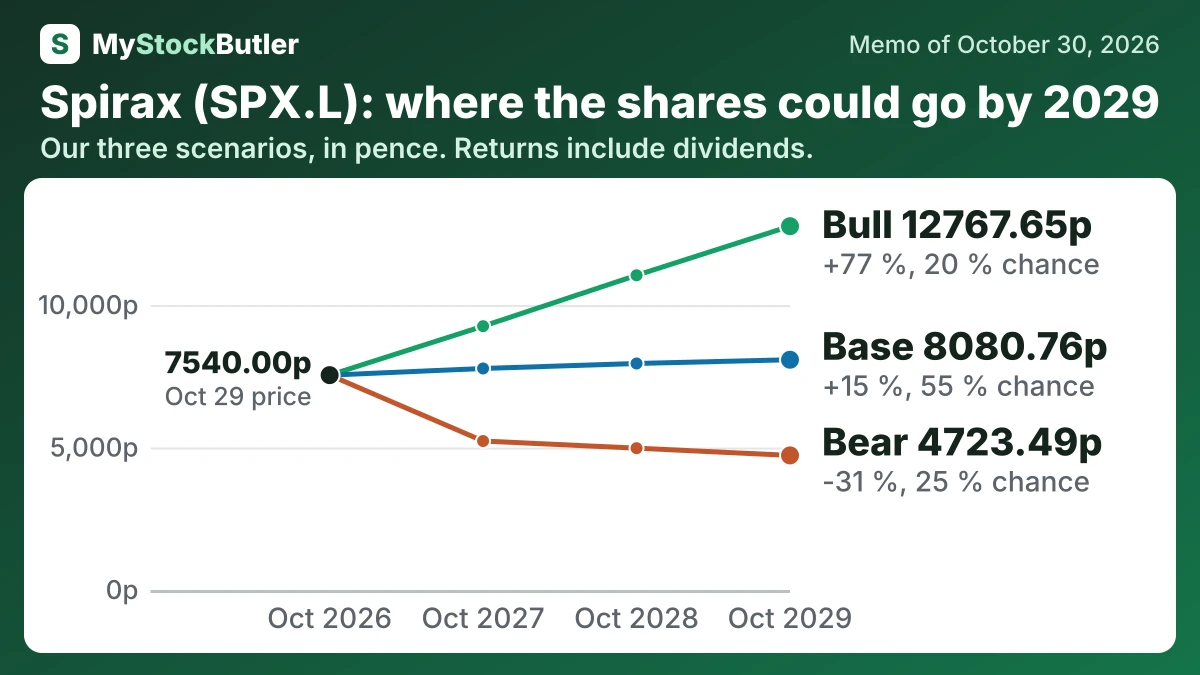
Our weighted value is 7,434.58 GBp in October 2027, a 1% return, and 8,178.82 GBp in October 2029, a 16% return. Bear, base and bull probabilities are 25%, 55% and 20%. The bear case gains weight during 2027–2029 if project delays, weak ETS throughput or WMFTS replenishment orders slow earnings and cash recovery. The bull case needs higher Ogden utilisation, durable WMFTS demand and paid decarbonisation projects. Spirax’s value turns on whether growth becomes durable cash recovery without another margin setback.
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 25 % | 5227.69 (-28 %) | 4976.94 (-29 %) | 4723.49 (-31 %) |
| Base | 55 % | 7774.44 (+5 %) | 7949.29 (+10 %) | 8080.76 (+15 %) |
| Bull | 20 % | 9258.58 (+25 %) | 11044.97 (+52 %) | 12767.65 (+77 %) |
| Weighted | 100 % | 7434.58 (+1 %) | 7825.34 (+9 %) | 8178.82 (+16 %) |
What has to go right or wrong for Spirax?
The bear case requires project delays, weak ETS throughput and WMFTS orders that prove partly to be inventory replenishment.
The price reaches 9,258.58 GBp in October 2027 and 12,767.65 GBp by October 2029. Its probability is 20% because several unproven improvements must occur together. The base case receives 55% because moderate growth and gradual margin recovery fit recent performance and current guidance.
How much cash does Spirax really make?
CEO Nimesh Patel took the role in January 2024 after serving as Spirax’s finance chief from 2020. CFO Louisa Burdett joined in July 2024 after finance roles at Croda, Meggitt and Victrex. Their annual incentive rewards operating profit, revenue, cash conversion and strategic objectives. Each received 59.6% of maximum for 2025. Patel held 25,665 shares and Burdett held 306 shares at 31 December 2025. Stock pay was £6.4 million in 2025, while diluted shares changed by 0.0%.
Real free cash flow — Restructuring payments of £22.1 million reduced 2025 real free cash flow to £178.7 million; without them, it was £200.8 million.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| = Free cash flow | 185.1 | 167.1 | 149.4 | 108.4 | 200.4 |
| − Stock pay | 6.4 | 3.1 | 6.1 | 8.9 | 9.2 |
| = Real free cash flow | 178.7 | 164.0 | 143.3 | 99.5 | 191.2 |
| Free cash flow — the company's own count | 199.0 | 173.2 | 153.3 | 116.1 | 194.5 |
What does an investor pay for Spirax today?
| Today (Oct 30, 2026) | |
|---|---|
| Share price | 7540.00 |
| Market value (calculated) | 5,566.5 |
| Enterprise value (calculated) | 6,184.7 |
| P/E, last 12 months (calculated) | 28.1x |
| P/E, next 12 months (calculated) | 23.4x |
| Real free cash flow yield (calculated) | 3.2% |
What this means. Enterprise value is higher than market value because it includes the company's debt and subtracts its cash.