Roper earnings: guidance and what to watch
MyStockButler's October 2026 analysis: Roper’s next results are expected on January 26, 2027. The key watch is whether collections support annual guidance after the pump sale and expected cash arrive.
What has Roper guided for the current year?
Management’s live target, issued October 22, 2026, is adjusted diluted earnings per share of $22.35–$22.40 for 2026. It includes $5.95–$6.00 for the fourth quarter of 2026. “Diluted” allows for shares that could be issued through employee awards. “Adjusted” removes selected accounting items. Roper also expects more than 8% total revenue growth and approximately 6% organic growth. Organic growth comes from businesses it already owns, so it shows whether existing customers are buying more rather than merely whether Roper has become larger through acquisitions.
GAAP earnings are higher because the adjustment is unusual this year. GAAP is the standard accounting result; adjusted earnings are management’s view after removing selected items. Roper guides to $25.60–$25.65 of GAAP diluted EPS for 2026, partly because gains linked to its Indicor investment exceed the acquisition-related amortization that adjusted earnings add back. That amortization is the paper expense assigned to purchased customer relationships and technology. Roper expects $663 million after tax of it in 2026, or $6.56 per share. Neither measure equals cash: amortization is non-cash, while an investment gain may not be immediately spendable.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Adjusted DEPS (FY 2026) | Year to Dec 2026 | 22.35 | 22.40 | Oct 22, 2026 |
| Adjusted DEPS (Q4 2026) | Quarter to Dec 2026 | 5.95 | 6.00 | Oct 22, 2026 |
| GAAP DEPS (FY 2026) | Year to Dec 2026 | 25.60 | 25.65 | Oct 22, 2026 |
| GAAP DEPS (Q4 2026) | Quarter to Dec 2026 | 4.27 | 4.32 | Oct 22, 2026 |
| Total revenue growth | Year to Dec 2026 | >8.0% | Oct 22, 2026 | |
| Organic revenue growth | Year to Dec 2026 | Approximately 6.0% | Oct 22, 2026 |
Has Roper kept its past promises?
The record earns management a strong but imperfect mark. All eight checked quarterly adjusted-earnings results exceeded the original upper endpoint. But on October 23, 2025, Roper lowered its annual adjusted-earnings upper endpoint from $20.05 to $19.95, citing acquisition dilution. That annual revision, rather than a quarterly miss, keeps the promise from being perfect.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Adjusted DEPS | 8 quarters | 8 | 0 | 0 |
What do Roper’s recent results show?
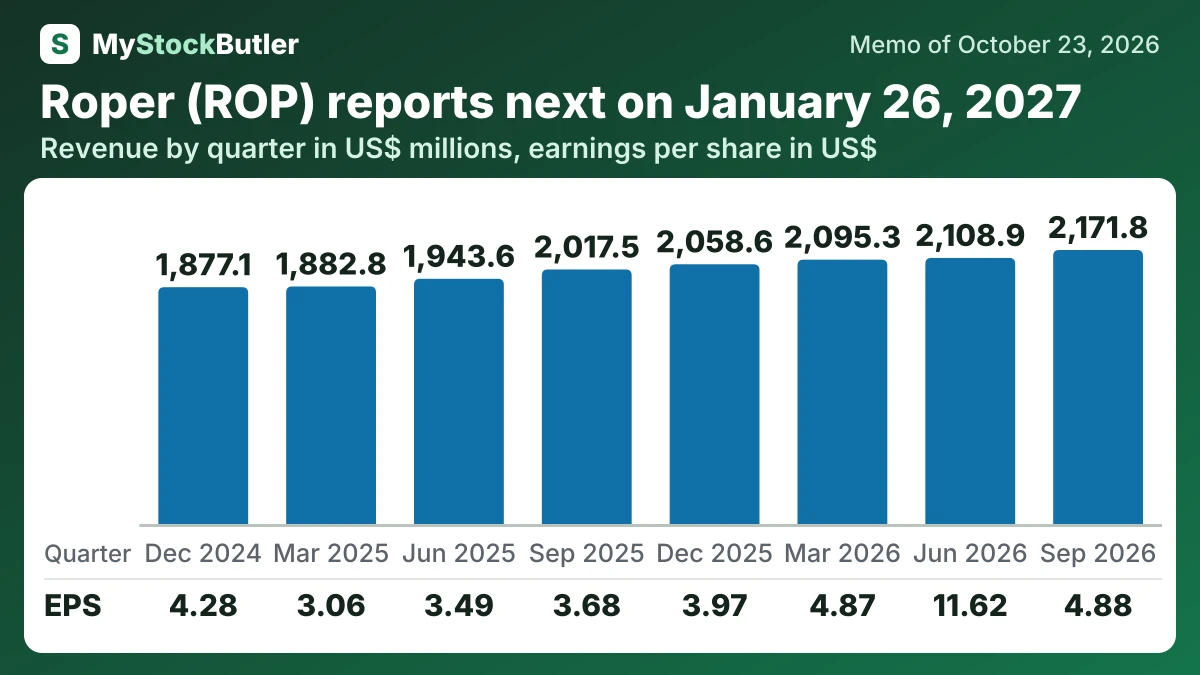
The third quarter of 2026 showed stronger organic growth and operating profit, but investment gains inflated earnings while collections lagged.
Revenue reached $2.2 billion, up from $2.0 billion a year earlier. Organic growth was 7%, with acquisitions adding 1%. Gross margin improved to 70.1%, and operating income rose to $623.2 million. Application Software improved, while Network Software and Technology Enabled Products declined, partly because weaker Neptune demand and a greater mix of mechanical meters affected the latter segment.
| Sep 2026 | Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 2,171.8 | 2,108.9 | 2,095.3 | 2,058.6 | 2,017.5 | 1,943.6 | 1,882.8 | 1,877.1 |
| Gross margin | 70.1% | 69.7% | 69.4% | 69.5% | 69.5% | 69.2% | 68.7% | 68.3% |
| Operating income | 623.2 | 584.7 | 569.6 | 588.3 | 573.0 | 548.3 | 525.8 | 524.7 |
| Net income | 484.7 | 1,168.5 | 508.9 | 428.4 | 398.5 | 378.3 | 331.1 | 462.3 |
| EPS, diluted | 4.88 | 11.62 | 4.87 | 3.97 | 3.68 | 3.49 | 3.06 | 4.28 |
| = Free cash flow | 810.5 | 458.5 | 577.8 | 728.2 | 857.9 | 387.6 | 519.2 | 695.4 |
What this means. The unusually high profit in June 2026 came largely from a paper gain on an investment, so it was not cash the company received.