Nordson stock forecast 2027–2029
MyStockButler's October 2026 analysis: Nordson’s weighted forecast is $314.54 in October 2027 and $359.98 in October 2029, with 28% bear, 52% base and 20% bull probabilities. Nordson’s outcome hinges on converting an electronics-led recovery and acquisitions into cash returns that justify today’s price.
Where could Nordson’s shares be by October 2029?
The forecast points to roughly flat returns after one year, followed by moderate gains if Nordson’s recovery continues. The probability-weighted price is $314.54 in October 2027, $333.99 in October 2028 and $359.98 in October 2029, equivalent to returns of -0%, 7% and 17% with dividends. The range in October 2029 is wide: $238.61 in the bear case to $474.69 in the bull case, against today’s $318.84.
The probabilities are 28% bear, 52% base and 20% bull, so the base case is the forecast’s centre of gravity.
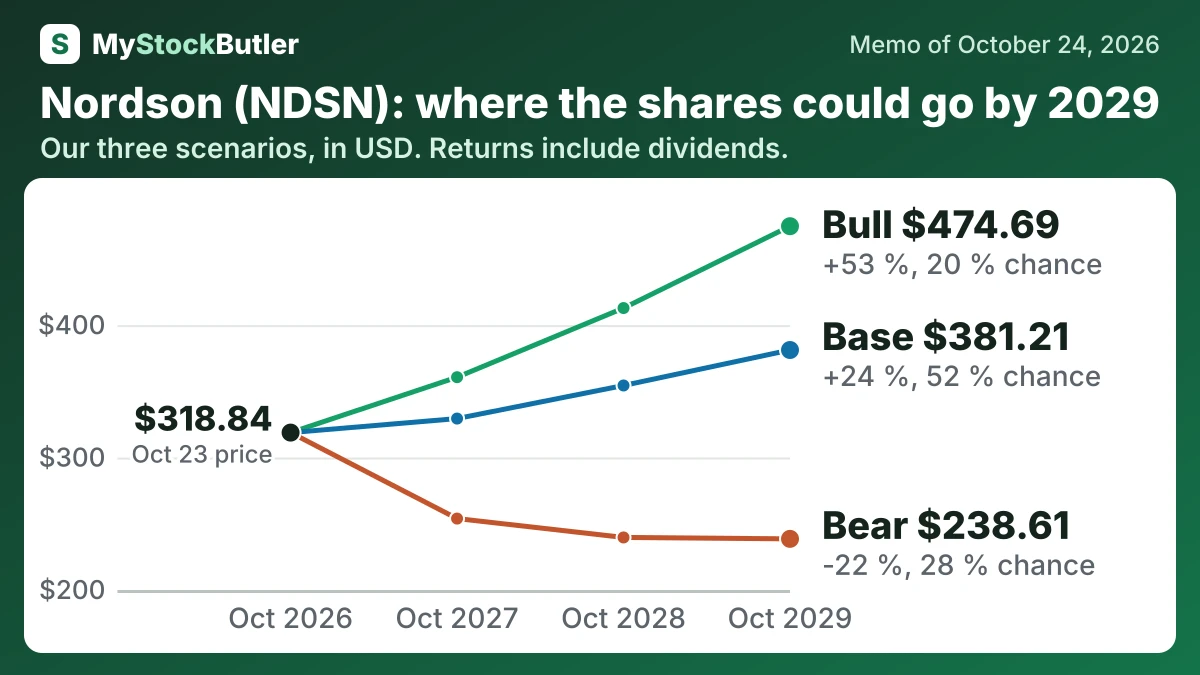
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 28 % | 253.93 (-19 %) | 239.68 (-22 %) | 238.61 (-22 %) |
| Base | 52 % | 329.44 (+5 %) | 354.42 (+14 %) | 381.21 (+24 %) |
| Bull | 20 % | 360.67 (+14 %) | 412.88 (+32 %) | 474.69 (+53 %) |
| Weighted | 100 % | 314.54 (-0 %) | 333.99 (+7 %) | 359.98 (+17 %) |
What this means. The weighted row is the average expected share value after giving more influence to cases with higher probabilities.
What has to go right for Nordson, and what could go wrong?
Earnings provide the main difference between the paths. The base case rises from $729 million in October 2027 to $794 million in 2028 and $866 million in 2029. That reflects 10% annual adjusted EPS growth from the $11.93833 analyst estimate, supported by management’s 10–12% long-term EPS target. The bear case gives $616 million, $638 million and $668 million because an electronics pause leaves margins below the FY2025 adjusted level. The bull case gives $735 million, $817 million and $911 million because backlog conversion and broader medical and industrial growth sustain recent adjusted margins. Backlog was 35% above the prior year, and ATS organic sales grew 30.9% in the July quarter.
The bear case begins with a factory-spending pause that pushes EPS below the $11.94 estimate by October 2027. Medical and industrial demand remain soft, so EPS recovers slowly. By October 2029, weaker acquisition confidence and debt pressure reduce the multiple to 20x. The resulting prices are $253.93 initially and $238.61 finally. Its 28% probability reflects repeated organic declines from 2023 through 2025 and the concentration of the current recovery in electronics, partly offset by backlog support and the continuing dividend.
| October 2027 | October 2028 | October 2029 | |
|---|---|---|---|
| Earnings | 729 (616 / 735) | 794 (638 / 817) | 866 (668 / 911) |
| Shares (millions) | 55.30 (55.80 / 55.05) | 54.90 (55.90 / 54.40) | 54.50 (56.00 / 53.75) |
| Dividends per share | 3.85 (3.76 / 3.90) | 4.22 (3.76 / 4.48) | 4.63 (3.76 / 5.15) |
| Price to earnings | 25.00 (23.00 / 27.00) | 24.50 (21.00 / 27.50) | 24.00 (20.00 / 28.00) |
How much cash does Nordson really make?
Capital spending was only about 2.1% of 2025 sales, consistent with a business whose value also lies in engineering and customer relationships. After subtracting stock-based compensation, analytical “real free cash flow” was $642.2 million in 2025. The cash then has to be set against debt and the capital employed.
| Oct 2025 | Oct 2024 | Oct 2023 | Oct 2022 | Oct 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 719,175 | 556,193 | 641,282 | 513,131 | 545,927 |
| − Capital spending | 58,060 | 64,410 | 34,583 | 51,428 | 38,303 |
| = Free cash flow | 661,115 | 491,783 | 606,699 | 461,703 | 507,624 |
| − Stock pay | 18,944 | 18,957 | 22,710 | 30,748 | 22,757 |
| = Real free cash flow | 642,171 | 472,826 | 583,989 | 430,955 | 484,867 |
| Real free cash flow, % of revenue | 23.0% | 17.6% | 22.2% | 16.6% | 20.5% |
What this means. The company's own free cash flow is slightly higher in October 2022 and October 2021 only because its charts round the figures; it is not extra cash.