Lennox stock forecast 2027–2029
MyStockButler's October 2026 analysis: The weighted case points to $358.74 in October 2027. It hinges on residential recovery and sustained cash conversion.
Where could Lennox's shares be by 2029?
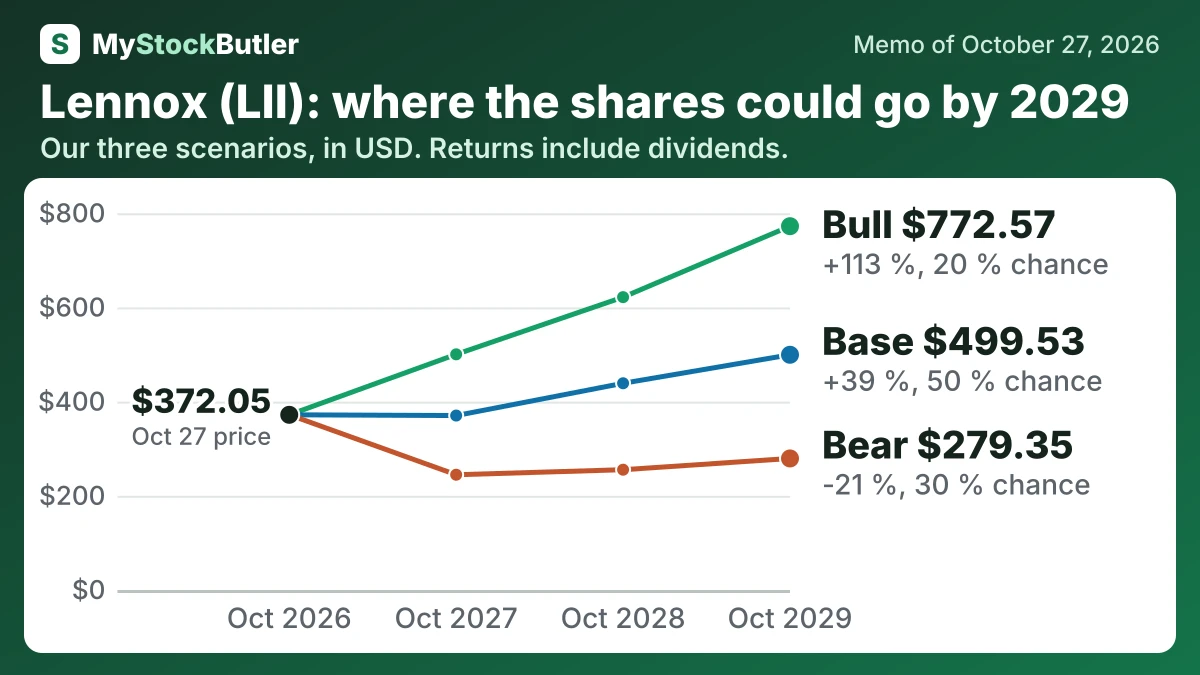
The weighted case points to $358.74 in October 2027 and hinges on residential recovery and sustained cash conversion. That first outcome is a 2% loss with dividends included. The weighted October 2029 price is $488.08. It represents a 36% return. The bear case has a 30% probability. The base case has 50%. The bull case has 20%.
The probability-weighted price is $358.74 in October 2027, a 2% loss including dividends. It rises to $420.54 in October 2028, a 16% gain. By October 2029, it reaches $488.08, a 36% gain.
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 30 % | 244.78 (-33 %) | 255.47 (-28 %) | 279.35 (-21 %) |
| Base | 50 % | 370.44 (+1 %) | 439.02 (+21 %) | 499.53 (+39 %) |
| Bull | 20 % | 500.44 (+36 %) | 621.93 (+70 %) | 772.57 (+113 %) |
| Weighted | 100 % | 358.74 (-2 %) | 420.54 (+16 %) | 488.08 (+36 %) |
What this means. The weighted row is the average value after giving more influence to the base case because it is considered more likely than the bear or bull case.
What has to go right for Lennox, and what could go wrong?
The bear case requires residential weakness to persist into 2027, leaving factories underused and forcing discounting or higher costs. Commercial and acquired growth fails to offset the core decline, cash flow stays weak and the multiple contracts. It leads to $244.78 in the first year and $279.35 by the last date. Its probability is 30% because volume and factory utilization remain the most failure-prone drivers.
| October 2027 | October 2028 | October 2029 | |
|---|---|---|---|
| Normal operating profit | 1,061 (908 / 1,202) | 1,159 (952 / 1,344) | 1,226 (1,044 / 1,518) |
| Shares (millions) | 34.40 (34.66 / 34.13) | 34.25 (34.76 / 33.74) | 34.10 (34.86 / 33.39) |
| Dividends per share | 5.72 (5.44 / 5.84) | 6.08 (5.44 / 6.40) | 6.48 (5.44 / 7.04) |
| Enterprise value to normal operating profit | 13.00 (10.50 / 15.00) | 13.50 (10.00 / 16.00) | 14.00 (9.50 / 17.00) |
| Net debt | 1,050 (1,050 / 950) | 610 (640 / 520) | 130 (180 / 10.00) |
How much cash does Lennox really make?
Lennox’s own free-cash-flow measure was $640.2 million. Deducting $29.1 million of stock compensation from $638.8 million of operating cash flow less capital spending produces an analytical “real free cash flow” of $609.7 million, reflecting dilution rather than a cash payment. Capital spending also fell from $250.2 million in 2023 to $118.8 million in 2025, so the lower requirement may not be permanent.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 757.6 | 945.7 | 736.2 | 302.3 | 515.5 |
| − Capital spending | 118.8 | 163.6 | 250.2 | 101.1 | 106.8 |
| = Free cash flow | 638.8 | 782.1 | 486.0 | 201.2 | 408.7 |
| − Stock pay | 29.1 | 28.5 | 30.1 | 21.8 | 24.3 |
| = Real free cash flow | 609.7 | 753.6 | 455.9 | 179.4 | 384.4 |
| Real free cash flow, % of revenue | 11.7% | 14.1% | 9.2% | 3.8% | 9.2% |
What this means. The company's free cash flow is slightly higher because it adds back money from selling property, while our count includes only money spent on property.
What does an investor pay for Lennox today?
Today’s price permits a recovery case, but it already requires earnings and cash generation to improve. The forward P/E is lower than the trailing P/E because future earnings are expected to rise. Using the rounded valuation multiples, forward EPS is about $25.66. Trailing EPS is about $22.55. That implies roughly 14% growth already embedded in the price.