Key earnings date and guidance
MyStockButler's October 2026 analysis: Key’s next results are expected on January 20, 2027. Watch whether repricing produces lasting improvement.
What has Key guided for FY2026?
Key could reach 20.88 by October 2029 for a positive 12% total return, if repricing and deposit costs deliver the earnings recovery and returns support the valuation. Management guides to 8% revenue growth and 10% net interest income growth for FY2026, with average loans up 5% and commercial loans up 10%. It targets a 3.3% net interest margin and 15% ROTCE for Q4 2027, then 16%–19% ROTCE over the long term. The plan includes 1,300 million of share repurchases and a 9.5%–10.0% long-term CET1 target.
| Period | Low | High | Date given | |
|---|---|---|---|---|
| Revenue | FY2026 growth vs FY2025 | 8.0% | 8.0% | Oct 20, 2026 |
| Net interest income | FY2026 growth vs FY2025 | 10.0% | 10.0% | Oct 20, 2026 |
| Net interest margin | Quarter to Dec 2026 | 3.0% | 3.0% | Oct 20, 2026 |
| ROTCE — 4Q27 target | Quarter to Dec 2027 | 15.0% | Oct 20, 2026 | |
| ROTCE — long-term target | Long term | 16.0% | 19.0% | Oct 20, 2026 |
| Share repurchases | FY2026 | 1,300 | 1,300 | Oct 20, 2026 |
What this means. The 3.3% net interest margin target is actually a 3.25% minimum rounded to one decimal place.
Has Key kept its promises?
Management has also begun delivering on public promises. In January 2026, it planned at least US$300 million of first-quarter buybacks; actual repurchases reached US$389 million. Return on tangible common equity, or ROTCE, measures profit against common shareholders’ capital after removing goodwill, other intangible assets and preferred stock. Key reported quarterly ROTCE of 15.11% in its October 20 results.
Management also reaffirmed a fourth-quarter 2027 floor for net interest margin and return on tangible common equity, followed by a higher long-term return range. Tangible common equity is shareholders’ capital after goodwill and other intangible assets are removed. Key exceeded the promised return floor in Q3 2026, but one strong quarter does not prove that the result can last.
What is Key’s revenue and profit trend?
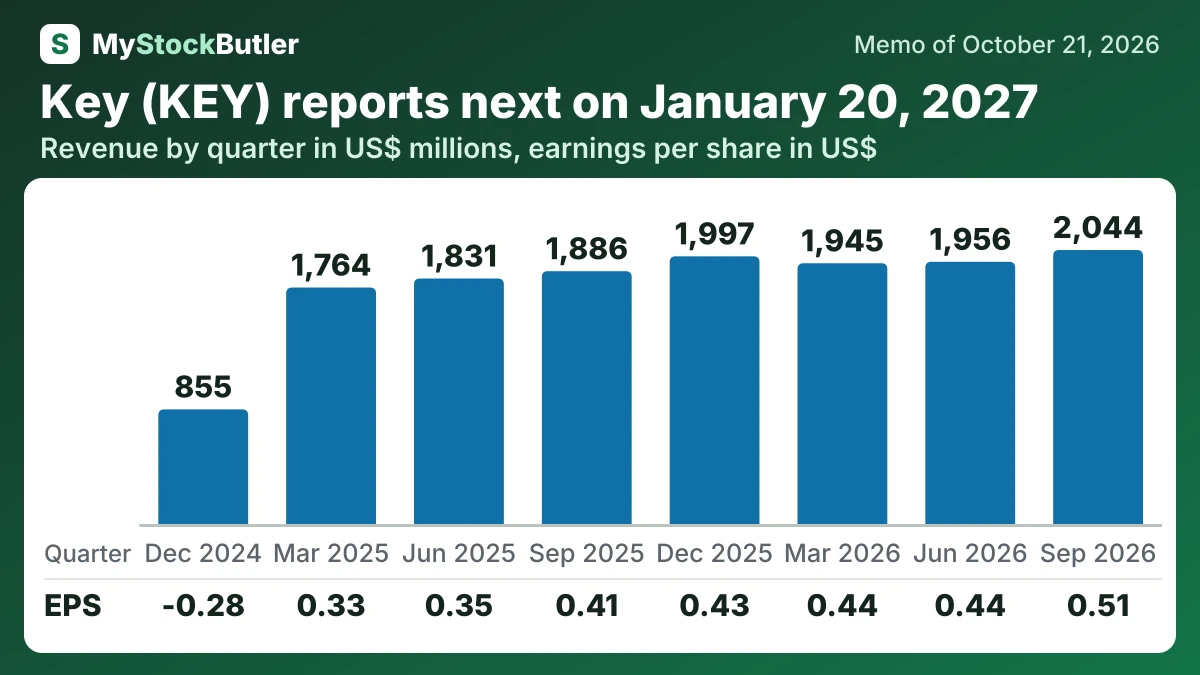
Revenue rose to $2,044 million from $1,886 million a year earlier, and net interest income rose to $1,300 million from $1,184 million. Net income reached $579 million, while diluted EPS reached $0.51. The quarterly progression suggests improvement in the business rather than one isolated result.
| Sep 2026 | Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 2,044 | 1,956 | 1,945 | 1,997 | 1,886 | 1,831 | 1,764 | 855 |
| Net interest income | 1,300 | 1,250 | 1,222 | 1,215 | 1,184 | 1,141 | 1,096 | 1,051 |
| Net income | 579 | 508 | 522 | 509 | 490 | 423 | 406 | -244 |
| EPS, diluted | 0.51 | 0.44 | 0.44 | 0.43 | 0.41 | 0.35 | 0.33 | -0.28 |
What this means. For this bank, revenue is not just sales: it is net interest income plus other income, so it can look close to net interest income.
What should I watch in Key’s next results?
Management said it would provide more specific targets and discuss future buybacks at that time. Investors should see whether loan growth is funded by deposits, whether expenses remain controlled, whether credit losses stay contained and whether Clearwater adds meaningful fee income. The margin target for Q4 is the immediate operating test; the longer test is whether repricing produces lasting improvement.