CPKC stock forecast 2027–2029
MyStockButler's October 2026 analysis: The weighted scenario for CPKC is C$129.72 in October 2027. It hinges on traffic converting into durable earnings and cash after investment and debt service.
Where could CPKC's shares be by October 2029?
The probability-weighted share price is C$129.72 in October 2027, for a 4% total return including dividends from today’s C$125.70. It rises to C$137.61 in October 2028, an 11% return, and C$146.83 in October 2029, a 20% return. By the last date, the bear case reaches C$93.28 while the bull case reaches C$214.49.
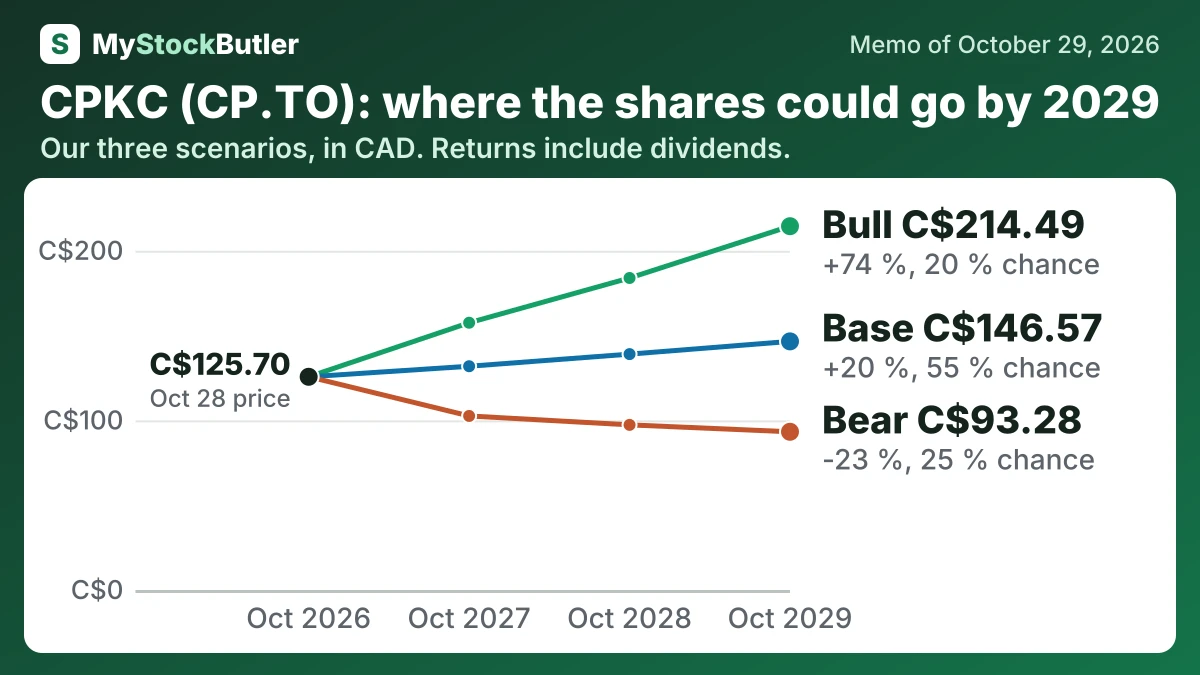
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 25 % | 102.61 (-18 %) | 97.35 (-21 %) | 93.28 (-23 %) |
| Base | 55 % | 131.92 (+6 %) | 139.07 (+13 %) | 146.57 (+20 %) |
| Bull | 20 % | 157.57 (+26 %) | 183.95 (+48 %) | 214.49 (+74 %) |
| Weighted | 100 % | 129.72 (+4 %) | 137.61 (+11 %) | 146.83 (+20 %) |
What this means. The weighted row is a probability-based average of the three cases, not a promise that the shares will reach that price.
What has to go right—and what could go wrong for CPKC?
The base case assumes 6% annual growth because trailing EBITDA was 5.2% above the prior year and management expects mid-single-digit revenue-ton-mile growth. CPKC’s history supports growth but not an unqualified acceleration: EBITDA rose from C$4.303 billion in 2021 to C$7.811 billion in 2025, with the merger distorting 2023. The bear case assumes a 3% first-year decline because trade, fuel and operating-ratio pressure could overwhelm volume growth. The bull case assumes 9% growth because the land bridge and productivity could convert into repeat traffic.
How much cash does CPKC really make?
Capital spending then takes priority. After capital spending and lease payments, basic free cash flow was lower than operating cash. A further deduction for stock compensation gives an analytical “real” free cash flow figure. That deduction is not another cash payment; it recognizes that stock issued as compensation still has an economic cost to shareholders.
CPKC’s own adjusted free-cash measure was higher because it added back or removed selected acquisition, tax, foreign-exchange and asset-sale items. Such adjustments can aid comparison, but the cash actually spent remains the harder number. In 2025, free cash flow fell from the prior year even though operating cash rose slightly, because capital spending increased.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 5,309 | 5,269 | 4,137 | 4,142 | 3,688 |
| − Capital spending | 3,140 | 2,863 | 2,499 | 1,557 | 1,532 |
| = Free cash flow | 2,158 | 2,393 | 1,625 | 2,481 | 2,148 |
| − Stock pay | 59 | 108 | 122 | 113 | 131 |
| = Real free cash flow | 2,099 | 2,285 | 1,503 | 2,368 | 2,017 |
| Real free cash flow, % of revenue | 13.9% | 15.7% | 12.0% | 26.9% | 25.2% |
What does an investor pay for CPKC today?
The price buys a valuable railway whose present cash return is modest, so the investment depends on future earnings growth.
| Today (Oct 29, 2026) | |
|---|---|
| Share price | 125.70 |
| Market value (calculated) | 109,459.56 |
| Enterprise value (calculated) | 134,906.56 |
| P/E, last 12 months (calculated) | 29.0x |
| P/E, next 12 months (calculated) | 21.1x |
| Real free cash flow yield (calculated) | 1.9% |
What this means. Enterprise value is higher than market value because it includes the company's debt along with its stock value, after subtracting its cash.