CPKC vs CN stock: the numbers side by side (October 2026)
How do CPKC and CN compare?
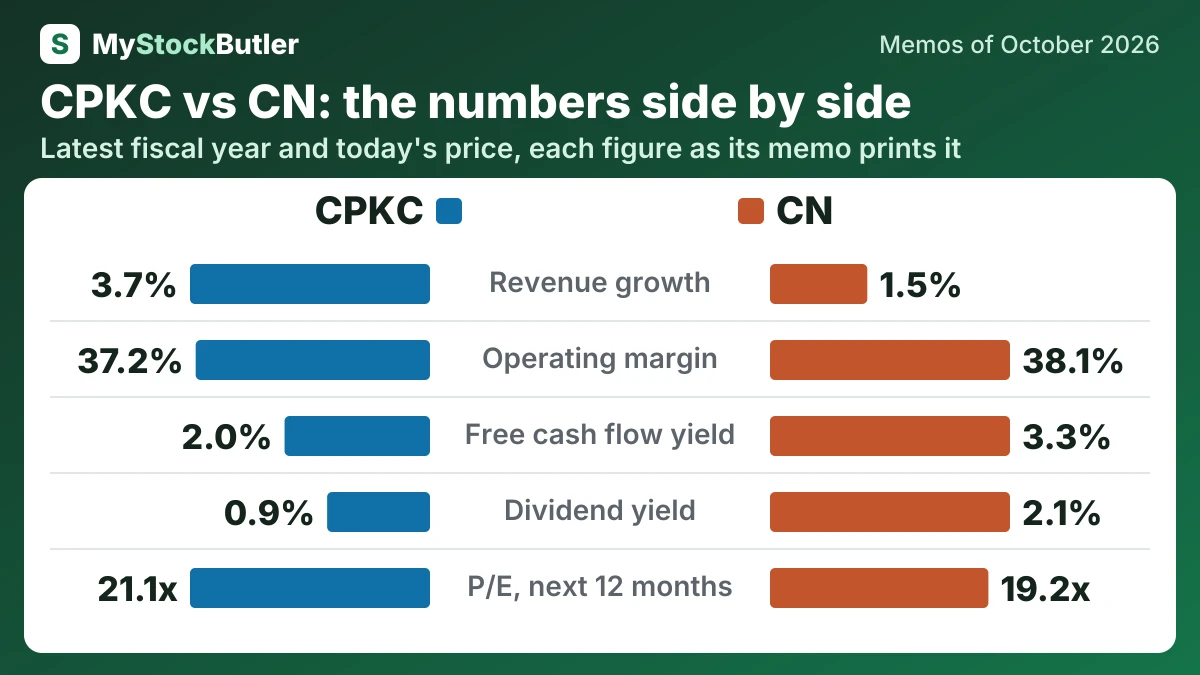
| CPKC CP.TO | CN CNR.TO | |
|---|---|---|
| Revenue growth | 3.7%2025 | 1.5%2025 |
| Operating margin | 37.2%2025 | 38.1%2025 |
| Free cash flow | 2,158C$ millions · 2025 | 3,389C$ millions · 2025 |
| Free cash flow yield | 2.0%Today (Oct 29, 2026) | 3.3%Today (Oct 31, 2026) |
| Dividend yield | 0.9%Today (Oct 29, 2026) | 2.1%Today (Oct 31, 2026) |
| P/E, last 12 months | 29.0xToday (Oct 29, 2026) | 21.7xToday (Oct 31, 2026) |
| P/E, next 12 months | 21.1xToday (Oct 29, 2026) | 19.2xToday (Oct 31, 2026) |
| Weighted price forecast, about 1 year | 129.72 (+4 %)October 2027 | 180.81 (+7 %)October 2027 |
| Weighted price forecast, about 3 years | 146.83 (+20 %)October 2029 | 211.65 (+29 %)October 2029 |
Who leads on what?
| Leads | The lead is | |
|---|---|---|
| Revenue growth | CPKC | The higher figure |
| Operating margin | CN | The higher figure |
| Free cash flow | CN | The higher figure |
| Free cash flow yield | CN | The higher figure |
| Dividend yield | CN | The higher figure |
| P/E, last 12 months | CN | The lower figure |
| P/E, next 12 months | CN | The lower figure |
| Weighted price forecast, about 1 year | CN | The higher weighted return |
| Weighted price forecast, about 3 years | CN | The higher weighted return |
What does each company do?
Canadian Pacific Kansas City (CPKC) sells freight transportation across Canada, the United States and Mexico.
CPKC (CP.TO), from our memo of October 29, 2026 · CPKC stock forecast
CN is a freight railway linking Canada’s Atlantic and Pacific coasts with the U.S. Midwest and Gulf Coast.
CN (CNR.TO), from our memo of October 31, 2026 · CN stock forecast
How big are CPKC and CN?
At CPKC, revenue came to C$15,078 million in 2025; at CN, it came to C$17,304 million in 2025.
How fast are CPKC and CN growing, and what did their latest results show?
Revenue at CPKC grew 3.7% in 2025, and revenue at CN grew 1.5% in 2025.
The September 2026 quarter brought more traffic and better operating income, but fuel and tax charges absorbed much of the gain below the line.
CPKC (CP.TO), from our memo of October 29, 2026 · CPKC earnings
Revenue rose 15% from the same quarter of 2025, while RTMs rose 4% and carloads edged down. Growth was uneven: grain and fertilizer improved, while intermodal, coal and forest products weakened. The quarter therefore looked stronger in dollars than across the entire network’s physical workload.
CN (CNR.TO), from our memo of October 31, 2026 · CN earnings
How much cash do CPKC and CN generate, and where does it go?
At CPKC, free cash flow came to C$2,158 million in 2025; at CN, it came to C$3,389 million in 2025. The dividend yield stood at 0.9% on October 29, 2026 for CPKC and 2.1% on October 31, 2026 for CN.
Capital spending then takes priority. After capital spending and lease payments, basic free cash flow was lower than operating cash. A further deduction for stock compensation gives an analytical “real” free cash flow figure. That deduction is not another cash payment; it recognizes that stock issued as compensation still has an economic cost to shareholders.
CPKC (CP.TO), from our memo of October 29, 2026 · CPKC stock forecast
CN’s 2025 operating cash exceeded net income, but that does not make the difference permanently spendable. Cash from working capital can reverse, and capital spending can be lumpy. The railway’s own free-cash-flow definition also differs from a stricter measure that subtracts lease payments and stock-based compensation.
CN (CNR.TO), from our memo of October 31, 2026 · CN stock forecast
What does an investor pay for CPKC and CN today?
CPKC traded at 29.0x the last 12 months’ earnings and 21.1x the next 12 months’ on October 29, 2026; CN traded at 21.7x the last 12 months’ earnings and 19.2x the next 12 months’ on October 31, 2026. At CPKC, the free cash flow yield was 2.0% on October 29, 2026; at CN, it was 3.3% on October 31, 2026.
The price buys a valuable railway whose present cash return is modest, so the investment depends on future earnings growth.
CPKC (CP.TO), from our memo of October 29, 2026 · CPKC stock forecast
The 3.3% free-cash-flow yield and 2.1% dividend yield suggest cash is being returned to shareholders, but buybacks can increase financial risk if they slow debt reduction. CN’s adjusted debt-to-adjusted EBITDA ratio was 2.61 at September 2026, and management expected it to return to about 2.5 times by year-end. The 10-year Government of Canada bond yield was 3.84% on October 29, 2026, giving investors a useful comparison for the income available from the shares.
CN (CNR.TO), from our memo of October 31, 2026 · CN dividend