Assurant stock forecast 2027–2029
MyStockButler's October 2026 analysis: The weighted scenario is $290.96 in October 2027 and $344.63 in October 2029. It hinges on durable profits, profitable growth and cash reaching the parent.
Where could Assurant's shares be by 2029?
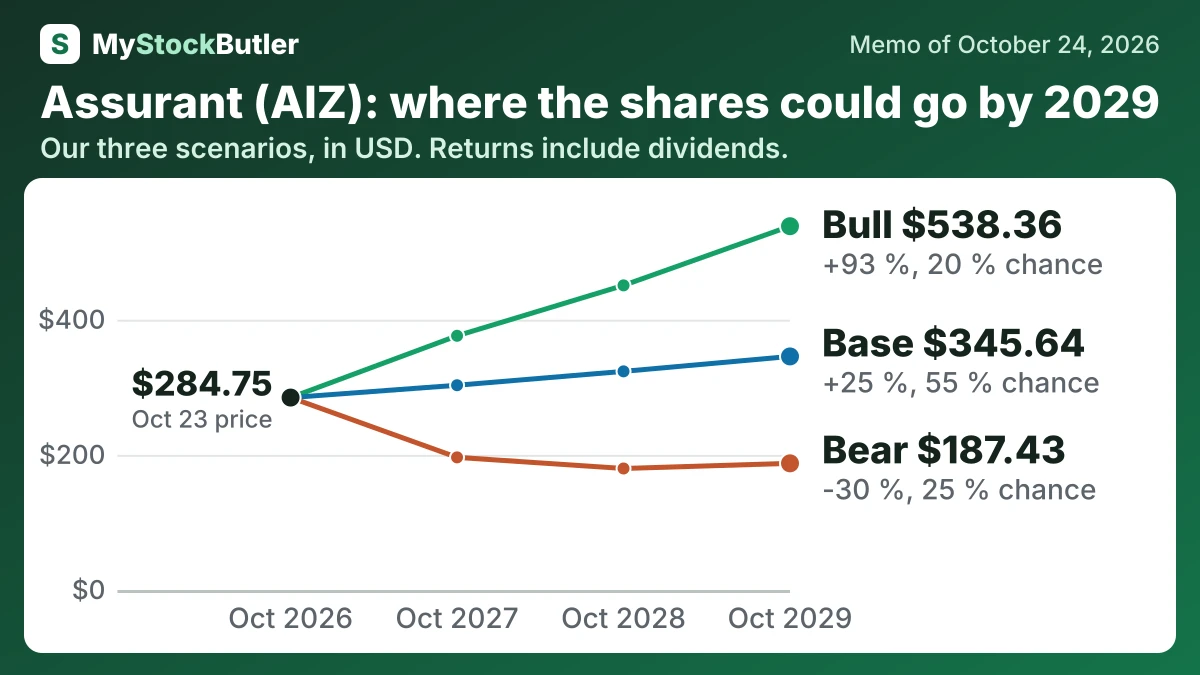
Assurant’s share could reach $290.96 in October 2027 and $344.63 in October 2029, but the outcome hinges on durable profits, profitable growth and cash reaching the parent. Management promises mid-single-digit growth in 2026 adjusted EBITDA and adjusted EPS excluding catastrophes, or 10.0% growth in both excluding prior-year development. The weighted forecast is $290.96 (+3%) at the first date and $344.63 (+25%) at the last, with bear, base and bull probabilities of 25%/55%/20%. The bear case brings normalized claims, higher catastrophe costs and fading reserve benefits. The bull case requires new programs to scale profitably. Key tests are ordinary claims, reserve development, Freedom Mortgage placements and Lifestyle margins. Third-quarter results arrive after market close on November 3, 2026, with the call on November 4. Home warranty launched in February 2026, and Freedom Mortgage began lender-placed services during Q2. Assurant’s value turns on whether service growth becomes profitable volume without consuming capital.
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 25 % | 196.26 (-30 %) | 179.81 (-34 %) | 187.43 (-30 %) |
| Base | 55 % | 303.02 (+8 %) | 323.56 (+16 %) | 345.64 (+25 %) |
| Bull | 20 % | 376.18 (+33 %) | 450.80 (+61 %) | 538.36 (+93 %) |
| Weighted | 100 % | 290.96 (+3 %) | 313.07 (+13 %) | 344.63 (+25 %) |
What this means. The weighted row is the average value after giving more influence to the case considered most likely.
What has to go right, and what could go wrong for Assurant?
The bear case starts at $900 million and falls to $855 million before recovering to $880 million. It assumes normalized claims, higher catastrophe costs and fading reserve benefits. The bull case starts at $1,200 million, reaches $1,320 million, and then $1,452 million as device, automotive and mortgage programs scale. Recent Lifestyle adjusted EBITDA growth supports that possibility, but first-half earnings also benefited from lower catastrophe losses.
The bull case requires several gains at once. Device and automotive growth must persist, Freedom Mortgage placements must become profitable, and home warranty must scale without absorbing its returns. Stronger cash remittances then support buybacks and dividends, while improved earnings quality lifts the P/E. The price reaches $376.18 first and $538.36 last. Its probability is 20%, because the opportunity is real but execution and catastrophe risks remain combined.
How much cash does Assurant really make?
Insurance reverses the usual commercial sequence: Assurant often receives premiums before it earns them and before it knows the final cost of claims. Operating cash flow reached $1.8 billion in 2025, against $1.3 billion in 2024, more than twice 2025 net income. That is encouraging, but it does not mean the difference is free cash.
The increase partly reflected business growth, an assumed Connected Living block and lower mobile-inventory outflows. Spending less on replacement or resale devices releases working capital; assuming a block can bring cash together with new obligations. After $235.5 million of property and other investing outflows, the apparent balance was about $1.6 billion, but claims, investments and regulated capital still compete for it.
What does an investor pay for Assurant today?
| Today (Oct 24, 2026) | |
|---|---|
| Share price | 284.75 |
| Market value (calculated) | 14,044.9 |
| P/E, last 12 months (calculated) | 13.6x |
| P/E on core earnings, last 12 months (calculated) | 12.0x |
| P/E, next 12 months (calculated) | 12.6x |
| Price to book (calculated) | 2.3x |
What this means. The insurer's core earnings still include losses from reported disasters, so they do not show only its usual ongoing profit.