Reckitt earnings: guidance and latest results
MyStockButler's October 2026 analysis: Reckitt's latest reported results showed Core Reckitt LFL growth of 4.2%, volume growth of 2.0%, Emerging Markets growth of 9.4%, North America growth of 2.8%, Europe decline of 1.5%, and Mead Johnson growth of 7.2%. Reckitt's next release must show whether the operating recovery is real and whether it can fund its future without an unexpected legal bill.
What has Reckitt guided for 2026?
“Core Reckitt” is the health-and-hygiene business built around brands such as Dettol, Lysol and Mucinex; Mead Johnson Nutrition, its infant-formula business, remains non-core. Management targets Core like-for-like growth of 4.0%–5.0% for the year, compared with 2.7% in the first half. Like-for-like growth compares the same continuing products at constant exchange rates. It can therefore rise even when reported Group revenue falls because a division has been sold or currencies have moved.
Profit must improve alongside sales. Reckitt guides to a 2026 adjusted operating margin of 24.9%–25.6%, or roughly £25 of operating profit for every £100 of sales. “Adjusted” excludes specified items such as some transformation costs, so it does not necessarily show how much cash remains.
| Period | Low | High | Given on | |
|---|---|---|---|---|
| Core Reckitt LFL net revenue growth (%) | Year to Dec 2026 | 4.0% | 5.0% | Sep 8, 2026 |
| Mead Johnson Nutrition LFL net revenue growth | Year to Dec 2026 | Jul 29, 2026 | ||
| Core Reckitt + MJN adjusted operating profit (AOP) margin (%) | Year to Dec 2026 | 24.9% | 25.6% | Jul 29, 2026 |
| Fixed costs as a percentage of net revenue (%) | Exit Dec 2027 | 19.0% | Sep 8, 2026 | |
| One-off cash restructuring and transformation costs (£ millions) | Fuel for Growth programme to Dec 2027 | 1,000 | 1,000 | Jul 29, 2026 |
What this means. The £1,000 million is the total cash cost of the Fuel for Growth programme through 2027, including money already spent, so it is not a cost expected only in 2026.
What has Reckitt delivered against its promises?
There is evidence that Licht’s promises produced results. The simplification plan delivered the disposal and a new operating structure, while Core Reckitt’s 2025 like-for-like revenue growth reached 5.2%. But only 45% of the main category-market combinations were holding or gaining share against a 60% ambition. Restructuring is therefore a milestone, not proof that the strategy has won customers.
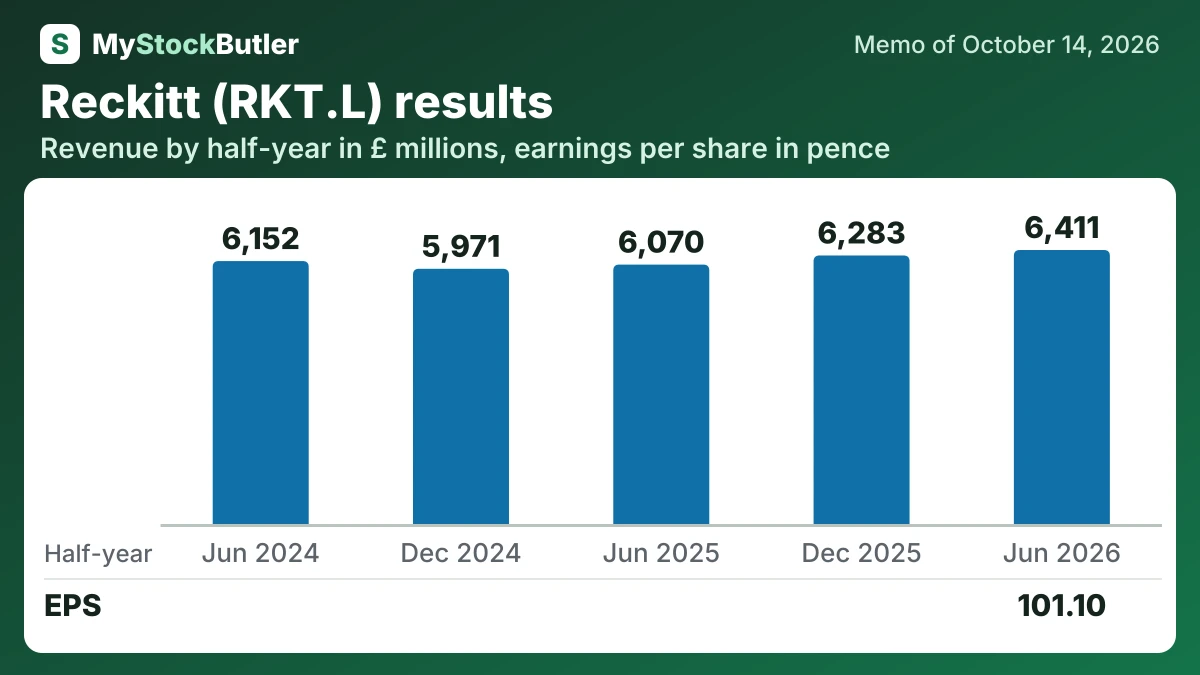
What is Reckitt's revenue and profit trend over the last eight reported periods?
Q2 provided better evidence of recovery. Core Reckitt’s LFL growth reached 4.2%, with volume contributing 2.0%. Emerging Markets grew 9.4%, North America returned to 2.8% growth, and Europe’s decline narrowed to 1.5%. Mead Johnson grew 7.2%, helped by a weak comparison. The test is whether this improvement survives stronger comparisons and the removal of transition work.
| 6 months to Jun 2026 | 6 months to Dec 2025 | 6 months to Jun 2025 | 6 months to Dec 2024 | 6 months to Jun 2024 | |
|---|---|---|---|---|---|
| Revenue | 6,411 | 6,283 | 6,070 | 5,971 | 6,152 |
| Gross margin | 58.5% | 61.8% | 62.1% | 61.8% | 61.7% |
| Operating income | 1,166 | ||||
| Net income | 655 | ||||
| EPS, diluted | 101.10 |
What this means. The interest paid row shows zero because the £152 million of interest is already included in cash from operations, so it is not subtracted twice.
What should Reckitt watch in the next release?
So the next update must answer two questions at once: is the operating recovery real, and can Reckitt fund its future without an unexpected legal bill changing the plan?