Pinnacle West stock forecast 2027–2029
MyStockButler's October 2026 analysis: In October 2029, the weighted price is $104.85. It hinges on whether rate recovery is timely.
Where could Pinnacle West’s shares go?
The weighted price is $100.19 in October 2027. That is a 2% loss including dividends. In October 2029, the weighted price is $104.85. That is a 10% gain. The forecast assigns 32% probability to the bear case and 53% to the base case. The bull case receives 15%.
PNW’s value depends on getting paid for growth before cash needs and dilution outrun earnings.
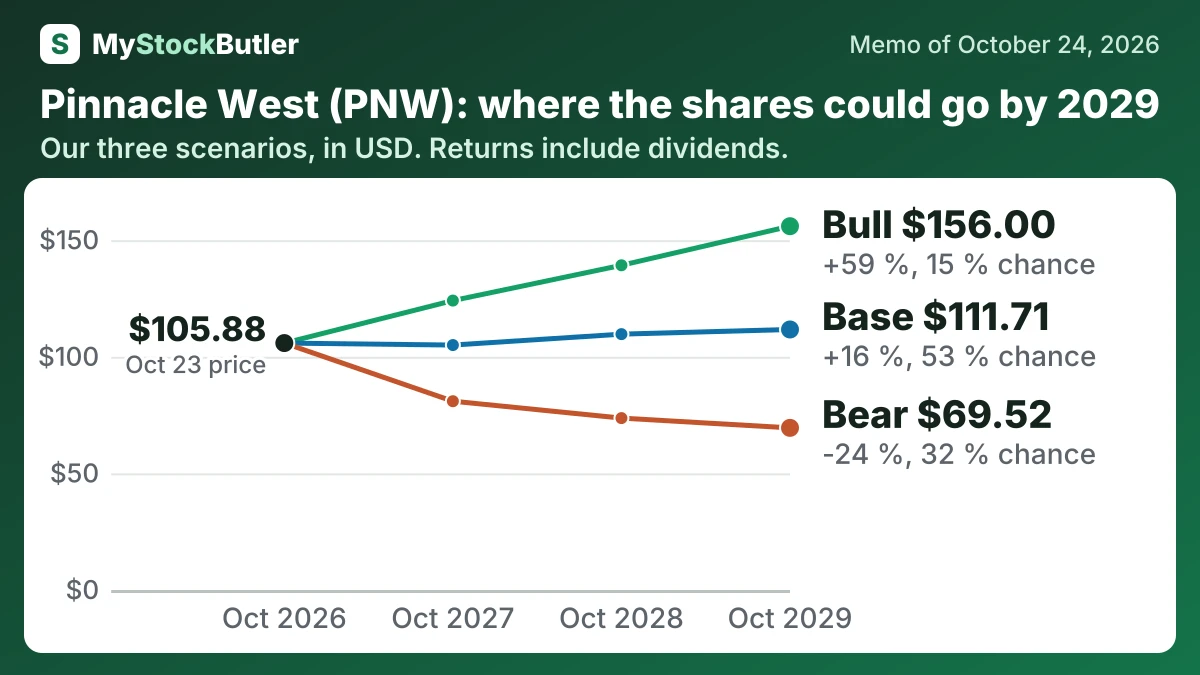
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 32 % | 80.95 (-20 %) | 73.70 (-23 %) | 69.52 (-24 %) |
| Base | 53 % | 105.03 (+3 %) | 109.71 (+11 %) | 111.71 (+16 %) |
| Bull | 15 % | 124.10 (+21 %) | 139.24 (+39 %) | 156.00 (+59 %) |
| Weighted | 100 % | 100.19 (-2 %) | 102.62 (+4 %) | 104.85 (+10 %) |
What could change Pinnacle West’s forecast?
The bear case gives earnings of $638 million in 2027 and $636 million in 2028. It reaches $660 million in 2029 because weak recovery and financing costs offset demand. The bull case gives $733 million in 2027 and $794 million in 2028, then $861 million in 2029 as load growth and timely asset additions lift EPS above target.
The base multiple is 19x in 2027 and 2028, then 18.5x in 2029. That is close to today’s valuation, but slightly cautious because the current multiple exceeds the company’s historical range. The bear case falls from 16x to 14x as recovery disappoints. The bull case rises from 21x to 23x if connected load and rate recovery make growth more dependable. Several supplied peers trade above 23x, but PNW still faces execution risk.
How much cash does Pinnacle West really make?
In 2025, Pinnacle West generated $1.8 billion of operating cash, almost three times net income. Depreciation explains part of the gap because it reduces accounting profit without requiring a current payment. Working capital also matters: APS released $178 million in 2025, partly collecting cash that had previously been tied up in receivables and other balances.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 1,805,095 | 1,609,823 | 1,207,697 | 1,241,441 | 860,014 |
| − Capital spending | 2,624,618 | 2,249,195 | 1,846,370 | 1,707,490 | 1,473,475 |
| = Free cash flow | -819,523 | -639,372 | -638,673 | -466,049 | -613,461 |
| − Stock pay | 27,457 | 23,532 | 17,341 | 15,942 | 18,460 |
| = Real free cash flow | -846,980 | -662,904 | -656,014 | -481,991 | -631,921 |
What this means. The company generated cash from daily operations but spent more on equipment, so free cash flow was negative.
What does an investor pay for Pinnacle West today?
| Today (Oct 24, 2026) | |
|---|---|
| Share price | 105.88 |
| P/E, next 12 months (calculated) | 19.1x |
| Free cash flow yield (calculated) | -6.4% |
| Real free cash flow yield (calculated) | -6.6% |
| Dividend yield (calculated) | 3.5% |
What this means. The whole business value is much higher than the stock-market value because the company has more debt than cash and short-term investments.