Pentair earnings date and guidance
MyStockButler's October 2026 analysis: Pentair’s next results are expected on February 2, 2027. Watch whether Pool inventory normalizes and Taco growth turns into cash that reduces debt.
What has Pentair guided for the full year?
Pentair’s share price can move higher if Pool shipments normalize, Taco delivers, and cash reduces debt. On October 27, 2026, management guided to a 3% full-year sales decline and adjusted EPS of $4.70. Management guided to full-year reported EPS of approximately $3.76. For the fourth quarter, reported sales should rise while core sales decline, with Taco included after its October 1 closing.
Pentair expects a difficult 2026, with a stronger-looking fourth quarter helped mainly by Taco. On October 27, management forecast lower full-year sales and a profit outlook that looks better under its adjusted measure than under standard accounting. It expects reported fourth-quarter sales to rise even as core sales decline, because Taco’s sales will enter the results after the October 1 acquisition.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Net sales — full year change (%) | Year to Dec 2026 | -3.0% | -3.0% | Oct 27, 2026 |
| Diluted earnings per ordinary share—as reported — full year | Year to Dec 2026 | 3.76 | 3.76 | Oct 27, 2026 |
| Diluted earnings per ordinary share—as adjusted — full year | Year to Dec 2026 | 4.70 | 4.70 | Oct 27, 2026 |
| Taco sales — 2027 estimate | Year to Dec 2027 | 620 | Oct 27, 2026 | |
| Taco EBITDA — 2027 estimate | Year to Dec 2027 | 105 | Oct 27, 2026 | |
| Adjusted EPS — full year change (%) | Year to Dec 2026 | -4.0% | -4.0% | Oct 27, 2026 |
What this means. The adjusted profit numbers are higher because they leave out certain costs, so they are not the company's full reported profit.
Did Pentair keep its past promises?
The forecast record is mixed. Pentair expected adjusted earnings per share of $4.65–$4.80 for 2025 and delivered $4.92. For 2026, management forecast $5.30–$5.40 in April but was guiding to about $4.70 by October after the Pool inventory correction.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| GAAP EPS from continuing operations | 8 quarters | 1 | 2 | 5 |
| adjusted EPS | 8 quarters | 7 | 0 | 1 |
| sales on a reported basis | 8 quarters | 5 | 2 | 1 |
How have Pentair’s revenue and profit trended?
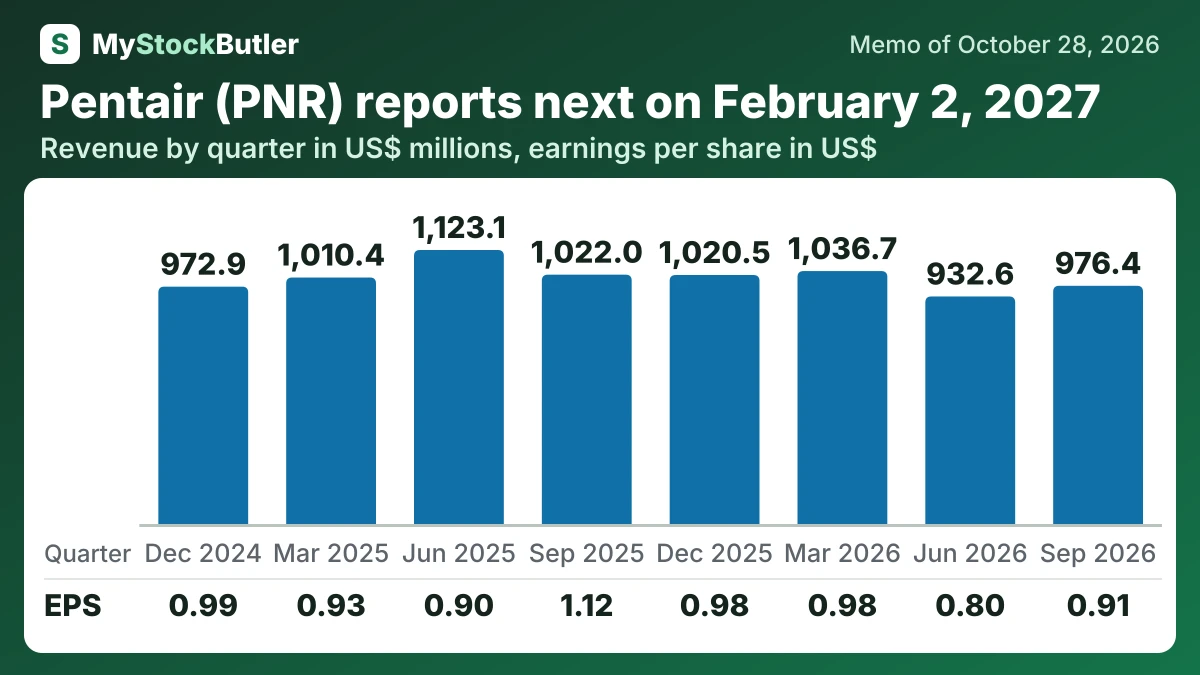
Revenue fell to $976.4 million from $1,022.0 million in the September 2025 quarter. Operating income fell to $195.9 million, while diluted earnings per share fell to $0.91. Gross margin also slipped, despite the tariff-refund benefit.
| Sep 2026 | Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 976.4 | 932.6 | 1,036.7 | 1,020.5 | 1,022.0 | 1,123.1 | 1,010.4 | 972.9 |
| Gross margin | 40.5% | 42.4% | 41.8% | 40.4% | 41.0% | 40.7% | 39.9% | 38.8% |
| Operating income | 195.9 | 166.5 | 210.0 | 205.0 | 231.7 | 217.7 | 203.1 | 195.1 |
| Net income | 145.1 | 128.6 | 160.8 | 161.8 | 184.3 | 148.5 | 154.9 | 166.4 |
| EPS, diluted | 0.91 | 0.80 | 0.98 | 0.98 | 1.12 | 0.90 | 0.93 | 0.99 |
What this means. The December 2025 and December 2024 cash-flow and capital-spending figures are calculated by subtracting the first nine months from the full year, so they are estimates of the quarter rather than directly reported quarterly amounts.
What should people watch in Pentair’s next results?
Pentair’s plan succeeds only if Taco grows, Pool channel inventories normalize and cash actually reduces debt; the next results should show whether those three claims are becoming one business.