Pentair dividend
MyStockButler's October 2026 analysis: Pentair pays a current quarterly dividend of $0.27 per share; its base forecast rises from $1.14 to $1.32 per share across the windows. In 2025, dividends and buybacks together used just over half of free cash flow, which was $746.0 million after $68.8 million of capital spending.
How much does Pentair pay per share?
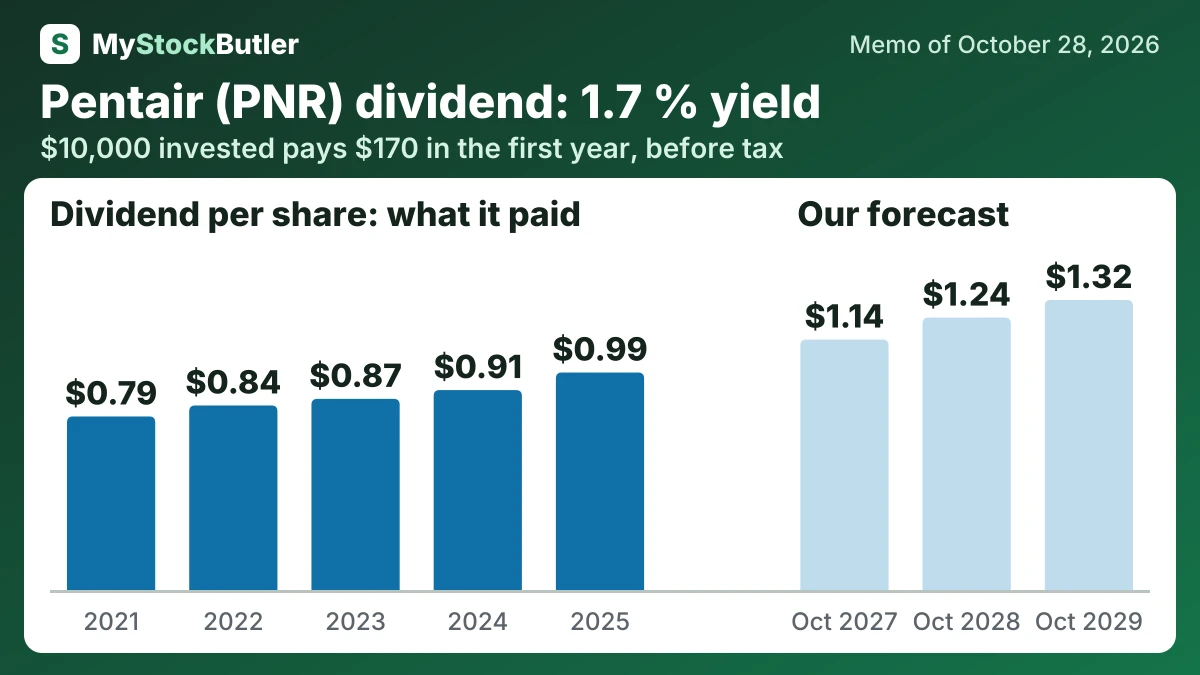
The base dividend rises from $1.14 to $1.32 per share across the windows. The bear holds it at $1.08, while the bull reaches $1.40. The base follows Pentair's 50-year record of increases but moderates the pace because the current quarterly rate is $0.27 and debt now competes for cash.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| EPS, diluted | 3.93 | 3.74 | 3.75 | 2.92 | 3.32 |
| Real free cash flow per share | 4.28 | 3.91 | 3.10 | 1.54 | 3.13 |
| − Dividends paid, per share | 0.99 | 0.91 | 0.87 | 0.84 | 0.79 |
| = FCF not paid out, per share | 2.16 | 2.34 | 2.40 | 0.55 | 1.61 |
How much would Pentair's dividend pay you?
$10,000 invested in Pentair at its 1.7% dividend yield (our report of October 28, 2026) pays $170.00 in the first year, before tax. If its dividend per share keeps changing 5.8% a year, as it did from 2021 to 2025, and the dividends are reinvested, year 10 pays $342.15, with $2,454.93 received in all.
Before tax. Past dividend growth is not a promise. Information only, not investment advice.
Is Pentair’s dividend covered by its cash?
The cash also went to shareholders. In 2025, dividends and buybacks together used just over half of free cash flow. Dividends pay cash directly; buybacks reduce the number of shares, which can increase each remaining share’s claim on future earnings. Their value depends on the price Pentair paid and on what else the cash could have financed.
Cash from operations was $814.8 million in 2025. After $68.8 million of capital spending, free cash flow was $746.0 million. This is cash left after investment in equipment and facilities, though the accounts do not show how much spending was strictly maintenance.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Free cash flow | 746.0 | 692.5 | 544.8 | 279.1 | 553.4 |
| − Dividends paid | 164.3 | 152.3 | 145.2 | 138.6 | 133.0 |
| − Share buybacks | 225.0 | 150.0 | 0 | 50.0 | 150.0 |
| = Free cash flow not paid out | 356.7 | 390.2 | 399.6 | 90.5 | 270.4 |
| Paid to shareholders | 389.3 | 302.3 | 145.2 | 188.6 | 283.0 |
| Paid out, % of free cash flow | 52.2% | 43.7% | 26.7% | 67.6% | 51.1% |
What could change Pentair’s dividend?
Taco sales or EBITDA below management's targets from 2027 through 2029 would also weaken earnings and leave borrowing costs competing with cash flow and buybacks. Recurring transformation costs or the loss of the $43 million tariff refund would further delay margin and leverage improvement.
| October 2027 | October 2028 | October 2029 | |
|---|---|---|---|
| Earnings | 843 (687 / 885) | 910 (678 / 981) | 948 (673 / 1,057) |
| Shares (millions) | 159 (160 / 157) | 158 (160 / 155) | 157 (160 / 153) |
| Dividends per share | 1.14 (1.08 / 1.16) | 1.24 (1.08 / 1.28) | 1.32 (1.08 / 1.40) |
| Price to earnings | 17.00 (13.00 / 20.00) | 17.50 (12.00 / 22.00) | 18.00 (11.00 / 24.00) |
What is Pentair’s dividend yield against its price?
Leverage supplies a second test. Hayward’s net debt was 1.9 times EBITDA at December 31, 2025. Pentair must reduce its own borrowing while continuing to fund the business and its dividend.