PCA earnings date and guidance
MyStockButler's October 2026 analysis: PCA’s next results are expected on January 26, 2027. PCA’s next test is whether better mill performance and higher prices become durable cash after outages, investment and dividends.
What has PCA guided for Q4 2026?
Management guides to adjusted EPS of $2.81 for the quarter to December 2026. PCA targets $60 million of pretax Greif synergies by September 2027. The test is whether savings become cash after integration costs and interest. 2026 capital investments are guided at $840 million to $870 million. That includes $21 million for environmental compliance.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Earnings per share, excluding special items | Quarter to Dec 2026 | 2.81 | 2.81 | Oct 21, 2026 |
| Capital investments | Year to Dec 2026 | 840 | 870 | Aug 7, 2026 |
| Capital expenditures to comply with environmental regulations | Year to Dec 2026 | 21 | 21 | Aug 7, 2026 |
| Synergies, pre-tax benefits | By Sep 2027 | 60 | 60 | Jul 1, 2025 |
What this means. The synergies are expected savings before taxes that should build up by September 2027, not extra earnings in one year.
Has PCA kept its past promises?
Management’s record is moderately reliable, not exact. Adjusted EPS beat guidance across most of the checked quarters, while operating forecasts were easier to meet: containerboard production landed within expectations in every checked quarter. The important miss came in Q4 2025, when weaker volume and mix in the original corrugated business combined with weaker production and sales in the acquired Greif business. On a consistent basis, Q3 2025 was a beat because the original forecast excluded the acquisition.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Diluted EPS excluding Special Items | 8 quarters | 6 | 1 | 1 |
| Containerboard production | 6 quarters | 0 | 6 | 0 |
| Paper segment sales volume | 8 quarters | 3 | 4 | 1 |
What is PCA’s revenue and profit trend over the last eight quarters?
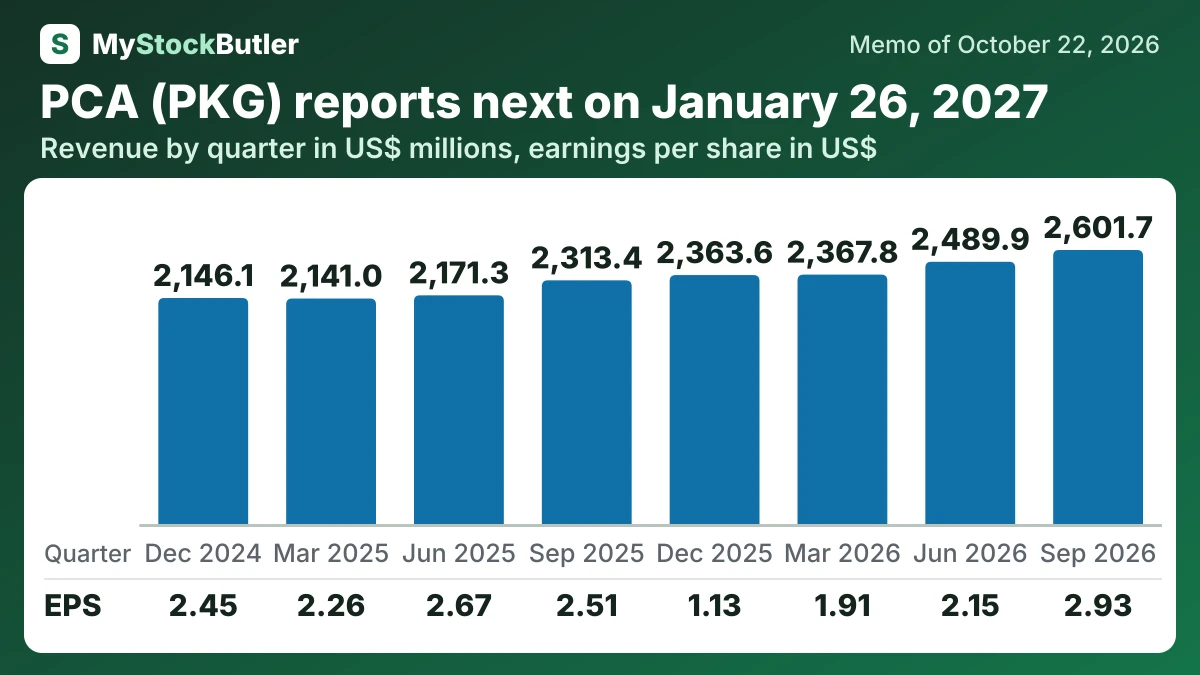
Revenue grew approximately 12.5% year over year in the September quarter. Operating income, net income and gross margin also improved, making the quarter stronger than the first half. The improvement reflects both a larger business and better profitability.
| Sep 2026 | Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 2,601.7 | 2,489.9 | 2,367.8 | 2,363.6 | 2,313.4 | 2,171.3 | 2,141.0 | 2,146.1 |
| Operating income | 385.3 | 291.2 | 251.3 | 168.5 | 324.5 | 333.7 | 280.3 | 302.2 |
| Net income | 262.3 | 192.1 | 170.9 | 101.8 | 226.9 | 241.5 | 203.8 | 221.1 |
| EPS, diluted | 2.93 | 2.15 | 1.91 | 1.13 | 2.51 | 2.67 | 2.26 | 2.45 |
What this means. Free cash flow is blank for the quarter ending September 2026 because the company did not report the cash from its daily business, not because it was zero.
What should I watch in PCA’s next release?
The decisive evidence will be whether better mill performance and higher prices become durable cash after outages, investment and dividends. For Q4 2026, watch outage duration, packaging prices and shipment mix together; higher production is not enough if freight, inventory or weak orders absorb the benefit. Through September 2027, test the $60 million synergy promise against earnings and cash.