Hiscox stock forecast 2027–2029
MyStockButler's October 2026 analysis: The weighted Hiscox scenario is 1,476.15p in October 2027, with the base case carrying a 52% probability. Hiscox’s outcome hinges on profitable Retail growth, durable underwriting and savings delivery.
Where could Hiscox’s shares be by 2029?
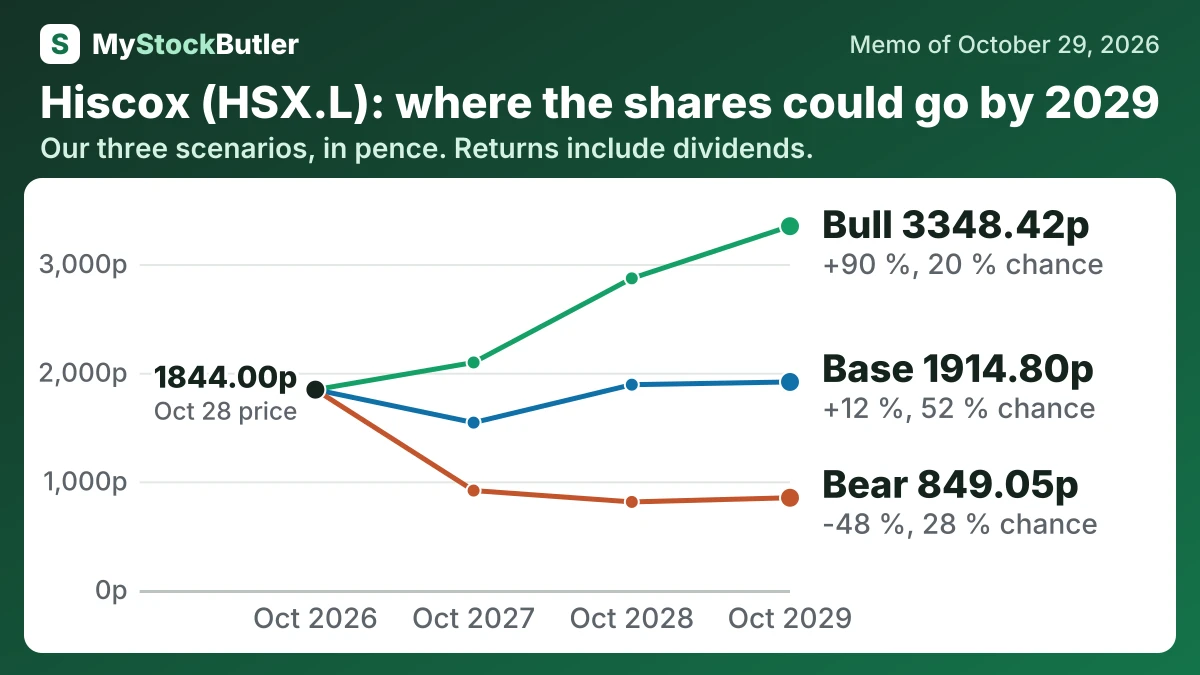
The weighted forecast is 1,476.15p in October 2027, an 18% decline including dividends. It reaches 1,903.11p in October 2029, an 11% gain including dividends. By the final forecast date, cases span 849.05p to 3,348.42p. The bear case carries a 28% probability. The base case carries 52%. The bull case carries 20%.
The range is much wider than the weighted path. By October 2029, the bear case gives 849.05p, while the bull case gives 3348.42p, against today’s 1844.00p. The probabilities are 28% bear, 52% base and 20% bull.
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 28 % | 915.11 (-48 %) | 810.54 (-52 %) | 849.05 (-48 %) |
| Base | 52 % | 1540.54 (-14 %) | 1889.72 (+7 %) | 1914.80 (+12 %) |
| Bull | 20 % | 2094.20 (+16 %) | 2868.33 (+61 %) | 3348.42 (+90 %) |
| Weighted | 100 % | 1476.15 (-18 %) | 1783.27 (+2 %) | 1903.11 (+11 %) |
What this means. The Weighted row is the probability-based average of the Bear, Base, and Bull cases, not a separate likely outcome.
What has to go right or wrong for Hiscox?
The bear case requires Retail growth to disappoint, acquisition costs to rise and reinsurance pricing to weaken. A major catastrophe or adverse reserve development would compound the damage, while missed savings would reduce margins. Capital preservation would stop buybacks. The bear case gives 915.11p at the first date. It gives 849.05p at the last. Its 28% probability reflects meaningful risk, but Hiscox remains profitable and capitalised.
The bull case requires profitable Retail expansion, successful automation and the $200m annual savings run rate from 2028. Catastrophes must remain manageable, reserves resilient and third-party capital fees supportive. The bull case gives 2094.20p at the first date. It reaches 3348.42p at the last. Its 20% probability reflects the number of favourable outcomes that must align.
How much cash does Hiscox really make?
Operating cash flow was only $72.8 million against $732.7 million of pre-tax profit in 2025. The apparent weakness reflects the way an insurer works. It receives premiums, invests them in bonds, sells or matures those investments, and later pays claims. Those investment transactions are classified as operating cash flows, so they can make cash conversion look volatile.
What does an investor pay for Hiscox today?
| Today (Oct 28, 2026) | |
|---|---|
| Share price | 1,844.0 |
| P/E, last 12 months (calculated) | 12.9x |
| P/E on core earnings, last 12 months (calculated) | 11.2x |
| P/E, next 12 months (calculated) | 12.3x |
| Price to book (calculated) | 2.0x |
| Dividend yield (calculated) | 2.1% |
What this means. The price-to-earnings ratio based on core earnings uses the insurer’s own measure of ongoing profit, so it may differ from the ordinary price-to-earnings ratio.