Fifth Third Bancorp earnings date
MyStockButler's October 2026 analysis: Fifth Third Bancorp expects its next results on January 19, 2027. Fifth Third Bancorp investors should watch whether integration savings become durable profit after the systems conversion.
What has Fifth Third Bancorp guided for the next quarter?
For the quarter ending December 31, 2026, management expects average loans and leases, net interest income and noninterest income to rise while noninterest expense falls. Net interest income is the profit from lending after paying interest to depositors and other funders. Fees from payments or investment management are noninterest income. Salaries, branches and technology are noninterest expenses.
Management also targets stronger profitability and efficiency for 2027. Return on tangible common equity, or ROTCE, asks how much profit the bank earns on shareholders’ tangible capital. The efficiency ratio asks how many cents of operating cost produce one dollar of revenue. Higher ROTCE and a lower efficiency ratio would show that Fifth Third is earning more from its resources.
| Period it covers | Low | High | Date given | |
|---|---|---|---|---|
| Avg. loans & leases | Quarter to Dec 2026 | 1.0% | 2.0% | Oct 19, 2026 |
| Net interest income | Quarter to Dec 2026 | 2.5% | 3.5% | Oct 19, 2026 |
| Noninterest income | Quarter to Dec 2026 | 2.0% | 4.0% | Oct 19, 2026 |
| Noninterest expense | Quarter to Dec 2026 | -3.0% | -2.0% | Oct 19, 2026 |
| Target ROTCE | Year to Dec 2027 | 19.0% | Sep 15, 2026 | |
| Target efficiency ratio | Year to Dec 2027 | 53.0% | 53.0% | Sep 15, 2026 |
What this means. The negative noninterest expense guidance means the company expects its costs to decrease, not that it will have negative costs.
Did Fifth Third Bancorp keep its past promises?
Management's promises were generally cautious on credit and achievable on expenses, but the initial 2023 net-interest-income growth target and 2021 expense-reduction target were too bold. The documented adverse revisions were repeated cuts to 2023 net-interest-income growth and increases to 2021 expected expenses; the annual forecasts reviewed were revised rather than explicitly withdrawn. The 2025 credit miss was largely explained by a $178 million fraud-related commercial-credit impairment, while 2023 income weakness reflected deposit repricing and migration into interest-bearing accounts, and the 2021 expense revisions incorporated higher servicing costs and the Provide acquisition.
| Metric | Record, last 5 years | Typical gap |
|---|---|---|
| net interest income | 4 of 5 inside or above initial guidance: 3 above, 1 inside, 1 below. The 2023 forecast was cut. | Median signed distance from the initial guidance boundary was approximately +0.1%; individual gaps ranged from -7.9% below the bottom to +12.1% above the top. Inside results count as zero. |
| expenses | 4 of 5 inside or below initial guidance: 3 below, 1 inside, 1 above. The 2021 expense forecast was increased twice. | Median signed distance from the initial guidance boundary was approximately -0.3%, favorable; the 2021 miss was approximately 4.9% above the initial implied expense amount. |
| loan losses — annual net charge-off ratio | 4 of 5 inside or below initial guidance: 2 below, 2 inside, 1 above. Lower losses are favorable; the 2025 reported ratio missed. | Median distance outside the initial range was 0 basis points; 2021 and 2022 were respectively 29 and 1 basis points below the bottom, while 2025 was 11 basis points above the top. |
What this means. A lower annual loan-loss ratio is better because it means the company had to write off less of its loans as uncollectible.
How have Fifth Third Bancorp’s revenue and profit trended?
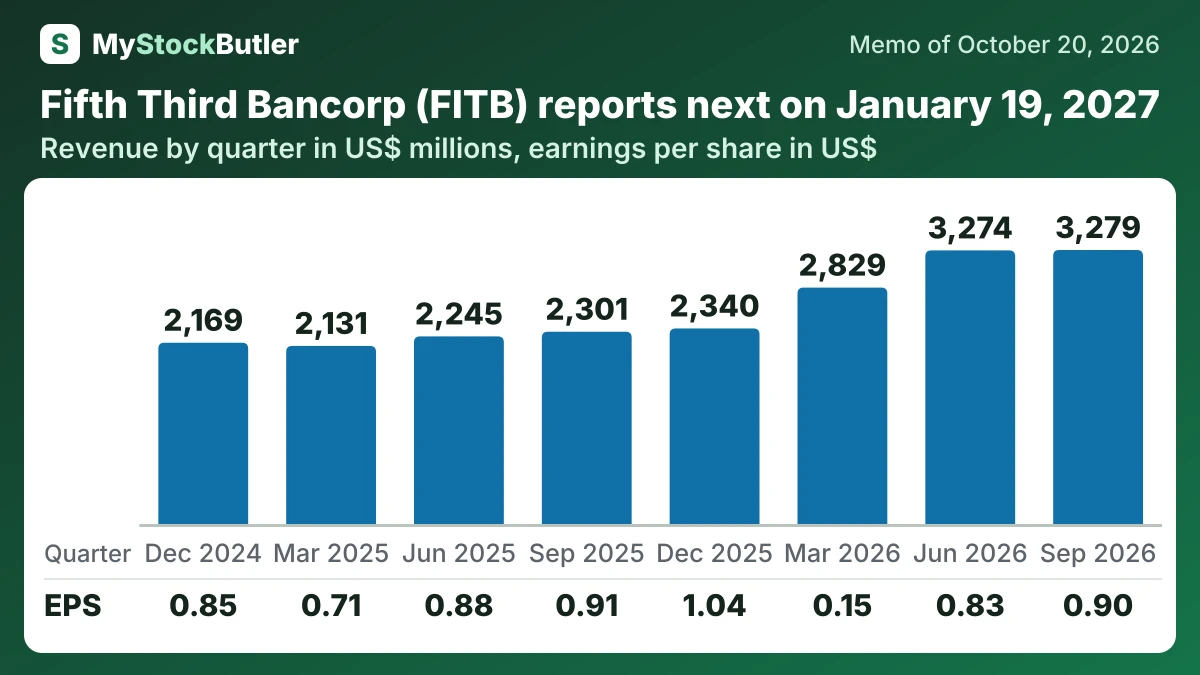
The sequential comparison is cleaner because both quarters include Comerica. Revenue was nearly unchanged, while net income, EPS and NII improved from Q2. That suggests progress in operating the combined bank, although reported fees weakened.
| Sep 2026 | Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 3,279 | 3,274 | 2,829 | 2,340 | 2,301 | 2,245 | 2,131 | 2,169 |
| Net interest income | 2,271 | 2,215 | 1,934 | 1,529 | 1,520 | 1,495 | 1,437 | 1,437 |
| Net income | 866 | 801 | 165 | 731 | 649 | 628 | 515 | 620 |
| EPS, diluted | 0.90 | 0.83 | 0.15 | 1.04 | 0.91 | 0.88 | 0.71 | 0.85 |
| Net interest margin | 3.3% | 3.4% | 3.3% | 3.1% | 3.1% | 3.1% | 3.0% | 3.0% |
| CET1 capital ratio | 10.0% | 9.9% | 9.9% | 10.8% | 10.6% | 10.6% | 10.4% | 10.6% |
What this means. The 2026 growth is not all from the bank's existing business because it includes Comerica after February 1, so some growth came from buying another bank.
What should I watch in Fifth Third Bancorp’s next results?
The quarter ending December 31, 2026 should show the full savings pace after the systems conversion. Early 2027 guidance should then reveal how much management keeps as profit and how much it reinvests. The useful test is recurring revenue against recurring costs, alongside deposits and credit quality.