AES stock forecast 2027–2029
MyStockButler's October 2026 analysis: AES's weighted forecast is $11.61 in October 2027. It hinges chiefly on the cash acquisition closing.
Where could AES's shares be by October 2029?
Management still targets annualized adjusted EBITDA growth of 5.0%–7.0% through 2027. It targets adjusted EPS growth of 7.0%–9.0% through 2027, measured from the 2023 guidance base. The bear case carries 22% probability; the base case carries 68%. The bull case carries 10%.
The probability-weighted price is $11.61 in October 2027, a 20% loss including dividends. It is $13.07 in October 2028, a 10% loss including dividends. By October 2029, it reaches $14.71, a 2% gain including dividends. The full 2029 range runs from $0.00 in the bear case to $46.53 in the bull case, against today’s $15.00.
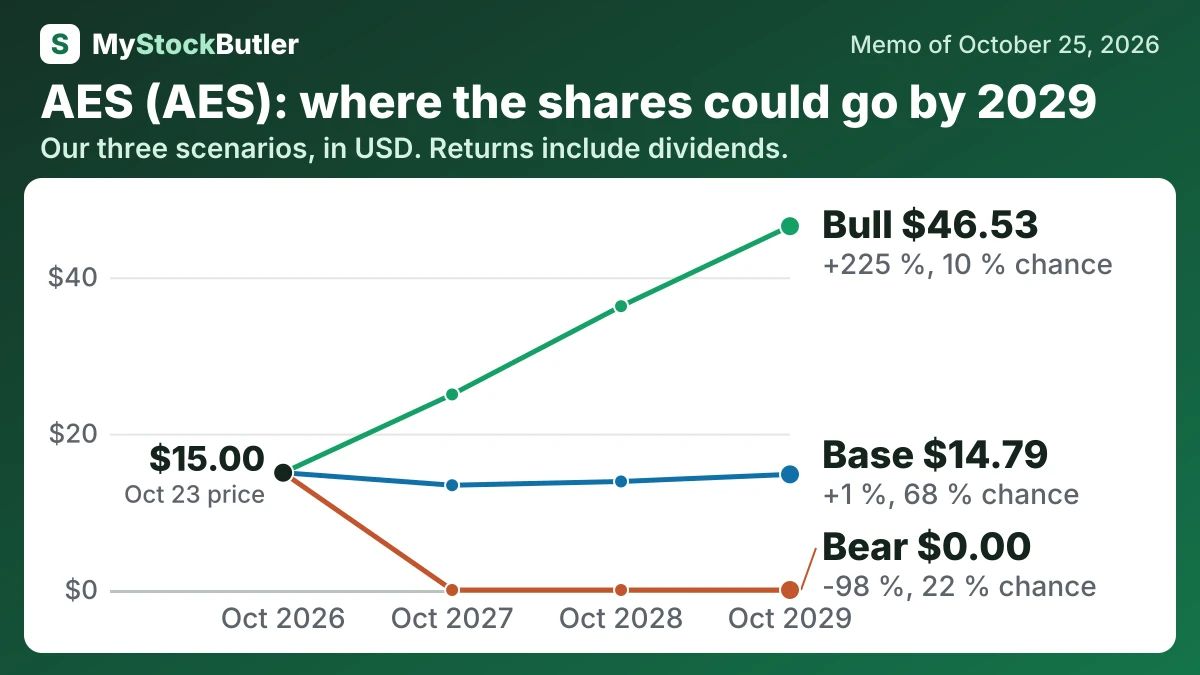
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 22 % | 0.00 (-98 %) | 0.00 (-98 %) | 0.00 (-98 %) |
| Base | 68 % | 13.40 (-8 %) | 13.88 (-5 %) | 14.79 (+1 %) |
| Bull | 10 % | 25.01 (+71 %) | 36.30 (+151 %) | 46.53 (+225 %) |
| Weighted | 100 % | 11.61 (-20 %) | 13.07 (-10 %) | 14.71 (+2 %) |
What this means. The weighted row is the probability-based average of all three cases, not the price expected in the most likely base case.
What has to go right for AES, and what could go wrong?
The base case uses $3,400 million in October 2027 and $3,550 million in October 2028. It reaches $3,700 million in October 2029. This is moderate growth because favorable spot and derivative effects may fade, while the 12.0 GW backlog, including 5.7 GW under construction, should add earnings only as projects operate. The bear case falls to $3,100 million, then $3,000 million, before recovering to $3,100 million as delays and normalization dominate. The bull case reaches $3,600 million, then $3,900 million, and finally $4,250 million if projects and utility investment convert quickly. The older management growth target supports the direction, but it is not a current period-by-period forecast.
The bear case requires the acquisition to fail or drift beyond its outside date, removing the $15 price anchor. AES then faces negative free cash flow, limited parent cash and heavy investment, while dilution and a lower multiple overwhelm electricity-demand growth. The price is $0.00 in October 2027 and remains $0.00 in October 2029. Its probability is 22%: the funding risk is real, but the outcome is unusually severe given the backlog and regulated earnings.
| October 2027 | October 2028 | October 2029 | |
|---|---|---|---|
| EBITDA | 3,400 (3,100 / 3,600) | 3,550 (3,000 / 3,900) | 3,700 (3,100 / 4,250) |
| Shares (millions) | 713 (742 / 713) | 713 (774 / 713) | 713 (802 / 713) |
| Dividends per share | 0.35 (0.35 / 0.70) | 0.00 (0.00 / 0.70) | 0.00 (0.00 / 0.75) |
| Enterprise value to ebitda | 12.30 (9.50 / 13.50) | 12.30 (8.50 / 14.50) | 12.30 (9.00 / 15.00) |
| Net debt | 32,264 (33,564 / 30,764) | 33,764 (35,564 / 30,664) | 34,964 (37,564 / 30,564) |
How much cash does AES really make?
Revenue stayed roughly flat, while real free cash flow—cash from operations minus capital spending and stock pay—was negative 13.5% of revenue in 2025. Net debt rose from $27,415 million in 2024 to $28,341 million in 2025. The per-share gap was $1.71 in the company’s free-cash-flow count versus negative $2.32 in its real free cash flow, with no buybacks.
| 2025 | |
|---|---|
| Cash from operations | 4,306 |
| − Capital spending | 5,929 |
| = Free cash flow | -1,623 |
| − Stock pay | 34 |
| = Real free cash flow | -1,657 |
What this means. The company's free cash flow is positive because it counts only the parent company's cash and leaves out capital spending by its subsidiaries, while our count includes that spending.