West earnings
MyStockButler's October 2026 analysis: West reports on October 29, 2026. Watch whether the recovery reaches margins and operating cash.
What has West guided for the year?
Management’s July 23, 2026 guidance calls for full-year organic sales growth of 10.0%–11.0%. It calls for adjusted diluted EPS of $8.85–$9.05 and capital spending of $250–$275 million. Its promise record is mixed: organic growth came in below initial guidance in three of the five years checked.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Full-year 2026 net sales | Year to Dec 2026 | 3,345.0 | 3,380.0 | Jul 23, 2026 |
| Full-year 2026 organic net sales growth | Year to Dec 2026 | 10.0% | 11.0% | Jul 23, 2026 |
| Full-year 2026 adjusted-diluted EPS | Year to Dec 2026 | 8.85 | 9.05 | Jul 23, 2026 |
| Capital spending | Year to Dec 2026 | 250 | 275 | Jul 23, 2026 |
| Third-quarter 2026 net sales | Quarter to Sep 2026 | 820 | 835 | Jul 23, 2026 |
| Third-quarter 2026 adjusted-diluted EPS | Quarter to Sep 2026 | 2.14 | 2.24 | Jul 23, 2026 |
What this means. Organic net sales growth leaves out sales from the SmartDose 3.5mL business after it was sold, while reported growth still includes the sale's effect.
Did West keep its past promises?
West’s promise record earns 3/5. Organic growth missed initial guidance in three of the five years checked. Currency, falling COVID demand, a facility sale, and customer destocking all affected earlier results, but the key question now is whether management understands customer ordering well enough to avoid another late reset.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Net sales | 5 years | 2 | 1 | 2 |
| Organic net sales growth (called organic sales growth in 2021 and initial 2022 guidance) | 5 years | 2 | 0 | 3 |
| Capital spending | 5 years | 4 | 0 | 1 |
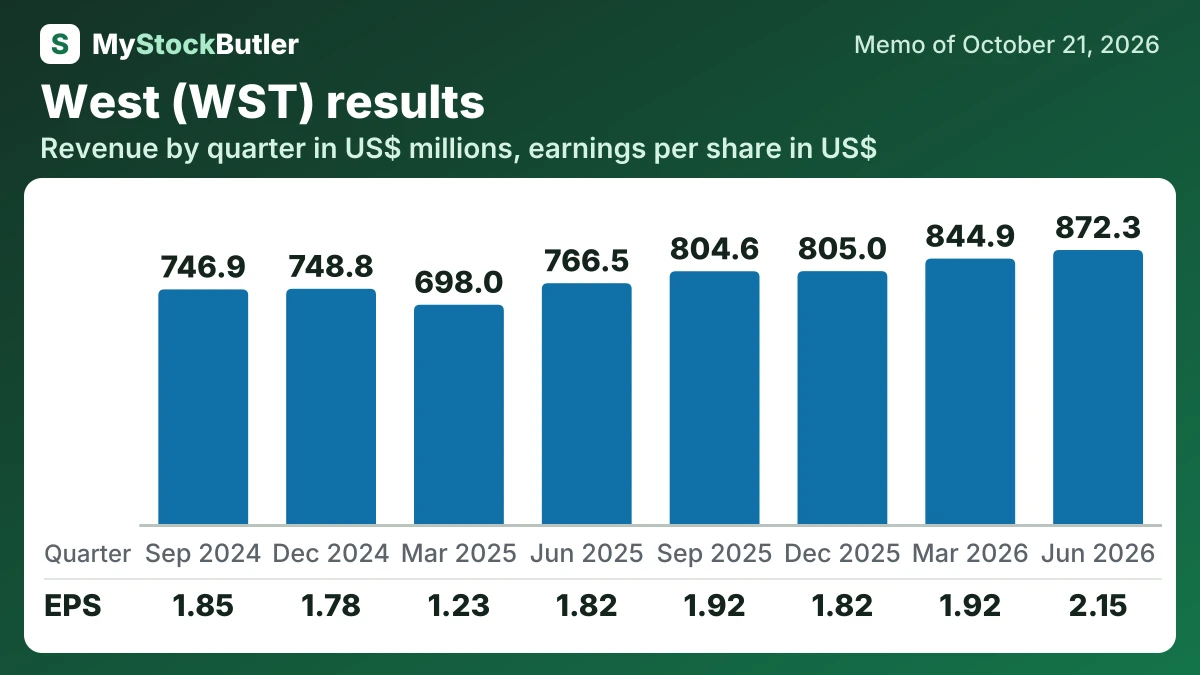
What is West's eight-quarter results trend?
The eight-quarter sequence shows a recovery from the low point in March 2025. Gross margin also recovered from that quarter’s 33.2%, which supports the view that factory utilization and product mix are improving over several quarters rather than in one isolated period.
Cash conversion was the counterpoint. Q2 operating cash and free cash flow both fell despite lower capital spending, largely because receivables and sales timing absorbed cash. Q3 guidance also separated reported growth from organic growth because prior-year SmartDose sales would be excluded from the comparison. The table places the latest quarter beside the preceding seven quarters.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 872.3 | 844.9 | 805.0 | 804.6 | 766.5 | 698.0 | 748.8 | 746.9 |
| Gross margin | 37.7% | 35.1% | 37.8% | 36.6% | 35.7% | 33.2% | 36.5% | 35.4% |
| Operating income | 179.1 | 177.1 | 156.6 | 167.6 | 153.7 | 107.0 | 159.6 | 161.3 |
| Net income | 154.0 | 138.8 | 132.1 | 140.0 | 131.8 | 89.8 | 130.1 | 136.0 |
| EPS, diluted | 2.15 | 1.92 | 1.82 | 1.92 | 1.82 | 1.23 | 1.78 | 1.85 |
| = Free cash flow | 80.8 | 47.2 | 175.0 | 133.9 | 101.9 | 58.1 | 85.2 | 98.8 |
What this means. The cash from operations and free cash flow numbers are for each quarter, even though the descriptions say yearly, because later quarters are calculated from year-to-date totals.
What should you watch in West's next results?
West has scheduled third-quarter results for October 29, 2026, before the market opens, followed by an 8 a.m. Eastern call. The report should show whether the recovery continued, whether Dublin production increased, and whether cash collection improved after the cyber disruption. Sales alone will not settle those questions; margins and operating cash must follow.