TSMC stock forecast 2027–2029
MyStockButler's October 2026 analysis: TSMC's weighted forecast is US$468.34 for October 2027. It hinges on turning leading-edge capacity into well-loaded, profitable production.
Where could TSMC's shares be by 2029?
The first weighted forecast is US$468.34. By October 2027, it implies a 15% return including dividends. The last is US$742.49. By October 2029, it implies an 84% return including dividends. The probabilities are 25% for the bear case, 55% for base and 20% for bull.
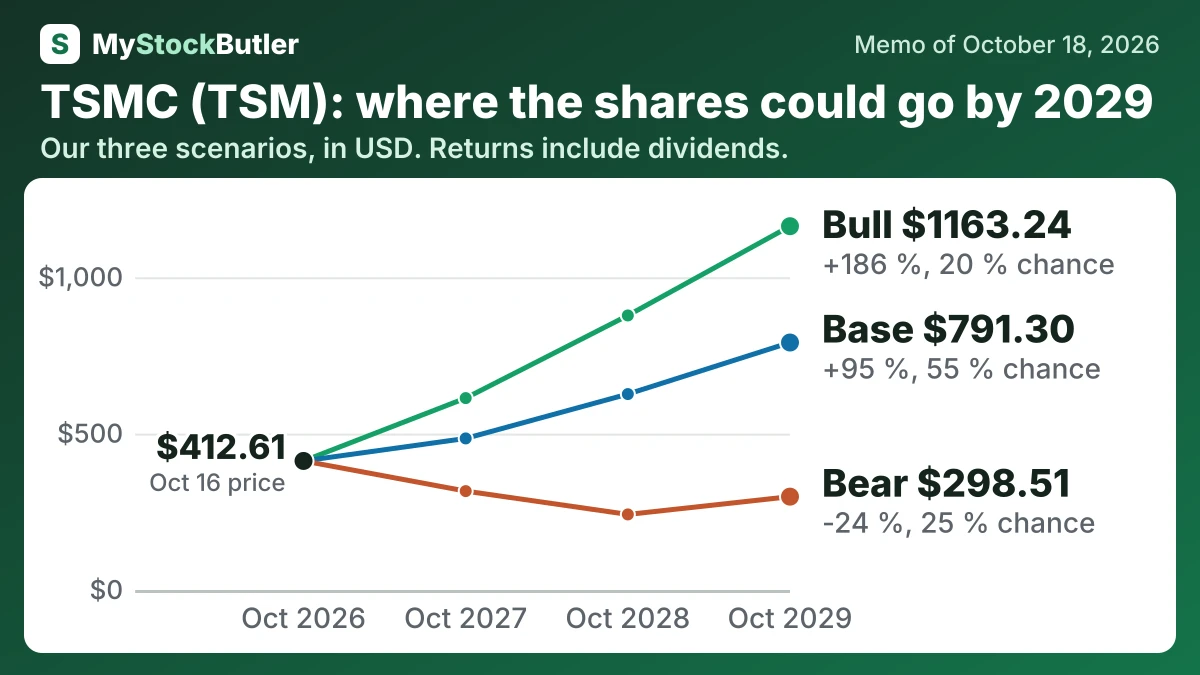
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 25 % | 316.21 (-22 %) | 241.66 (-39 %) | 298.51 (-24 %) |
| Base | 55 % | 484.67 (+19 %) | 626.46 (+54 %) | 791.30 (+95 %) |
| Bull | 20 % | 613.62 (+50 %) | 877.80 (+115 %) | 1163.24 (+186 %) |
| Weighted | 100 % | 468.34 (+15 %) | 580.53 (+43 %) | 742.49 (+84 %) |
What this means. The weighted row is the probability-based average of the bear, base, and bull cases, not a separate forecast.
What has to go right, and what could go wrong for TSMC?
EBITDA is the main source of upside and downside. Base EBITDA is TWD 4,500,000m in October 2027 and 5,475,000m in October 2028. It reaches TWD 6,512,000m in October 2029. The bear row falls to TWD 3,575,000m in 2028, while the bull row reaches TWD 6,080,000m. The bear assumes weaker utilization and ramp costs; the bull assumes strong AI demand, better N2 yields and fuller CoWoS capacity.
The December 2026 quarter tests guidance against two-nanometer ramp costs and overseas-fab dilution. TSMC plans to double N2 family annual capacity by 2027; customer adoption, yield improvement and loading will test whether that investment is productive. CoWoS expansion must raise saleable throughput, while AI investment must translate into sustained orders through 2027–2028.
How much cash does TSMC really make?
Stock-based pay is deducted to produce “real free cash flow,” because paying employees in shares does not use cash immediately but does dilute shareholders. The adjustment is small here compared with the company’s overall cash generation.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 2,274,975.6 | 1,826,177.1 | 1,241,967.3 | 1,610,599.2 | 1,112,160.7 |
| − Capital spending | 1,272,410.5 | 956,006.5 | 949,816.8 | 1,082,672.1 | 839,195.7 |
| = Free cash flow | 1,002,565.1 | 870,170.6 | 292,150.5 | 527,927.1 | 272,965.0 |
| − Stock pay | 1,246.1 | 1,242.7 | 483.0 | 302.4 | 7.8 |
| = Real free cash flow | 1,001,319.0 | 868,927.9 | 291,667.5 | 527,624.7 | 272,957.2 |
| Real free cash flow, % of revenue | 26.3% | 30.0% | 13.5% | 23.3% | 17.2% |
What this means. The company's own free cash flow is slightly different because it adds back or removes a few cash items that we treat differently, while our real free cash flow also subtracts shares given to employees as pay.
What does an investor pay for TSMC today?
At the October 18, 2026 snapshot, a forward P/E of 24.2 means investors pay $24.20 for each dollar of profit expected over the next year. That can make sense if profit soon grows to $2, but not if it remains at $1. The ratio therefore prices profits beyond the forecast year.
| Today (Oct 18, 2026) | |
|---|---|
| Share price | 412.61 |
| Market value (calculated) | 2,139,960.5 |
| Enterprise value (calculated) | 2,046,315.6 |
| P/E, last 12 months (calculated) | 26.8x |
| P/E, next 12 months (calculated) | 24.2x |
| Free cash flow yield (calculated) | 1.5% |
What this means. Enterprise value is lower than market value because the company has more cash and short-term investments than debt.