PTC stock forecast 2027–2029
MyStockButler's October 2026 analysis: PTC’s weighted forecast is $185.24 in October 2027 and $227.63 in October 2029. It hinges on Schneider Electric’s $205 cash offer and standalone cash generation.
Where could PTC’s shares be by 2029?
The weighted forecast is weak in October 2027, but improves as cash generation rises and the acquisition outcome becomes clearer. The shares are worth $185.24 in October 2027, including dividends, or a 5% loss from today’s $194.00. The weighted value rises to $205.35, a 6% gain, in October 2028 and $227.63, a 17% gain, in October 2029.
The October 2029 range is wide: $117.07 in the bear case to $306.80 in the bull case. The probabilities are 20% bear, 65% base and 15% bull, reflecting the signed $205 cash offer but also the risks around approval, timing and standalone execution.
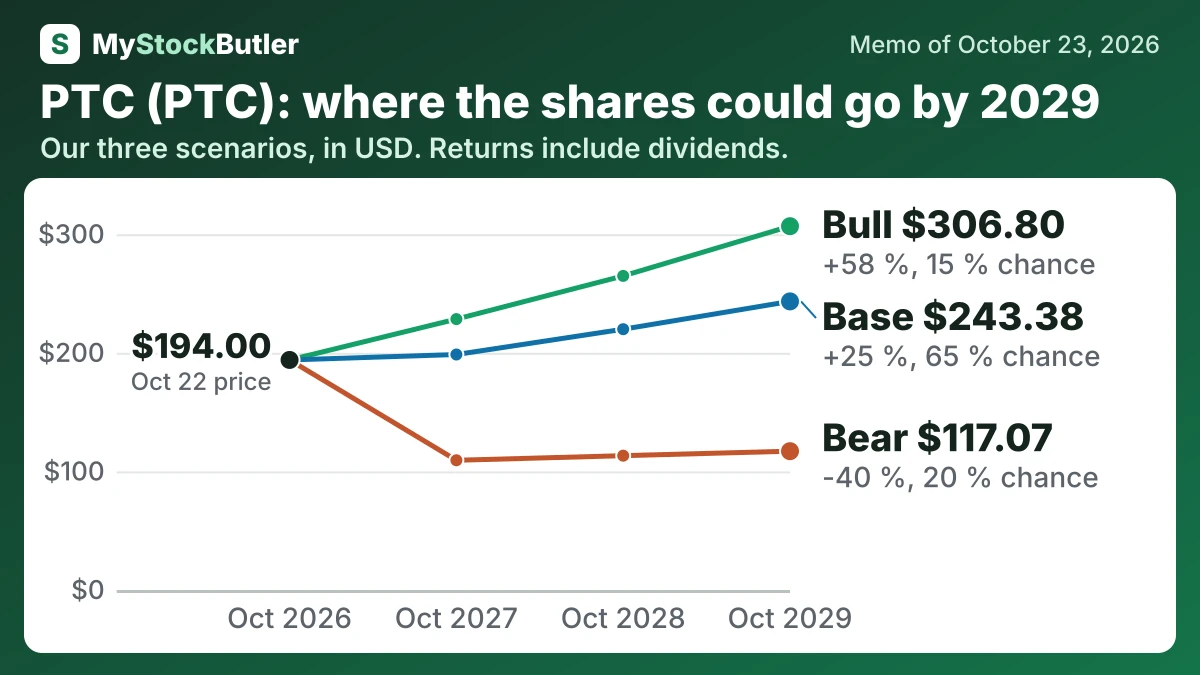
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 20 % | 109.40 (-44 %) | 113.28 (-42 %) | 117.07 (-40 %) |
| Base | 65 % | 198.60 (+2 %) | 219.95 (+13 %) | 243.38 (+25 %) |
| Bull | 15 % | 228.46 (+18 %) | 264.88 (+37 %) | 306.80 (+58 %) |
| Weighted | 100 % | 185.24 (-5 %) | 205.35 (+6 %) | 227.63 (+17 %) |
What has to go right or wrong for PTC?
The bear case gives $480 million, $500 million and $520 million, allowing for delayed starts, seat reductions and weaker activation. The bull case gives $640 million, $700 million and $770 million, assuming deferred contracts activate and paid AI adoption adds to recurring growth. The five-year record of rising real cash flow supports recovery, but FY2026 guidance implies a decline after stock pay.
How much cash does PTC really make?
Stock compensation requires another adjustment. PTC recorded substantial FY2025 stock pay without making an equivalent cash payment immediately. That boosts operating cash flow, but employees received an ownership claim that can dilute existing shareholders. Deducting stock pay produces a useful analytical measure of cash generation, though it is not an official cash-flow statement.
| Sep 2025 | Sep 2024 | Sep 2023 | Sep 2022 | Sep 2021 | |
|---|---|---|---|---|---|
| = Free cash flow | 856,688 | 735,606 | 587,047 | 415,830 | 344,096 |
| − Stock pay | 216,205 | 223,461 | 206,459 | 174,863 | 177,289 |
| = Real free cash flow | 640,483 | 512,145 | 380,588 | 240,967 | 166,807 |
| Free cash flow, % of revenue | 31.3% | 32.0% | 28.0% | 21.5% | 19.0% |
| Real free cash flow, % of revenue | 23.4% | 22.3% | 18.1% | 12.5% | 9.2% |
What this means. The company's own free cash flow matches ours, but real free cash flow is lower because we also count shares given to employees as a real cost to existing owners.
What does PTC’s stock price pay for in earnings and cash?
PTC’s P/E, or price-to-earnings ratio, says how much investors pay for each dollar of earnings. The trailing P/E is 18.9x, while the forward P/E is 21.8x. The difference matters because fiscal 2026 earnings included a $463 million gain from selling Kepware and ThingWorx. That temporary gain enlarged the earnings denominator, making the trailing ratio look cheaper without making ordinary software customers more profitable.
| Today (Oct 22, 2026) | |
|---|---|
| Share price | 194.00 |
| P/E, last 12 months (calculated) | 18.9x |
| P/E, next 12 months (calculated) | 21.8x |
| Free cash flow yield (calculated) | 4.1% |
| Real free cash flow yield (calculated) | 3.0% |
What this means. The next-12-month price-to-earnings ratio uses analysts’ forecast profit, so it is an estimate rather than a result the company has already earned.