Kraken earnings date and guidance
MyStockButler's October 2026 analysis: Kraken’s next results are expected on November 30, 2026. Watch whether accepted deliveries become profitable cash generation.
What has Kraken guided for 2026?
At C$4.50 per share, Kraken can reach C$4.75 by October 2029, a 6% gain including dividends, if repeat orders, Covelya integration and cash conversion improve. Management guides 2026 revenue to C$290–320 million and adjusted EBITDA to C$65–75 million, with a 22.0–23.0% margin. Capital expenditures and intangible assets are guided at C$27–33 million. Products are expected to account for 75.0% of revenue. For 2027, management expects Covelya to add low-to-mid double-digit EPS accretion, including cost savings.
| the period guided | low | high | the date it was given | |
|---|---|---|---|---|
| Consolidated Revenues | Year to Dec 2026 | 290,000 | 320,000 | Jul 2, 2026 |
| Adjusted EBITDA | Year to Dec 2026 | 65,000 | 75,000 | Jul 2, 2026 |
| Adjusted EBITDA Margin | Year to Dec 2026 | 22.0% | 23.0% | Jul 2, 2026 |
| Capital Expenditures / Intangible Assets | Year to Dec 2026 | 27,000 | 33,000 | Jul 2, 2026 |
| Product revenue (% of 2026 revenues) | Year to Dec 2026 | 75.0% | Aug 27, 2026 | |
| EPS accretion | Year to Dec 2027 | Jul 2, 2026 |
Did Kraken keep its past promises?
Adjusted EBITDA is management’s estimate of operating earnings before interest, taxes, depreciation, amortization, stock compensation and selected unusual costs. It helps compare operations, but it is not cash in the bank. Management forecast revenue of C$120–135 million and adjusted EBITDA of C$26–34 million. Actual 2025 revenue was C$102.2 million, and adjusted EBITDA was C$25.0 million.
What is Kraken’s revenue and profit trend?
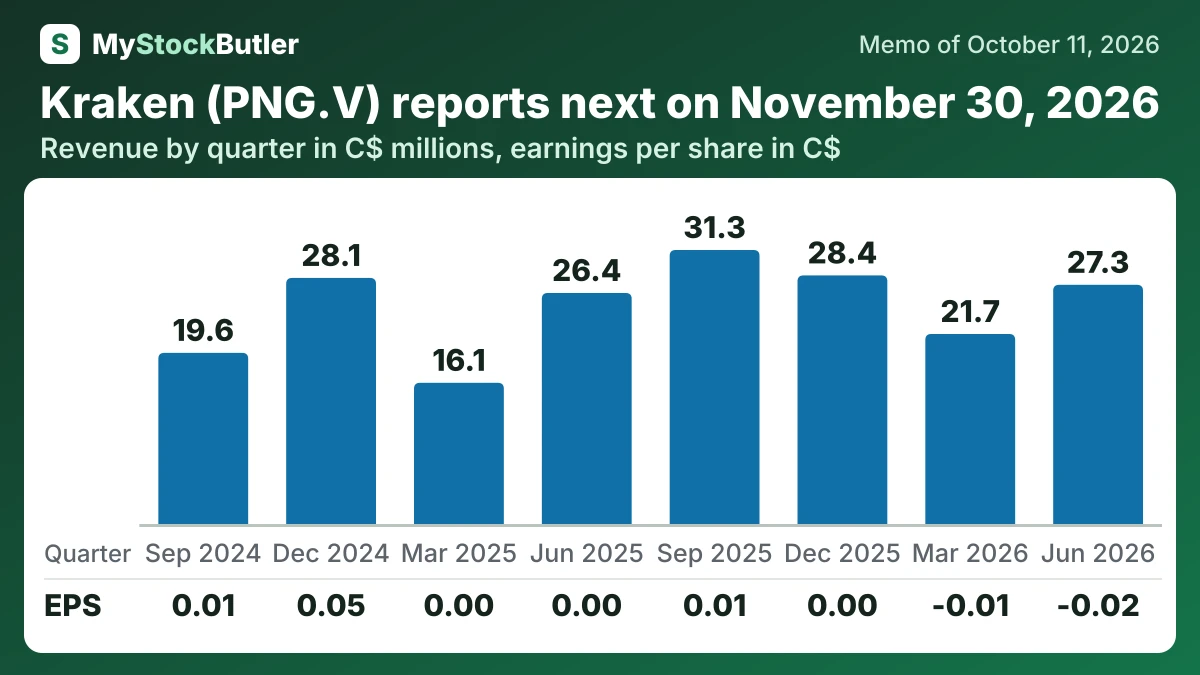
Reported revenue grew 3.5% year over year, despite a C$1.500 million reversal of previously recognized integration-project revenue after the contract scope narrowed. Without that reversal, growth would have been 9.2%. Revenue can therefore change after work has been recognized when the expected contract value changes.
Profitability remained poor. The quarter included a C$6.911 million supplier-arbitration provision, C$1.963 million of restructuring costs and C$690,000 of acquisition amortization. Removing restructuring and amortization produces modest operating profit, while the company’s complete reconciliation produced C$769,000 of adjusted earnings after its tax adjustment. The arbitration provision was non-cash when recorded, but it represents an expected obligation.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 27,320 | 21,705 | 28,394 | 31,298 | 26,390 | 16,128 | 28,109 | 19,550 |
| Operating income | -1,999 | -3,585 | 3,038 | 4,290 | 751 | 476 | 4,920 | 2,304 |
| Net income | -7,518 | -3,326 | 54 | 3,290 | -699 | 215 | 13,674 | 1,631 |
| EPS, diluted | -0.02 | -0.01 | 0.00 | 0.01 | 0.00 | 0.00 | 0.05 | 0.01 |
What should I watch in Kraken’s next results?
Q3 reporting, scheduled for late November 2026, will include Covelya for the first time. Q4 will test the promised second-half weighting and the additional KATFISH contract. Beyond that, management targets C$10 million of acquisition cost efficiencies within twenty-four months of closing, or around July 2028. Revenue delivery and cost savings are separate tests.