HII stock forecast 2027–2029
MyStockButler's October 2026 analysis: The weighted scenario reaches $352.52 by October 2029, a 32% return including dividends. It hinges on turning shipyard throughput into delivered ships, stable estimates and collected cash.
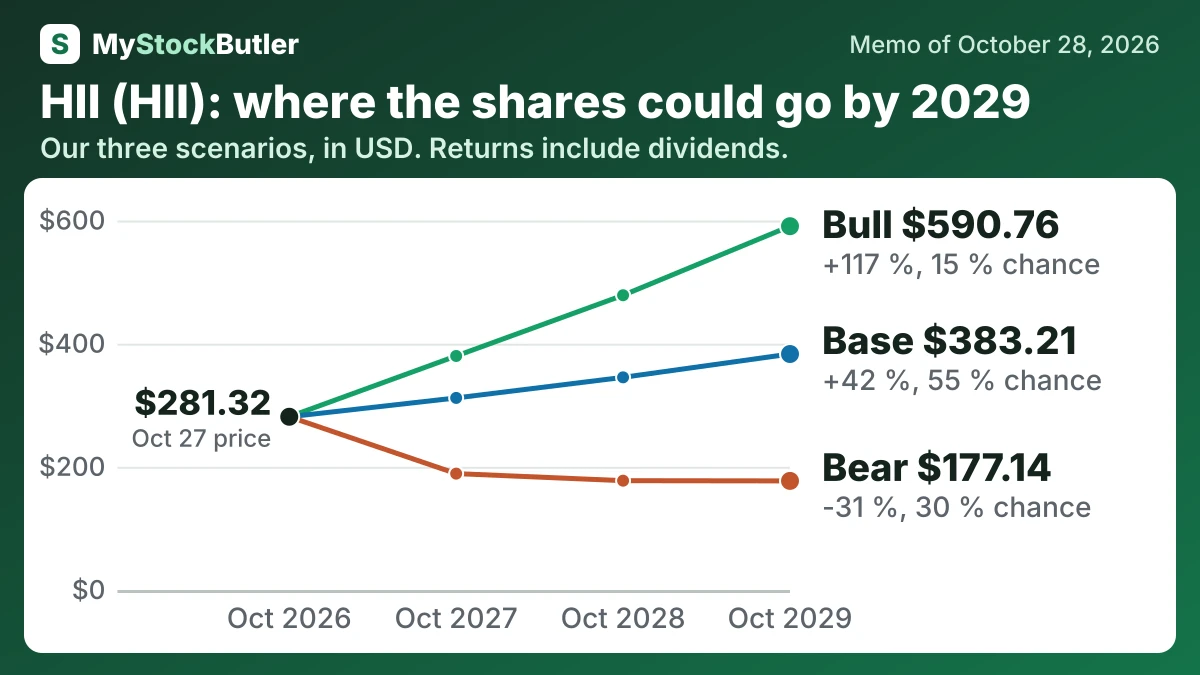
Where could HII's shares be by October 2029?
At the first forecast point, weighted price is $285.24 in October 2027, a 3% return including dividends. At the last, $352.52 in October 2029 represents a 32% return including dividends. The bear case has 30% probability. The base case has 55%. The bull case has 15%.
The probability-weighted price is $285.24 in October 2027, a 3% return including dividends. It reaches $314.98 in October 2028, a 16% return including dividends. By October 2029, it reaches $352.52, a 32% return including dividends.
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 30 % | 188.99 (-31 %) | 177.51 (-33 %) | 177.14 (-31 %) |
| Base | 55 % | 311.90 (+13 %) | 345.33 (+27 %) | 383.21 (+42 %) |
| Bull | 15 % | 380.00 (+37 %) | 478.63 (+74 %) | 590.76 (+117 %) |
| Weighted | 100 % | 285.24 (+3 %) | 314.98 (+16 %) | 352.52 (+32 %) |
What this means. The weighted row is the probability-based average of the bear, base, and bull outcomes, not a separate forecast.
What has to go right for HII, and what could go wrong?
The base revenue path follows gradual growth toward management's 6% outlook. Its net margin rises from 5.5% to 5.7%, below what the analyst EPS estimate would imply, because execution and cash conversion remain unproven. The bear case assumes about 2% annual growth and margins near 4.2%, reflecting delays and rework. The bull case reaches a 6.0% margin as throughput becomes dependable delivery. HII's rising throughput supports the upside, but Bougainville's delayed delivery and uneven guidance record argue for restraint.
The bear story is that HII cannot convert added capacity into timely, profitable deliveries. Labor shortages, supplier handoffs, rework and adverse contract revisions keep margins weak, while delayed billing and investment suppress cash. Bougainville's delivery moved to July 2027, and Virginia production remains below purchases. The bear price is $188.99 in October 2027 and $177.14 in October 2029. Its probability is 30% because negative first-half free cash flow and the welding investigation leave a credible path to lower earnings and a lower multiple.
How much cash does HII really make?
Operating cash flow reached $1,196 million in 2025, compared with $393 million in 2024. After capital spending, free cash flow was $794 million; subtracting $54 million of stock-based compensation gives an analytical “real” free cash flow of $740 million. That deduction treats shares issued as compensation as an economic cost to shareholders, not as another cash payment.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 1,196 | 393 | 970 | 766 | 760 |
| − Capital spending | 402 | 367 | 292 | 284 | 331 |
| = Free cash flow | 794 | 26 | 678 | 482 | 429 |
| − Stock pay | 54 | 23 | 34 | 36 | 33 |
| = Real free cash flow | 740 | 3 | 644 | 446 | 396 |
| Real free cash flow, % of revenue | 5.9% | 0.0% | 5.6% | 4.2% | 4.2% |
What does an investor pay for HII today?
| Today (Oct 27, 2026) | |
|---|---|
| Share price | 281.32 |
| Market value (calculated) | 11,085.30 |
| Enterprise value (calculated) | 13,775.30 |
| P/E, last 12 months (calculated) | 16.8x |
| P/E, next 12 months (calculated) | 13.3x |
| Real free cash flow yield (calculated) | 6.7% |
What this means. Enterprise value is higher than market value because it includes debt and subtracts cash, showing what it would cost to buy the whole business.