Merck earnings: November 12, 2026 guidance and watch
MyStockButler's November 2026 analysis: Merck's next results are due on November 12, 2026. Merck should watch U.S. Mavenclad sales after August and Life Science orders.
What has Merck guided for 2026?
Management guides to 2026 sales of €21.0–€21.8 billion. EBITDA pre guidance is €5.9–€6.3 billion. Free cash flow guidance is €1.8–€2.3 billion. Life Science and Electronics should grow, while Healthcare declines. Management’s past promise score is 3/5.
| Period | Low | High | Given on | |
|---|---|---|---|---|
| Group, Net sales | Year to Dec 2026 | 21,000 | 21,800 | Aug 6, 2026 |
| Group, EBITDA pre | Year to Dec 2026 | 5,900 | 6,300 | Aug 6, 2026 |
| Group, Free cash flow | Year to Dec 2026 | 1,800 | 2,300 | Aug 6, 2026 |
| Life Science, Net sales, Organic | Year to Dec 2026 | 5.0% | 7.0% | Aug 6, 2026 |
| Healthcare, Net sales, Organic | Year to Dec 2026 | -4.0% | -2.0% | Aug 6, 2026 |
| Electronics, Net sales, Organic | Year to Dec 2026 | 6.0% | 9.0% | Aug 6, 2026 |
What this means. The forecast for spending on property, plant, and equipment is not the same as cash spending because it excludes leases.
Did Merck keep its past promises?
Management’s forecasting record merits 3/5. Merck exceeded its initial 2021 expectations, but later cut 2023 guidance and its original 2025 sales and operating-cash-flow forecasts. Currency hurt the 2025 sales comparison, while higher tax payments contributed to the 2022 cash-flow miss.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Net sales | 4 years | 0 | 2 | 2 |
| EBITDA pre | 5 years | 1 | 3 | 1 |
| Operating cash flow | 4 years | 1 | 0 | 3 |
What this means. The report says management kept three of five promises, but the rows show thirteen checks, so it is unclear what the five promises are.
What has Merck's revenue and profit trend been?
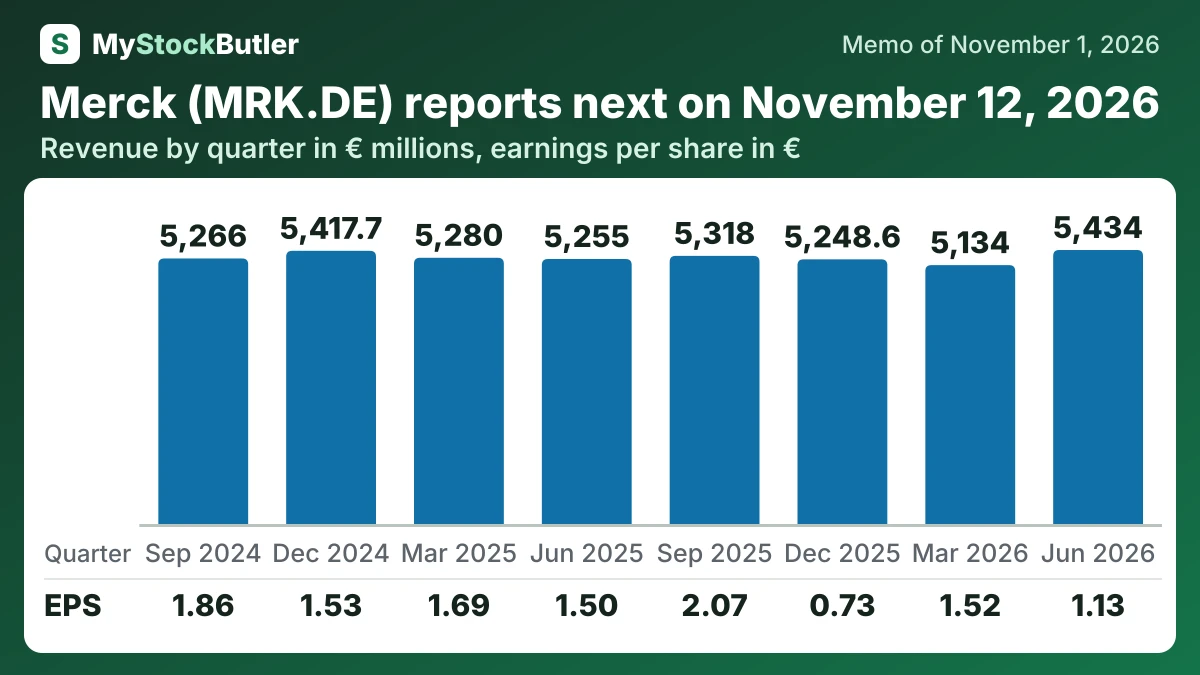
Revenue rose organically by 4.1% in the quarter, helped by bioprocessing and semiconductor products. Yet operating income and net income fell. Stronger sales and weaker profit are therefore not contradictory: the quarter also contained €189 million of restructuring charges.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 5,434 | 5,134 | 5,248.6 | 5,318 | 5,255 | 5,280 | 5,417.7 | 5,266 |
| Gross margin | 58.3% | 59.7% | 56.4% | 60.4% | 57.6% | 59.6% | 57.2% | 59.7% |
| Operating margin | 13.9% | 18.3% | 9.2% | 23.0% | 17.0% | 19.1% | 15.2% | 20.8% |
| EPS, diluted | 1.13 | 1.52 | 0.73 | 2.07 | 1.50 | 1.69 | 1.53 | 1.86 |
| Free cash flow | 314 | 332 | 233 | 28 |
What this means. The blank free cash flow cells mean the report did not provide enough information to calculate them without guessing, not that the company had no cash flow.
What should I watch in Merck's next release?
On November 12, 2026, Merck is scheduled to report third-quarter results. Investors should examine U.S. Mavenclad sales after August and Life Science orders, because management expects unusually strong early-2026 buying to normalize. Electronics also needs inspection: first-half adjusted earnings included €43 million from selling OLED patents and income from a supplier reimbursement, neither of which is the same as recurring chip-material demand.
Bio-Techne shareholders approved the transaction on September 23, 2026, and the antitrust waiting period had expired. Closing was expected in late 2026 or early 2027. The key evidence will be the cash paid, debt added and interest rate. By the third year, the promised savings and earnings-per-share improvement will matter more.