Glencore earnings
MyStockButler's October 2026 analysis: Glencore returned to statutory profit, but adjusted earnings fell. The next release will test copper delivery and EVR output after first-half weakness.
What has Glencore guided for the year?
For 2026, Glencore guides to copper production of 810–870 thousand tonnes and zinc production of 700–740 thousand tonnes. Those ranges survived the sale of Kidd on 1 June, although Kidd had been expected to supply 11 thousand tonnes of copper and 20 thousand tonnes of zinc during June–December. The remaining mines must therefore do more: like a restaurant chain selling one branch but promising the same number of meals, the other branches must serve more.
Marketing, Glencore’s commodity-trading operation, is the larger reset. Management expects 2026 adjusted EBIT above $5 billion, helped by disrupted energy markets. Its 2027 reference range is $2.8–4.2 billion because readily marketable inventories, or RMI, require funding. For example, Glencore may borrow to hold copper already promised to a customer, then repay the borrowing when that customer pays.
| the period guided | low | high | the date it was given | |
|---|---|---|---|---|
| Copper, production (kt) | 2026 | 810 | 870 | Jul 29, 2026 |
| Zinc, production (kt) | 2026 | 700 | 740 | Jul 29, 2026 |
| Marketing Adj. EBIT (US$ billions), in excess of | 2026 | 5 | Oct 2, 2026 | |
| Marketing Adj. EBIT, reference-case range (US$ billions) | 2027 | 2.8 | 4.2 | Oct 2, 2026 |
Has Glencore kept its past promises?
There is evidence of delivery behind the strategic story. Glencore promised roughly $1 billion in recurring annual cost savings against a 2024 baseline and reported delivering more than half in 2025. Its US compliance monitorships also ended about a year early in 2025. Those milestones matter, although ending external monitoring does not prove misconduct cannot recur.
What is Glencore's revenue and profit trend?
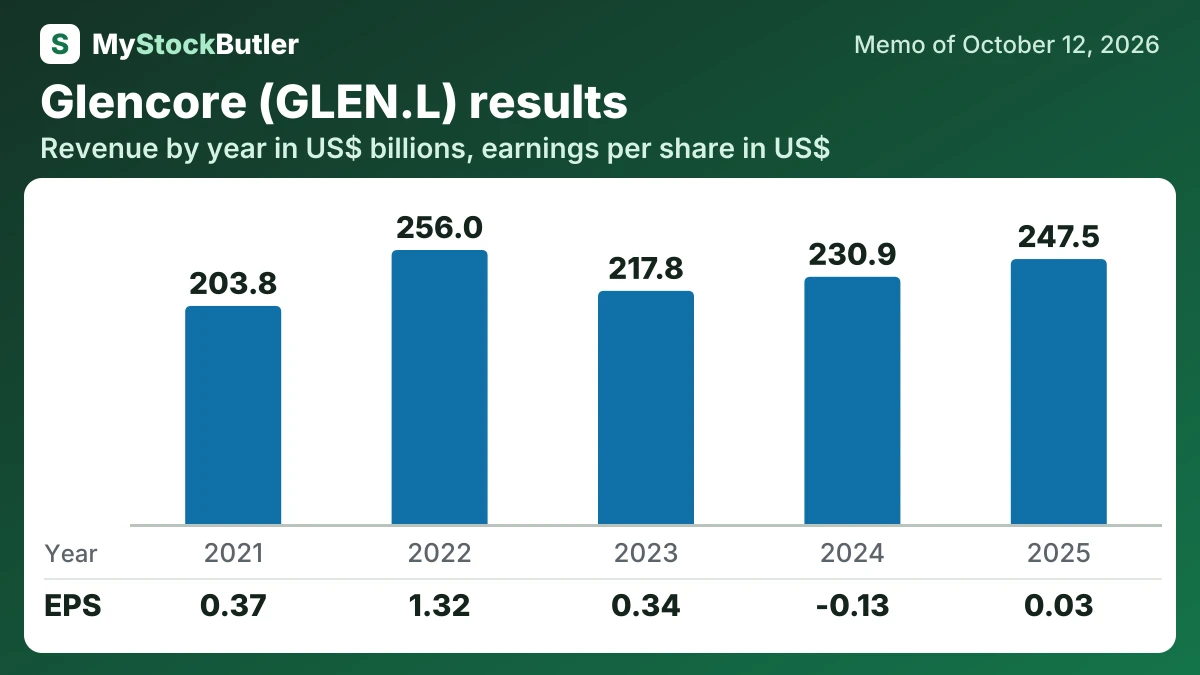
Reported profit improved because significant items were less damaging than before. Adjusted earnings remove selected gains and losses to show what management considers ordinary performance. In 2025, adjusted EBITDA and adjusted net income both fell, even as statutory net income recovered.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Revenue | 247,535 | 230,944 | 217,829 | 255,984 | 203,751 |
| Revenue growth (calculated) | 7.2% | 6.0% | -14.9% | 25.6% | 43.1% |
| Net income | 363 | -1,634 | 4,280 | 17,320 | 4,974 |
| EPS, diluted | 0.03 | -0.13 | 0.34 | 1.32 | 0.37 |
What should you watch in Glencore's next release?
The expected 14 October ASX debut will show whether Australian access attracts trading activity. The 29 October third-quarter production report is the sharper operating test, especially for copper and EVR, where first-half throughput and yields had reduced output. By year-end, management also expects full delivery of its recurring cost-saving programme.