Dassault Systèmes stock forecast 2027–2029
MyStockButler's November 2026 analysis: The weighted scenario is €28.76 in November 2027 and €32.63 in November 2029. It hinges on ARR converting into recurring cash.
Where could Dassault Systèmes's shares be by 2029?
Our weighted price is €28.76 in November 2027, a 15% return including dividends. It reaches €32.63 in November 2029, a 33% return including dividends. The bear case has 30% probability. The base has 55%. The bull has 15%.
The first checkpoint is February 3, 2027: MEDIDATA growth, ArisGlobal contribution and ARR conversion. During 2027–2028, cross-selling decides whether growth broadens. By 2028–2029, cash generation and buybacks decide the valuation.
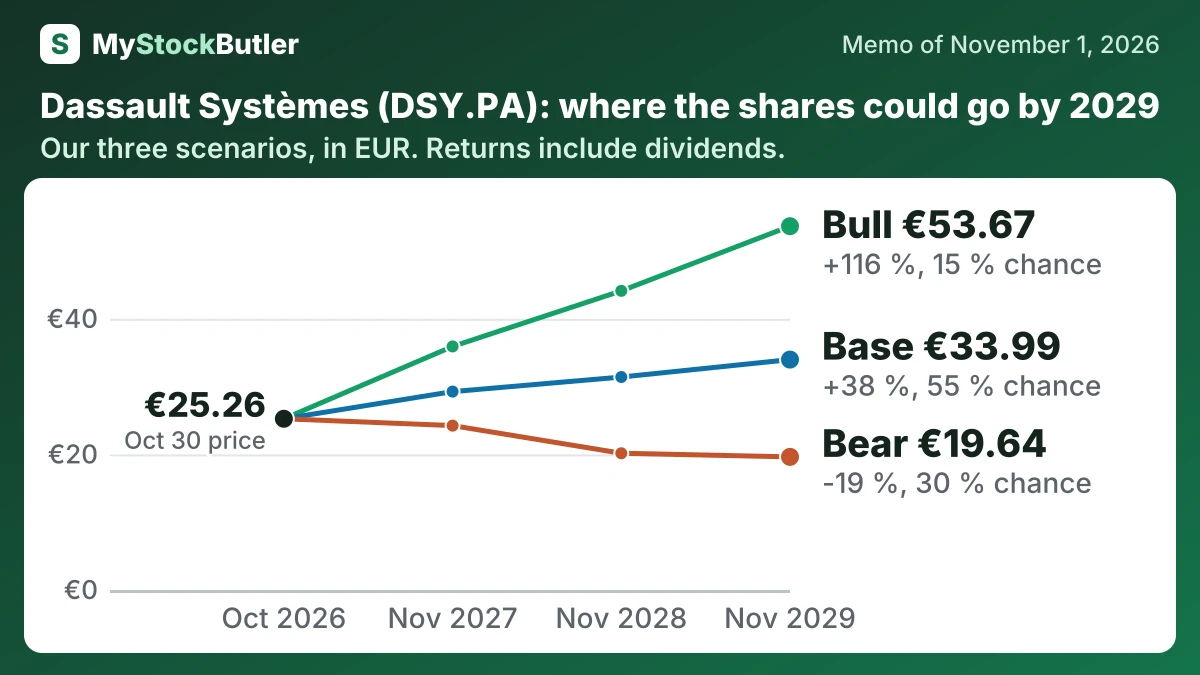
| Case | Probability | November 2027 | November 2028 | November 2029 |
|---|---|---|---|---|
| Bear | 30 % | 24.25 (-3 %) | 20.17 (-18 %) | 19.64 (-19 %) |
| Base | 55 % | 29.27 (+17 %) | 31.42 (+27 %) | 33.99 (+38 %) |
| Bull | 15 % | 35.93 (+43 %) | 44.13 (+77 %) | 53.67 (+116 %) |
| Weighted | 100 % | 28.76 (+15 %) | 29.95 (+21 %) | 32.63 (+33 %) |
What has to go right or wrong for Dassault Systèmes?
The base case raises free cash flow after stock pay from €1,480 million to €1,660 million. It assumes operating cash flow grows from €1,800 million to €2,020 million while investment and stock pay also rise. That is supported by six-percent ARR growth in each of the first three 2026 quarters, but tempered by only three-percent subscription-and-support growth in Q3. The bear case falls to €1,280 million in 2028 as deployments and clinical-trial activity weaken; the bull case reaches €1,920 million as 3DEXPERIENCE adoption, MEDIDATA and ArisGlobal cross-selling accelerate.
The bear case assumes customers delay deployments, ARR converts slowly, MEDIDATA remains exposed to weak trial activity and ArisGlobal adds limited cross-selling. Subscription and support already grew more slowly than ARR, while the top fifteen deals supplied about 80% of the net increase in subscription ARR. The bear prices are €24.25 in November 2027 and €19.64 in November 2029, with a 30% probability because these risks are material but the company still has recurring revenue and positive net cash.
How much cash does Dassault Systèmes really make?
Our “real free cash flow” makes an analytical further deduction for employee stock awards. Subtracting €174.8 million of stock pay produced €1,204.8 million, or 19.3% of revenue. That is not a second cash-flow statement: the accounting cost of awards may differ from the cash required to offset dilution.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| = Free cash flow | 1,379.6 | 1,386.7 | 1,330.5 | 1,290.9 | 1,411.8 |
| − Stock pay | 174.8 | 190.4 | 184.2 | 166.7 | 171.6 |
| = Real free cash flow | 1,204.8 | 1,196.3 | 1,146.3 | 1,124.2 | 1,240.2 |
| Free cash flow, % of revenue | 22.1% | 22.3% | 22.4% | 22.8% | 29.0% |
| Real free cash flow, % of revenue | 19.3% | 19.3% | 19.3% | 19.8% | 25.5% |
What this means. The company's own free cash flow is slightly higher only because it rounds the numbers and adds back a tiny amount, not because it counts more cash.
What does an investor pay today for Dassault Systèmes?
| Today (Nov 1, 2026) | |
|---|---|
| Share price | 25.26 |
| Market value (calculated) | 33,440.77 |
| Enterprise value (calculated) | 32,391.87 |
| P/E, last 12 months (calculated) | 25.5x |
| P/E, next 12 months (calculated) | 17.5x |
| Real free cash flow yield (calculated) | 3.6% |
What this means. The next-year price-to-earnings number uses analysts’ expected profit, so it is an estimate and may be wrong.