Anglo earnings: latest results and guidance
MyStockButler's October 2026 analysis: Anglo reported continuing revenue of $9,926 million, up 11%, and underlying EBITDA of $4,002 million; continuing shareholder profit was $301 million, or $0.28 of diluted EPS. Watch whether better ore access and dependable water support the guided copper recovery.
What has Anglo guided for 2026 and 2027?
Management guides to 700–760 kt of copper and 55–59 Mt of premium iron ore in 2026. The 2027 ranges are 750–810 kt and 59–63 Mt. Copper unit-cost guidance is 145 cents per pound in 2026. Premium iron ore guidance is $41 per tonne. Continuing-operations capital expenditure is $3.2 billion in 2026, alongside a 40% dividend payout ratio.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Copper production (kt) — 2026F | Year to Dec 2026 | 700 | 760 | Jul 30, 2026 |
| Copper production (kt) — 2027F | Year to Dec 2027 | 750 | 810 | Jul 30, 2026 |
| Premium Iron Ore production (Mt) — 2026F | Year to Dec 2026 | 55 | 59 | Jul 30, 2026 |
| Premium Iron Ore production (Mt) — 2027F | Year to Dec 2027 | 59 | 63 | Jul 30, 2026 |
| Copper unit costs (c/lb) | Year to Dec 2026 | 145 | 145 | Jul 30, 2026 |
| Premium Iron Ore unit costs (US$/t) | Year to Dec 2026 | 41 | 41 | Jul 30, 2026 |
How have Anglo’s revenue and profit changed?
The stronger financial figures cover the first half, not the second quarter alone. Continuing revenue reached $9,926 million, up 11%, and underlying EBITDA rose 35% to $4,002 million. Copper prices, cost control and lower De Beers losses supported the improvement.
Continuing shareholder profit was $301 million, or $0.28 of diluted EPS. A $411 million special tax charge, including $368 million linked to an internal reorganisation, obscured the operating result. Removing the combined special tax and currency charge would produce $637 million of continuing profit, but the currency element may recur.
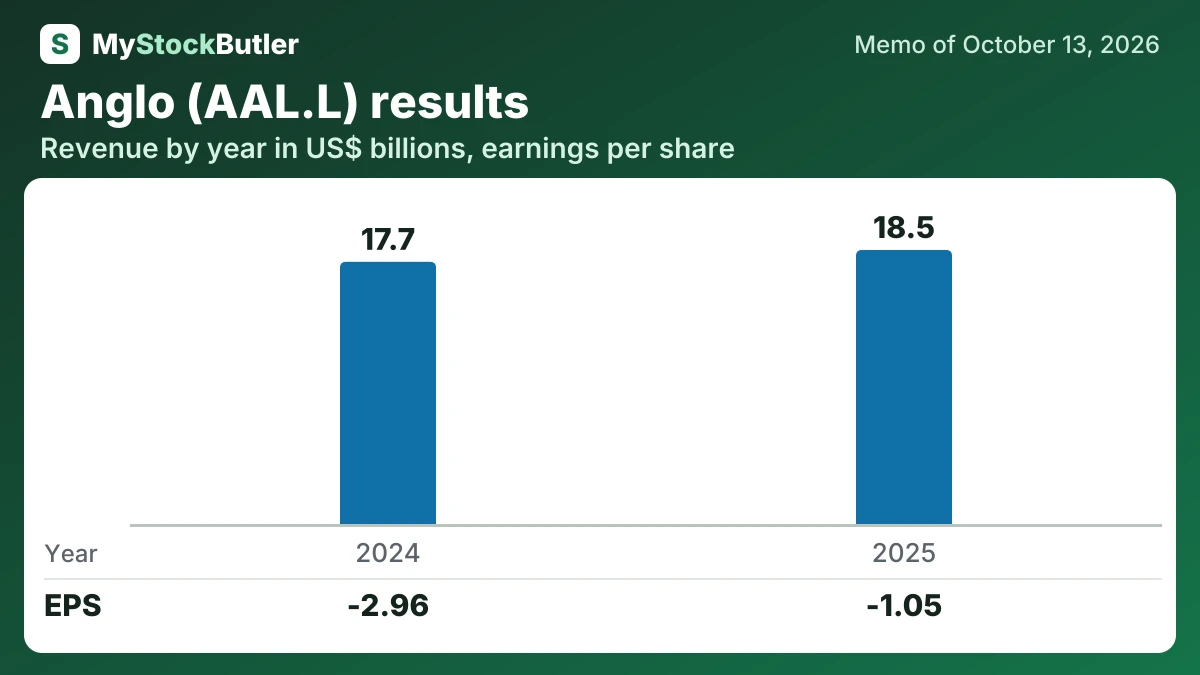
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Revenue | 18,546 | 17,745 | |||
| Revenue growth (calculated) | 4.5% | ||||
| Operating income | 1,352 | -975 | |||
| Net income | -1,192 | -3,166 | |||
| Net margin (calculated) | -6.4% | -17.8% | |||
| EPS, diluted | -1.05 | -2.96 |
What should Anglo watch in the 20 October 2026 production report?
The next production report, scheduled for 20 October 2026, should show whether Chile is delivering the second-half improvement. Better-ore access at Los Bronces and Collahuasi matters because processing poorer rock efficiently still produces less copper.
Water is equally important. Copper plants use water to grind ore, separate the metal and manage waste, recycling much of it but still requiring reliable fresh supply. Anglo has been using alternatives after a Chilean tribunal set aside the environmental authorisation for Collahuasi’s desalination project. Seawater supplied 41% of Chilean copper-mining water in 2024, so the useful milestone is not a nearly finished plant but legally authorised, dependable water at the mine.