Stella-Jones stock forecast 2027–2029
MyStockButler's October 2026 analysis: Stella-Jones's weighted scenario reaches C$96.80 by October 2029, including dividends. It hinges on demand normalizing, margins recovering, capacity filling and cash converting.
Where could Stella-Jones's shares be in each forecast year?
The weighted forecast is C$73.44 in October 2027 (+10%) and C$96.80 in October 2029 (+49%), including dividends. Bear, base and bull probabilities are 28%/54%/18%. October 2029 outcomes are C$48.01 in the bear case (-24%), C$104.09 in the base case (+60%) and C$150.83 in the bull case (+129%), including dividends.
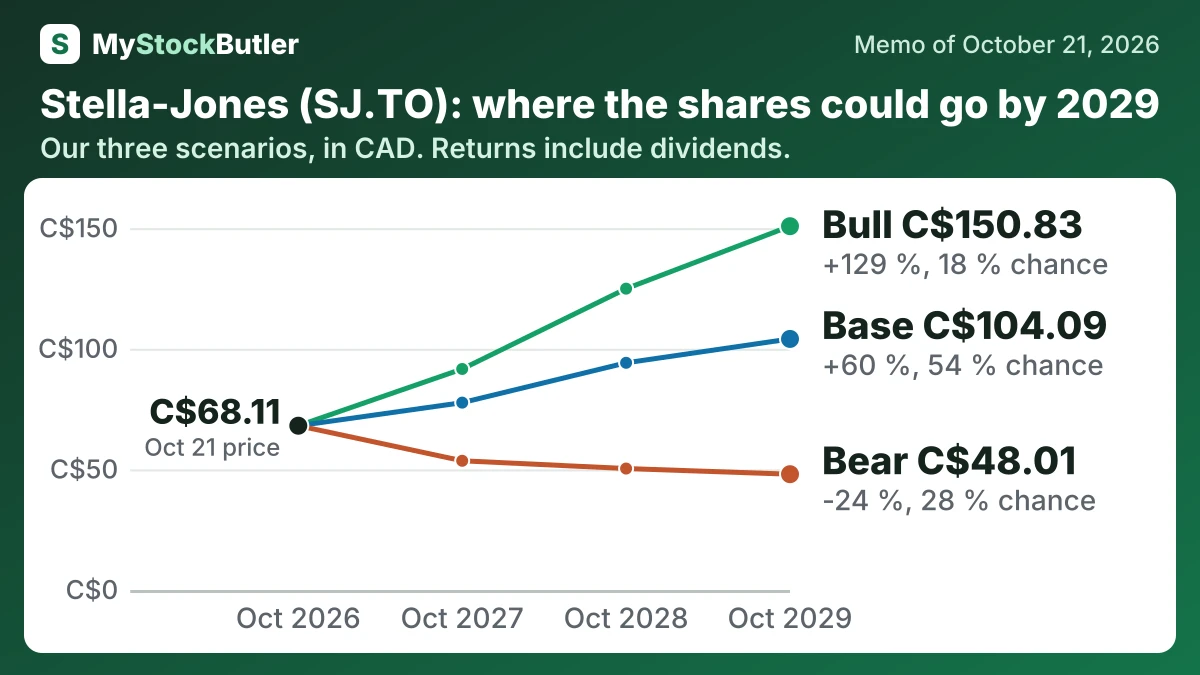
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 28 % | 53.57 (-19 %) | 50.35 (-22 %) | 48.01 (-24 %) |
| Base | 54 % | 77.68 (+16 %) | 94.19 (+43 %) | 104.09 (+60 %) |
| Bull | 18 % | 91.63 (+37 %) | 124.93 (+88 %) | 150.83 (+129 %) |
| Weighted | 100 % | 73.44 (+10 %) | 87.45 (+33 %) | 96.80 (+49 %) |
What has to go right for Stella-Jones, and what could go wrong?
The November 4, 2026 results call should show pole volumes becoming sales and margin, with railway demand improving without more treatment moving in-house. By year-end 2026, Candiac’s ramp and railway-network changes should show whether disruption is fading. Fayetteville should commission by the end of 2027 and reach full production ramp-up by the end of 2028; its US$50 million investment and 20,000-ton capacity must earn cash returns. Stella-Jones is a bet on converting long-lived infrastructure demand, inventory and capacity into durable cash flow.
The base case reaches C$77.68 in the first year and C$104.09 in the last. It assumes utility orders and railway purchases normalize, Candiac disruption fades, and Fayetteville ramps before the end of the period. Its 54% probability reflects a recovery that is plausible but not assured.
| October 2027 | October 2028 | October 2029 | |
|---|---|---|---|
| Earnings | 299 (242 / 326) | 359 (247 / 409) | 393 (257 / 457) |
| Shares (millions) | 53.94 (54.22 / 53.41) | 53.37 (53.93 / 52.39) | 52.86 (53.61 / 51.48) |
| Dividends per share | 1.45 (1.36 / 1.48) | 1.57 (1.36 / 1.70) | 1.69 (1.24 / 1.94) |
| Price to earnings | 14.00 (12.00 / 15.00) | 14.00 (11.00 / 16.00) | 14.00 (10.00 / 17.00) |
How much cash does Stella-Jones really make?
That release can reflect timing rather than new economics: wood bought earlier can produce cash when shipped later without creating equivalent new earnings. Free cash flow also depends on the definition used. Stella-Jones spent C$103 million on capital and C$66 million on leases in 2025. On that basis, free cash flow was C$388 million. Subtracting C$14 million of stock compensation leaves C$374 million of economic, or “real,” free cash flow.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 557 | 408 | 107 | 255 | 251 |
| Of which, freed from working capital | 95 | ||||
| Of which, tied up in working capital | 57 | 345 | 105 | 23 | |
| − Capital spending | 103 | 132 | 155 | 97 | 48 |
| − Lease payments | 66 | 62 | 50 | 41 | 35 |
| − Interest paid | 0 | 0 | 0 | 0 | 0 |
| = Free cash flow | 388 | 214 | -98 | 117 | 168 |
| − Stock pay | 14 | 14 | 13 | 7 | 4 |
| = Real free cash flow | 374 | 200 | -111 | 110 | 164 |
| Free cash flow — the company's own count | 414 | 247 | -48 | 139 | 152 |
| What its own count adds back | 26 | 33 | 50 | 22 | |
| What its own count also takes out | 16 | ||||
| Free cash flow, % of revenue | 11.1% | 6.2% | -3.0% | 3.8% | 6.1% |
| Real free cash flow, % of revenue | 10.7% | 5.8% | -3.3% | 3.6% | 6.0% |
What this means. The company’s own free cash flow is higher because it leaves out some lease and other spending that we count.
What does an investor pay for Stella-Jones today?
At C$68.11 on October 21, 2026, the market values Stella-Jones’ shares at C$3,716.60 million. Its trailing price-to-earnings ratio, or P/E, is 14.4x. That means investors pay 14.4 times the profit earned over the last twelve months, assuming that profit is repeatable.