Masco stock forecast 2027–2029
MyStockButler's October 2026 analysis: Masco’s weighted case is $79.30 by October 2027. It hinges on durable unit growth and cash after tariff relief fades.
Where could Masco's shares be by 2029?
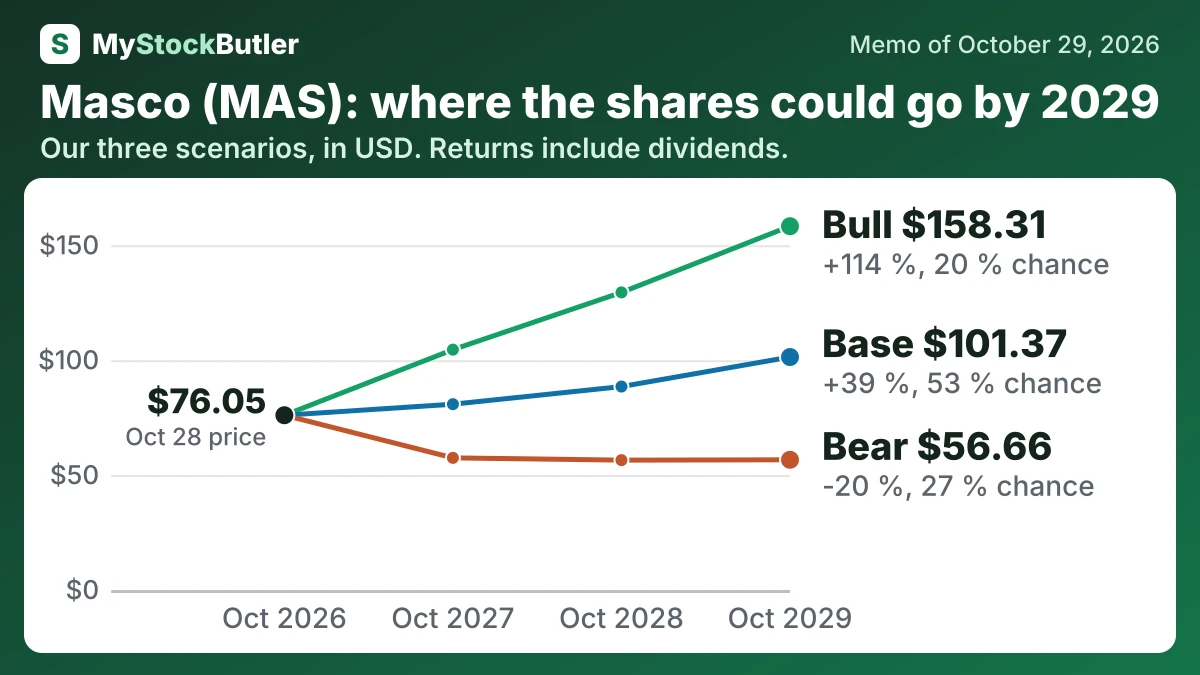
The weighted case puts the price at $79.30 by October 2027. That is a 6% total return. By October 2029, it reaches $100.69. That is a 38% total return. The bear case carries 27% probability. The base case carries 53%. The bull case carries 20%.
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 27 % | 57.49 (-23 %) | 56.51 (-22 %) | 56.66 (-20 %) |
| Base | 53 % | 80.86 (+8 %) | 88.53 (+20 %) | 101.37 (+39 %) |
| Bull | 20 % | 104.60 (+39 %) | 129.50 (+74 %) | 158.31 (+114 %) |
| Weighted | 100 % | 79.30 (+6 %) | 88.08 (+19 %) | 100.69 (+38 %) |
What this means. The weighted row is the probability-based average of the bear, base, and bull cases, not a guaranteed share price.
What has to go right for Masco's forecast?
At fourth-quarter 2026 results and the 2027 call, margins and cash generation without the tariff refund are the first test. Through 2027–2029, unit growth in plumbing and professional paint must accompany earnings. By 2028, Masco needs 3%–4% organic sales growth and adjusted margins toward 18%. The base case assumes $650 million of annual buybacks. Masco’s 2026 plan calls for $1 billion. The recovery requires durable unit growth and cash, not price and buybacks alone.
The bear row falls to $1.18 billion in the first period, then $1.20 billion in the second and $1.24 billion in the third. The bull row reaches $1.46 billion in the first period and $1.57 billion in the second, before reaching $1.68 billion. The bear assumes weak volume and cost pressure; the bull requires sustained unit gains and productivity after tariff relief ends.
How much cash does Masco really make?
Masco’s cash from operations exceeded net income in 2025. Capital spending reduced the amount available as free cash flow, while subtracting stock pay gives a stricter view of cash available to owners. The comparison across years is noisy: working capital released cash in 2023, a pension-plan adjustment affected 2021, and a 2025 tax law improved the timing of deductions.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 1,022 | 1,075 | 1,413 | 840 | 930 |
| − Capital spending | 156 | 168 | 243 | 224 | 128 |
| = Free cash flow | 866 | 907 | 1,170 | 616 | 802 |
| − Stock pay | 30 | 39 | 31 | 49 | 61 |
| = Real free cash flow | 836 | 868 | 1,139 | 567 | 741 |
| Real free cash flow, % of revenue | 11.1% | 11.1% | 14.3% | 6.5% | 8.8% |
What this means. The company's own free cash flow differs because it adds back 94 million dollars of pension payments in 2021 and removes a 40 million dollar insurance payment in 2023, while our count includes both.
What does an investor pay for Masco today?
Market value is what shareholders’ ownership costs. Enterprise value estimates the operating business while adding debt and subtracting cash, so it shows the claims that stand ahead of shareholders. Masco’s long-term debt was $3.245 billion, while cash was $610 million. The difference matters because two companies with the same P/E can leave shareholders with very different financing risks.
| Today (Oct 29, 2026) | |
|---|---|
| Share price | 76.05 |
| Market value (calculated) | 14,660.09 |
| Enterprise value (calculated) | 17,297.09 |
| P/E, last 12 months (calculated) | 16.5x |
| P/E, next 12 months (calculated) | 16.8x |
| Real free cash flow yield (calculated) | 5.7% |
What this means. Price to book is not meaningful because the company owes more than it owns on its accounting books.