FICO stock forecast 2027–2029
MyStockButler's October 2026 analysis: FICO’s weighted outcome is $782.62 in October 2027, a 4% loss including dividends. It hinges first on delivered-loan usage, realized pricing and equivalent-population performance.
Where could FICO's shares be by 2029?
The range is much wider than the weighted path. By October 2029, the bear case gives $469.36 while the bull case gives $1,521.66, against today’s $815.31. The base case receives 50% weight. The bear case receives 30%, and the bull case receives 20%.
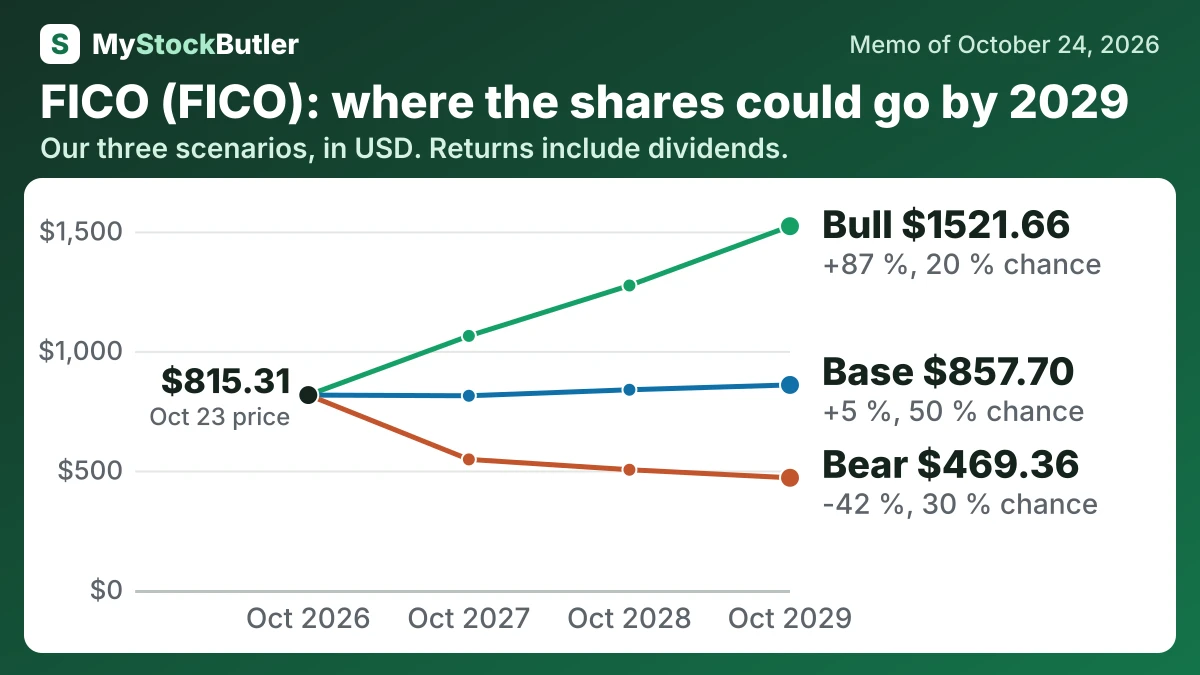
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 30 % | 546.21 (-33 %) | 502.95 (-38 %) | 469.36 (-42 %) |
| Base | 50 % | 812.39 (-0 %) | 837.55 (+3 %) | 857.70 (+5 %) |
| Bull | 20 % | 1062.82 (+30 %) | 1273.63 (+56 %) | 1521.66 (+87 %) |
| Weighted | 100 % | 782.62 (-4 %) | 824.39 (+1 %) | 873.99 (+7 %) |
What this means. The weighted row is the average expected share price after giving more weight to the cases considered more likely.
What has to go right, and what could go wrong for FICO?
The base case assumes earnings grow steadily but not spectacularly. Earnings rise from $957 million in October 2027 to $1,040 million in October 2028, then to $1,127 million in October 2029. The path uses normalized revenue of $2,750 million and a 34.8% net margin initially, followed by the revenue and margin progression shown below. It assumes FY2026 guidance is broadly delivered, Platform growth offsets legacy declines and cash flow supports debt reduction.
The bear case gives earnings of $835 million, then $830 million, and finally $840 million. It assumes revenue grows from $2,650 million but margins fall from 31.5% because mortgage price pressure, migration costs, interest and software costs offset growth. The bull case reaches $1,012 million initially and $1,144 million in the following year, before $1,295 million. It assumes broad mortgage retention, better direct-licensing economics and net-new Platform demand.
How much cash does FICO really make?
Capital spending of $39.4 million leaves free cash flow of $739.4 million, or 37.1% of revenue. FICO’s own measure agrees. A stricter calculation deducts stock pay of $156.7 million as an allowance for the ownership transferred to employees, leaving real free cash flow of $582.7 million, or 29.3% of revenue. This is an analytical measure, not a separate cash balance, but it gives existing shareholders a more demanding view.
| Sep 2025 | Sep 2024 | Sep 2023 | Sep 2022 | Sep 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 778,807 | 632,964 | 468,915 | 509,450 | 423,817 |
| − Capital spending | 39,407 | 25,551 | 4,237 | 6,029 | 7,569 |
| = Free cash flow | 739,400 | 607,413 | 464,678 | 503,421 | 416,248 |
| − Stock pay | 156,667 | 149,439 | 123,847 | 115,355 | 112,457 |
| = Real free cash flow | 582,733 | 457,974 | 340,831 | 388,066 | 303,791 |
| Real free cash flow, % of revenue | 29.3% | 26.7% | 22.5% | 28.2% | 23.1% |
What this means. The working capital amount is already included in cash from operations, so it is shown for context and is not subtracted again.
What does an investor pay for FICO today?
The forward P/E looks modest against FICO’s recent history, but it uses expected earnings rather than completed results. Its implied earnings must therefore arrive after the July 2026 guidance year, or depend on a different earnings definition. Cash offers a second test. FICO generated $961 million of free cash flow over the last four quarters, but the adjusted cash-flow yield is lower than the ordinary measure. In the simple illustration, a 10% required return leaves about 6.7% continuing annual growth to be supplied by cash-flow expansion. That is a condition of the valuation, not a forecast.
| Today (Oct 24, 2026) | |
|---|---|
| Share price | 815.31 |
| Market value (calculated) | 17,608,767.792 |
| Enterprise value (calculated) | 22,946,969.792 |
| P/E, last 12 months (calculated) | 23.6x |
| P/E, next 12 months (calculated) | 16.7x |
| Real free cash flow yield (calculated) | 3.3% |
What this means. Price to book is not meaningful because the company owes more than it owns on its books, making its book value negative.