DCC stock forecast 2027–2029
MyStockButler's October 2026 analysis: DCC's weighted price is 4973.44 GBp in October 2029. It hinges on whether the takeover completes.
Where could DCC's shares be by October 2029?
The weighted price is 4681.24 GBp in October 2028, a -25% return. It reaches 4973.44 GBp in October 2029, still a -20% return.
The October 2029 range is wide: 2357.55 GBp in the bear case to 7126.97 GBp in the bull case, against today’s 6445.00 GBp. The forecast assigns 20% to the bear case, 68% to the base case and 12% to the bull case.
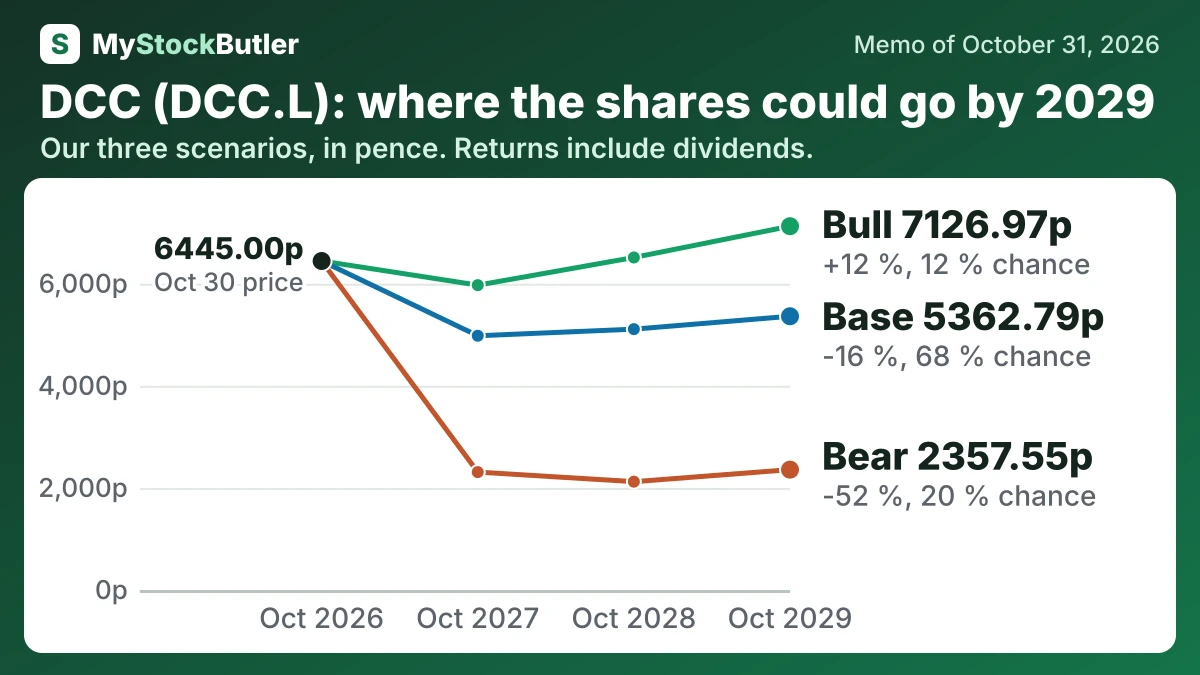
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 20 % | 2309.76 (-61 %) | 2122.15 (-60 %) | 2357.55 (-52 %) |
| Base | 68 % | 4980.69 (-22 %) | 5110.44 (-20 %) | 5362.79 (-16 %) |
| Bull | 12 % | 5971.91 (-6 %) | 6514.22 (+2 %) | 7126.97 (+12 %) |
| Weighted | 100 % | 4565.45 (-28 %) | 4681.24 (-25 %) | 4973.44 (-20 %) |
What has to go right for DCC's forecast?
That path reflects UGI’s acquired liquid-gas businesses, modest organic growth and stable unit economics. UGI contributes about ten months of the first forecast year, while Energy adjusted operating profit grew 3.5% in FY2026, though organic growth was only 1.3%. The bear case gives £247m initially and falls to £242m before recovering to £253m, because the takeover fails, Services remains weak and Products volumes and margins suffer. Energy Services profit fell from £48.3m to £15.7m.
The bull case gives £364m initially and rises to £398m. It reaches £435m if UGI integrates well, Products’ improved profit per litre holds and Services recovers. Products’ adjusted operating profit per litre rose from 3.3p to 3.8p, but the Services recovery remains unproven.
How much cash does DCC really make?
DCC’s free-cash-flow measure deducts capital spending and lease repayments but comes before most interest, tax and exceptional cash costs. Group free cash flow was £689.62 million in 2026, while the figure after the company’s interest and tax adjustments was £491.57 million. The Energy measure and the group measure therefore answer different questions.
| Mar 2026 | Mar 2025 | Mar 2024 | Mar 2023 | Mar 2022 | |
|---|---|---|---|---|---|
| − Capital spending | 151,800 | 159,500 | 177,600 | 173,100 | 135,800 |
| − Interest paid |
What this means. The capital spending figure is the money spent on equipment and buildings after subtracting money received from selling assets and grants, so it is not the full amount paid.
What does an investor pay for DCC today?
| Today (Oct 31, 2026) | |
|---|---|
| Share price | 6,445.0 |
| Market value (calculated) | 5,507.19 |
| P/E, next 12 months (calculated) | 12.7x |
| Dividend yield (calculated) | 3.4% |
What this means. The next-year price-to-earnings ratio uses analysts’ expected profit per share, but the source does not say which parts of the company those forecasts cover.