Corpay earnings date
MyStockButler's October 2026 analysis: The next Corpay results are expected on November 4, 2026. Watch whether implementations become active payments.
What has Corpay guided for 2026?
Management guides to 10% organic revenue growth in 2026 and adjusted diluted EPS of $27.15–$27.55, versus GAAP diluted EPS guidance of $19.50–$19.90. The $644 million of pre-tax adjustments makes cash conversion and recurring costs central tests of that promise.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Total revenues | Year to Dec 2026 | 5,290 | 5,330 | Aug 5, 2026 |
| Net income per diluted share (Year to Dec 2026) | Year to Dec 2026 | 19.50 | 19.90 | Aug 5, 2026 |
| Adjusted net income per diluted share (Year to Dec 2026) | Year to Dec 2026 | 27.15 | 27.55 | Aug 5, 2026 |
| Organic revenue growth (Year to Dec 2026) | Year to Dec 2026 | 10.0% | 10.0% | Aug 5, 2026 |
| Cash EPS growth | Year to Dec 2026 | 28.0% | 28.0% | Aug 5, 2026 |
| Full-year free cash flow | Year to Dec 2026 | 1,800 | 1,800 | Aug 5, 2026 |
What this means. Corpay's stated free cash flow is its adjusted net income, while our usual free cash flow means cash from operations minus spending on equipment.
Did Corpay keep its past promises?
The record is mixed. Across seven quarters, adjusted EPS beat guidance three times and landed within it four times. GAAP EPS fell below guidance in four of those quarters. Impairments, transaction costs, taxes and the FTC settlement explain some volatility, but a business-sale gain helped GAAP earnings in another quarter. Annual GAAP guidance fell in both 2025 and 2026; in August 2026, the range moved from $20.39–$21.19 to $19.50–$19.90.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Total revenues | 6 quarters | 3 | 2 | 1 |
| Net income per diluted share | 7 quarters | 2 | 1 | 4 |
| Adjusted net income per diluted share | 7 quarters | 3 | 4 | 0 |
What this means. The revenue forecast includes the company's receivables business and assumes the announced epyx sale, so future purchases or sales of businesses could change the result.
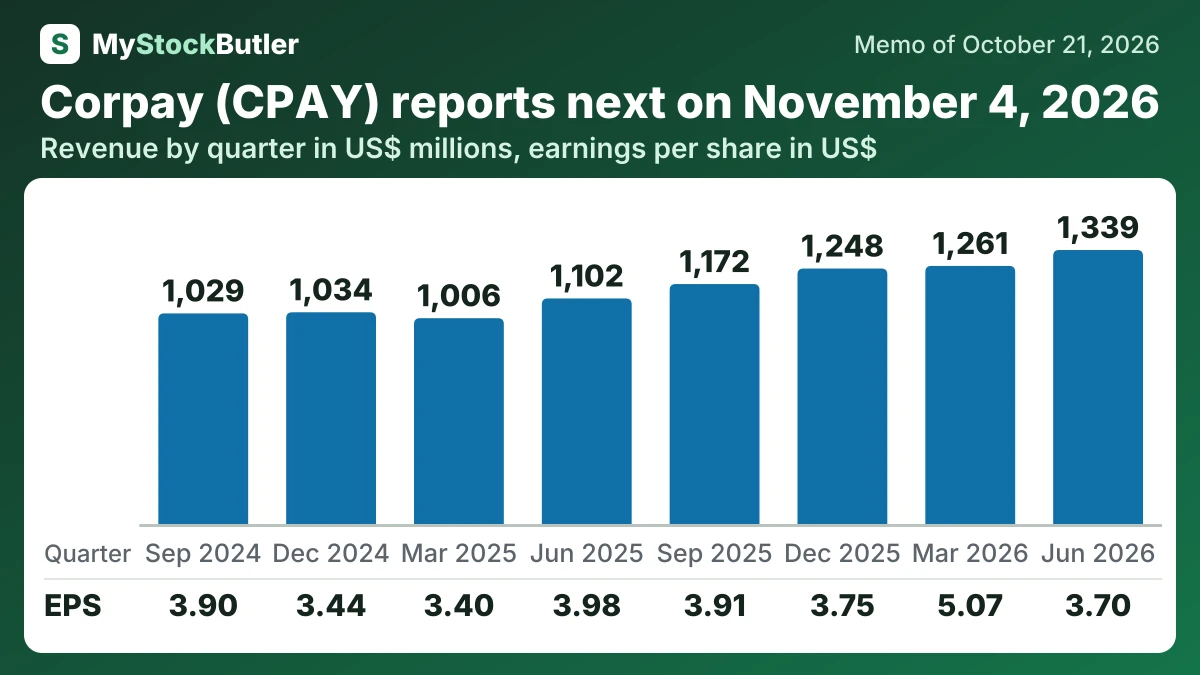
What do Corpay's last eight quarters show?
Revenue grew approximately 21.5% year-on-year and gross margin improved. Operating income and net income nevertheless fell because Corpay recorded a $100 million provision for a preliminary FTC settlement. Removing that charge would leave operating income of $572,274 thousand and an operating margin of 42.7%, showing stronger underlying operations without pretending the legal cost is unreal.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 1,338,809 | 1,260,987 | 1,248,226 | 1,172,480 | 1,102,030 | 1,005,667 | 1,034,431 | 1,029,197 |
| Gross margin | 79.4% | 78.4% | 79.2% | 78.8% | 78.4% | 77.9% | 77.9% | 78.3% |
| Operating income | 472,274 | 636,165 | 564,474 | 523,120 | 479,390 | 427,124 | 488,348 | 468,132 |
| Net income | 248,307 | 350,066 | 264,484 | 277,941 | 284,168 | 243,233 | 245,955 | 276,397 |
| EPS, diluted | 3.70 | 5.07 | 3.75 | 3.91 | 3.98 | 3.40 | 3.44 | 3.90 |
| = Free cash flow | 1,415,662 | -107,712 | 760,297 | -429,841 | 1,087,611 | -118,922 | 604,563 | 355,010 |
What this means. Cash from operations can look sharply negative in some quarters because the quarterly figure is calculated by subtracting one year-to-date total from the previous one, not because the company necessarily spent all that cash in that quarter.
What should I watch in Corpay's next results?
Third-quarter results are the next operating checkpoint. Watch revenue against $1,355 million and adjusted EPS against $7.05–$7.25. Then compare organic growth with 9%–11%. Also watch the planned sale of epyx, r2c Online and Business Gateway, because Corpay expects repurchases funded by the proceeds to offset lost earnings.
Customer quality matters as much as sales. Corpay reported 93.0% revenue retention and 30% sales growth for Q2. But the retention measure recently began including cross-border and excludes businesses owned for less than a year. The next test is whether implementations become active payments and whether existing customers keep producing revenue. That leads directly to the Mastercard channel.