Albemarle dividend: cash coverage and yield
MyStockButler's October 2026 analysis: Albemarle's base-case dividend is 1.64 per share and rises to 1.72 in 2029. Albemarle's 2025 free cash flow was $692.5 million, but lower spending, a $350 million customer prepayment and working-capital releases helped the recovery, so the coverage is not presented as durable.
How much does Albemarle pay per share?
The base dividend begins at 1.64 per share and rises to 1.68 in 2028. It reaches 1.72 in 2029. The bear holds at 1.64 before cutting to 1.00, while the bull rises from 1.68 to 1.92. The base extends the steady dividend record and the declared quarterly rate of 0.41. The bear reflects the risk that weak cash generation and heavy investment overwhelm that record; the bull requires sustained cash flow.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
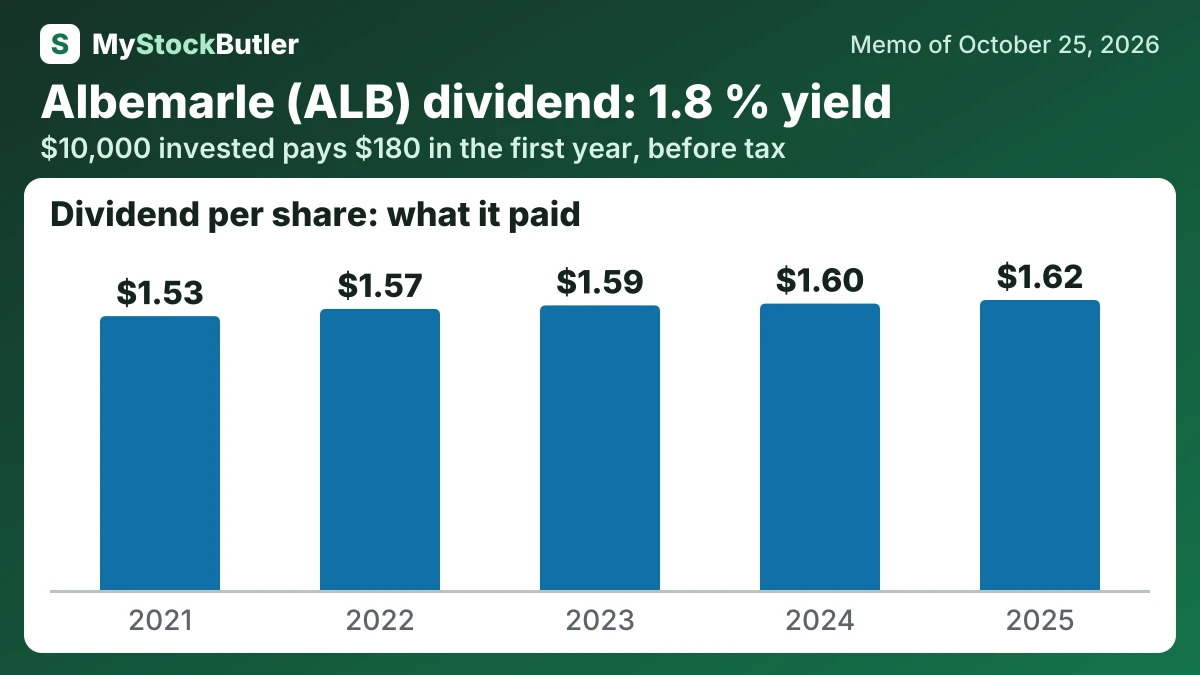
| − Dividends paid, per share | 1.62 | 1.60 | 1.59 | 1.57 | 1.53 |
What this means. The company's own free cash flow per share is higher because it does not subtract shares given to employees as pay; we subtract that pay to show what remains for existing shareholders.
How much would Albemarle's dividend pay you?
$10,000 invested in Albemarle at its 1.8% dividend yield (our report of October 25, 2026) pays $180.00 in the first year, before tax. If its dividend per share keeps changing 1.4% a year, as it did from 2021 to 2025, and the dividends are reinvested, year 10 pays $242.64, with $2,096.02 received in all.
Before tax. Past dividend growth is not a promise. Information only, not investment advice.
Does Albemarle's dividend come from its cash?
Free cash flow was $692.5 million in 2025, compared with negative $992.7 million in 2024. The improvement mostly reflects the fall in construction spending, not an equivalent rise in durable profit. Slowing or completing expansion releases cash immediately, but does not prove that the same cash can be distributed every year.
The $350 million customer prepayment is especially important. A customer paid before receiving lithium, like a builder receiving a deposit before finishing a house. The receipt strengthens current cash but creates a delivery obligation, so it is not sustainable revenue or free cash flow.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Free cash flow | 692,466 | -992,653 | -827,959 | 650,770 | -609,410 |
| − Dividends paid | 190,530 | 188,530 | 187,188 | 184,429 | 177,853 |
| − Share buybacks | 0 | 0 | 0 | 0 | 0 |
| = Free cash flow not paid out | 483,767 | 422,133 | |||
| Paid out, % of free cash flow | 27.5% | not meaningful | not meaningful | 28.3% | not meaningful |
What could change Albemarle's dividend?
The base case is supported if the $500 million capital plan and cost improvements hold through 2026–2028, while Q2's operating recovery persists. The March 2027 preferred conversion remains a fixed dilution event that can reduce per-share gains even if earnings improve.
The view would move toward the bear case if lithium prices weaken from late 2026 through 2029, because contract and inventory lags would delay the margin damage. A CGP3 delay after the June 2026 fire would constrain volumes during 2027 and 2028.
What is Albemarle's dividend yield against its price?
| Today (Oct 25, 2026) | |
|---|---|
| Share price | 93.67 |
| Free cash flow yield (calculated) | 5.5% |
| Real free cash flow yield (calculated) | 5.1% |
| Dividend yield (calculated) | 1.8% |
What this means. The price-to-earnings measure is 346.9 times for the past year but 9.6 times for the coming year because the company earned very little recently and analysts expect much more profit next year.