Airtel Africa stock forecast 2027–2029
MyStockButler's October 2026 analysis: Airtel Africa’s weighted forecast is 460.18p in October 2027 and 683.68p in October 2029, including dividends. It hinges on whether network spending becomes durable cash, not just more usage.
Where could Airtel Africa's shares be by 2029?
Airtel Africa’s share price could rise from 282.2p to 683.68p in October 2029, but the outcome hinges on durable EBITDA growth, cash conversion and returns from network investment. Management reaffirmed $1,100 million of FY27 capex guidance in July 2026; it excludes spectrum acquisitions and licence renewals. The weighted forecast is 460.18p in October 2027, a 65% return including dividends, and 683.68p in October 2029, a 148% return including dividends. It assigns 25% probability to the bear case, 55% to base and 20% to bull. The test is whether data traffic, customer retention and paid usage sustain growth while margins and net debt hold up. The half-year report on 30 October 2026 is the next catalyst. The $110 million buyback programme is expected to end by 27 November 2026, while spending competes with elevated network investment. The investment case is simple: network spending must become durable cash, not just more usage.
The October 2029 range is wide: 337.42p in the bear case to 1,061.48p in the bull case. That spread reflects uncertainty over currency, cash conversion, mobile-money monetisation and the returns from new network capacity.
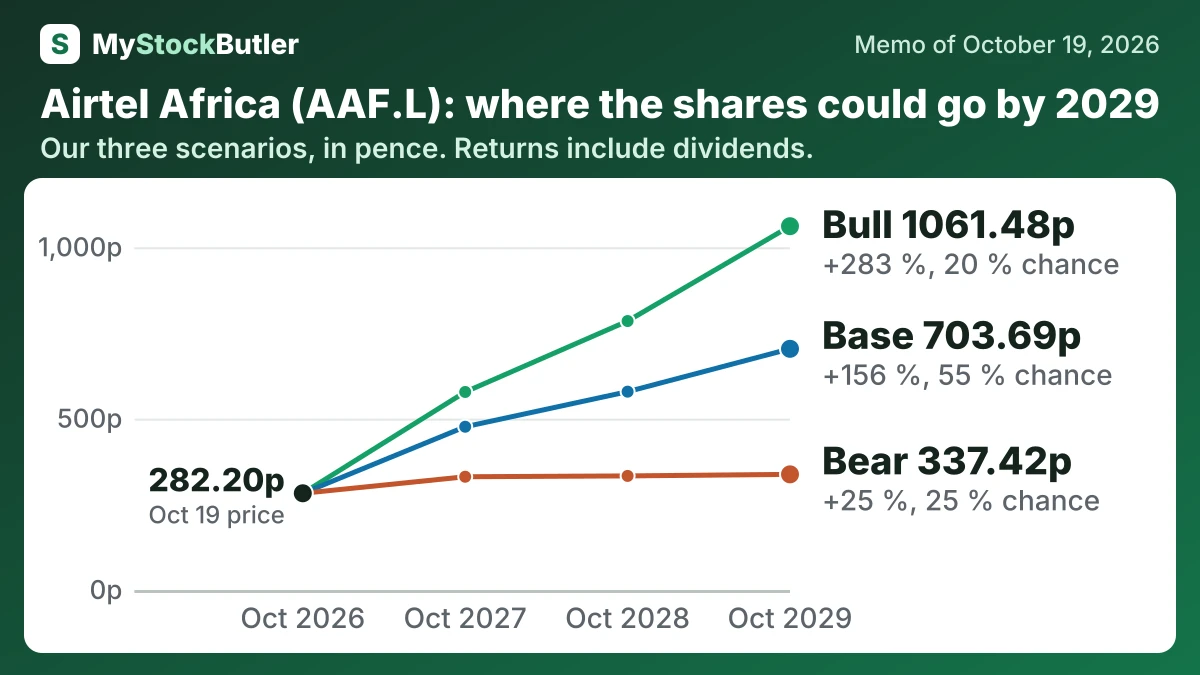
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 25 % | 330.47 (+19 %) | 332.89 (+21 %) | 337.42 (+25 %) |
| Base | 55 % | 476.38 (+71 %) | 578.70 (+109 %) | 703.69 (+156 %) |
| Bull | 20 % | 577.78 (+107 %) | 784.78 (+182 %) | 1061.48 (+283 %) |
| Weighted | 100 % | 460.18 (+65 %) | 558.46 (+102 %) | 683.68 (+148 %) |
What this means. The weighted value is an average that gives more weight to the cases considered more likely, rather than a promise that the shares will reach that price.
What has to go right for Airtel Africa, and what could go wrong?
FY26 adjusted EBITDA was $3,162m after two falling years. June-quarter EBITDA then reached $928m, with constant-currency growth of 24.4% and a 50.1% margin. Data usage per customer rose 27.7%, data revenue grew 35.2% at constant currency, and quarterly traffic rose 56.3%. The base case therefore rises through the three forecast dates, as shown in the table. The bear case allows currency weakness, fuel, tower and network costs to overwhelm volume growth. The bull case assumes higher-value data, better capacity utilisation and stronger Nigerian customer gains.
Net debt is the most demanding base-case assumption. June net debt was $1,321m. Base cash conversion of 88%, guided capex and $700m of other annual uses produce net cash by October 2028. The bear case uses 78% conversion and $850m of other uses, while the bull case uses $500m and reaches much larger net cash. FY26 free cash flow was $1,399m, but the historical gap between cash generation and debt movement shows why this row is uncertain.
| Mar 2026 | Mar 2025 | Mar 2024 | Mar 2023 | Mar 2022 | |
|---|---|---|---|---|---|
| Revenue growth | 29.5% | -0.5% | -5.3% | 11.5% | 20.6% |
| Operating margin | 33.0% | 29.4% | 32.9% | 33.4% | 32.6% |
| Real free cash flow, % of revenue | 14.7% | 14.2% | |||
| Net debt | 1,333 | 1,693 | 1,407 | 1,475 | 1,414 |
What this means. The blank free-cash-flow percentages for the last three years mean the report could not calculate them because the company did not disclose its total share-based pay expense.
How much cash does Airtel Africa really make?
Cash from operations reached $3,195m in fiscal 2026, compared with $2,266m in fiscal 2025. Working capital released $401m. Customers’ payments, suppliers’ bills and other balances therefore supplied an important part of the cash increase. That release may not recur, so the quality of cash generation matters as much as its size.
| Mar 2026 | Mar 2025 | Mar 2024 | Mar 2023 | Mar 2022 | |
|---|---|---|---|---|---|
| Cash from operations | 3,195 | 2,266 | 2,259 | 2,229 | 2,011 |
| − Capital spending | 753 | 736 | 868 | 779 | 717 |
| − Lease payments | 204 | 222 | 324 | 279 | 251 |
| − Interest paid | 839 | 670 | 440 | 400 | 370 |
| = Free cash flow | 1,399 | 638 | 627 | 771 | 673 |
| = Real free cash flow | 770 | 671 |
What this means. The company's free cash flow is higher because it leaves out money tied up in stock and unpaid customer bills, taxes, lease payments, and interest, so it counts cash that still has to be paid.