Smith+Nephew dividend: payout and cash cover
MyStockButler's October 2026 analysis: Smith+Nephew’s dividend per share is shown across its history and forecast, including the $0.391 2025 annual rate and a base path rising from $0.413 to $0.447. Cash coverage is mixed: free cash flow reached $802 million in 2025, but distributions exceeded free cash flow from 2021 through 2025.
How much does Smith+Nephew pay per share?
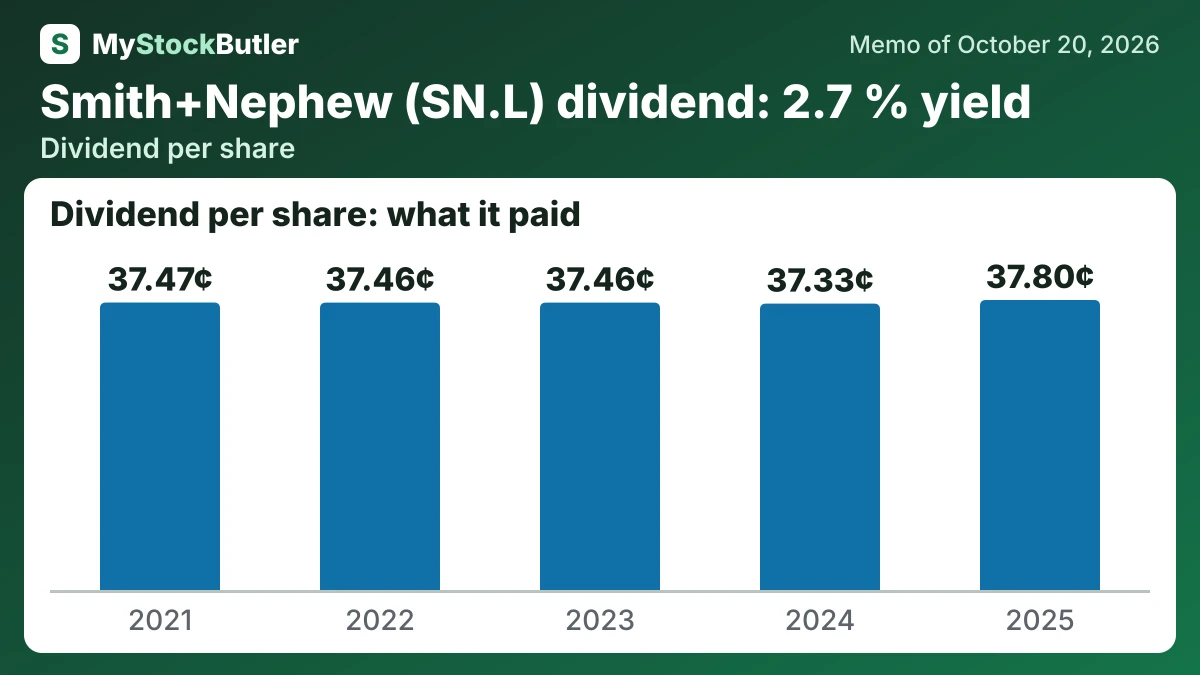
Base dividends per share rise from $0.413 to $0.447. The bear case falls to $0.370 and then freezes. The bull case reaches $0.472. The base path follows the progressive policy, the $0.391 2025 annual rate and the higher 2026 interim dividend.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| EPS, diluted | 71.60 | 47.00 | 30.10 | 25.50 | 59.70 |
| Real free cash flow per share | 86.94 | 58.33 | 10.31 | 1.83 | 42.03 |
| − Dividends paid, per share | 37.80 | 37.33 | 37.46 | 37.46 | 37.47 |
| = FCF not paid out, per share | 25.57 | 9.23 |
What this means. The company's own free cash flow per share is higher than our count in 2025 because it includes money from selling property, while our count leaves that money out.
Does Smith+Nephew’s cash cover its dividend?
Smith & Nephew’s cash recovery is real, but distributions have often left little for reinvestment. Free cash flow is the cash left after running the business and paying for capital expenditure; dividends and buybacks are separate choices about how to distribute it. From 2021 through 2025, distributions exceeded free cash flow, including in the cash squeeze of 2022 and again in 2025.
Cash from operations reached $1,285 million in 2025. Capital spending was $433 million. Lease payments were $50 million, leaving $802 million of free cash flow on a consistent basis before further shareholder-cost adjustments.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Free cash flow | 802 | 551 | 129 | 56 | 410 |
| − Dividends paid | 330 | 327 | 327 | 327 | 329 |
| − Share buybacks | 502 | 0 | 0 | 158 | 0 |
| = Free cash flow not paid out | 224 | 81 | |||
| = Paid out more than the free cash flow | 30 | 198 | 429 | ||
| Paid out, % of free cash flow | 103.7% | 59.3% | 253.5% | 866.1% | 80.2% |
What this means. The company's own net debt is higher because it includes lease liabilities and derivative balances, while our count leaves those out.
What could change Smith+Nephew’s dividend?
For FY2026, management guides to around 4% underlying revenue growth. It targets $1,300 million trading profit after Integrity Orthopaedics and $800 million of company free cash flow. FY2026 adjusted ROIC guidance is at least 10%. RISE targets 6–7% organic revenue growth. It targets 9–10% trading-profit growth through 2028.
Broader LANDMARK availability is expected through 2027. Surgeon adoption and repeat knee procedures must follow. The Melton wound-manufacturing facility is scheduled to start operating in 2027; its value depends on productive throughput and returns on investment. RISE matters if underlying growth, repeat CORI procedures, sports-medicine demand, free cash flow and ROIC improve—not savings or placements alone.
What is Smith+Nephew’s dividend yield today?
| Today (Oct 20, 2026) | |
|---|---|
| Share price | 1,077.5 |
| Market value (calculated) | 9,023.34 |
| Enterprise value (calculated) | 11,149.40 |
| Free cash flow yield (calculated) | 6.7% |
| Dividend yield (calculated) | 2.7% |
What this means. The enterprise value is higher than the market value because it includes the company’s debt after subtracting its cash.