Smith+Nephew stock forecast 2027–2029
MyStockButler's October 2026 analysis: Smith+Nephew's probability-weighted price reaches 1,954.18 GBp in October 2029, a 90% return including dividends. It hinges on LANDMARK, CORI and other launches generating repeat procedures.
Where could Smith+Nephew's shares go?
The probability-weighted price is 1,478.35 GBp in October 2027, a 40% return including dividends. It reaches 1,699.33 GBp in October 2028, a 63% return. By October 2029, it reaches 1,954.18 GBp, a 90% return.
The 2029 bear case is 949.17 GBp. The bull case is 3,226.90 GBp, versus 1,077.50 GBp today. The forecast assigns 30% to the bear case, 50% to the base case and 20% to the bull case.
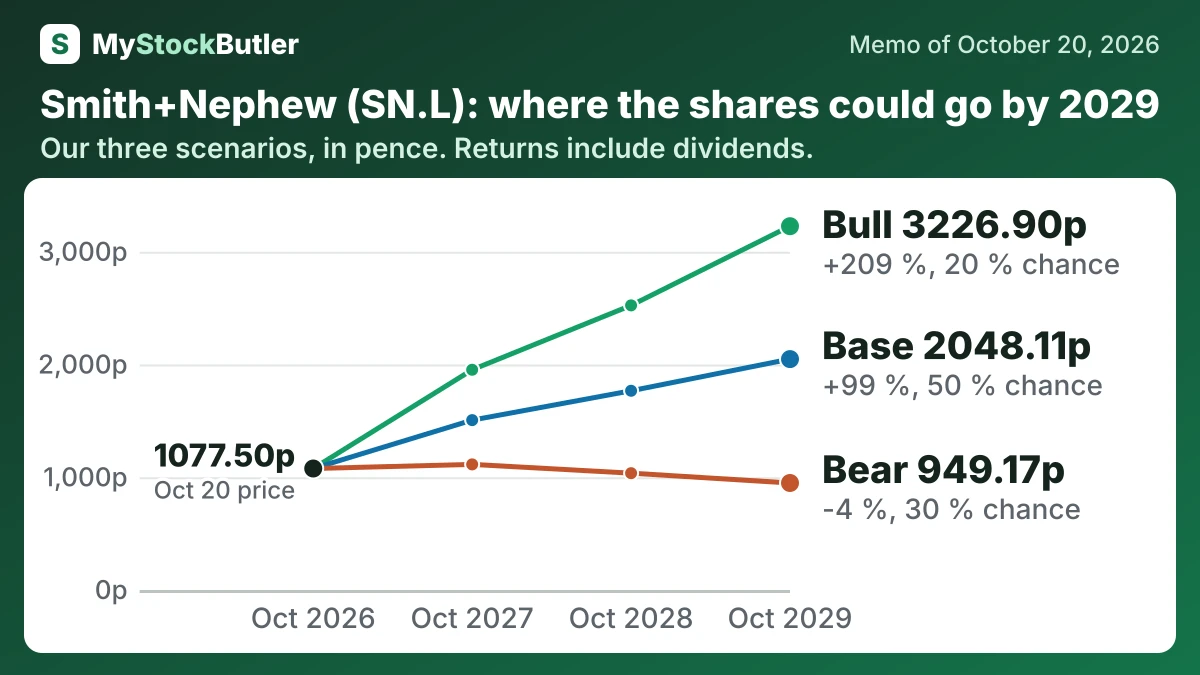
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 30 % | 1114.12 (+6 %) | 1036.14 (+1 %) | 949.17 (-4 %) |
| Base | 50 % | 1506.81 (+43 %) | 1767.13 (+70 %) | 2048.11 (+99 %) |
| Bull | 20 % | 1953.55 (+84 %) | 2524.60 (+140 %) | 3226.90 (+209 %) |
| Weighted | 100 % | 1478.35 (+40 %) | 1699.33 (+63 %) | 1954.18 (+90 %) |
What this means. The weighted row is the average value after giving each case more or less influence based on its probability, so it is not a fourth outcome.
What has to go right for Smith+Nephew?
The bear case gives $870 million in the first year and remains near that level thereafter. Its margin falls to 12.7% as weak US knees, tenders and reimbursement pressure persist. The bull case reaches $1,312 million, with margin reaching 16.5%, if LANDMARK, CORI and other launches generate repeat procedures.
How much cash does Smith+Nephew really make?
Cash from operations reached $1,285 million in 2025. Capital spending was $433 million. Lease payments were $50 million, leaving $802 million of free cash flow on a consistent basis before further shareholder-cost adjustments.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 1,285 | 987 | 608 | 468 | 877 |
| − Capital spending | 433 | 381 | 427 | 358 | 408 |
| − Lease payments | 50 | 55 | 52 | 54 | 59 |
| = Free cash flow | 802 | 551 | 129 | 56 | 410 |
| − Stock pay | 43 | 40 | 39 | 40 | 41 |
| = Real free cash flow | 759 | 511 | 90 | 16 | 369 |
What does an investor pay for Smith+Nephew?
Free cash flow is therefore the better cross-check. The reported free cash flow yield is 6.7%, but that is not the same as the 2.7% dividend yield: the board can use cash for debt, acquisitions, instruments, inventory or buybacks. The table shows the valuation measures that investors are paying for.
| Today (Oct 20, 2026) | |
|---|---|
| Share price | 1,077.5 |
| P/E, last 12 months (calculated) | 19.5x |
| P/E, next 12 months (calculated) | 12.0x |
| EV / revenue, last 12 months (calculated) | 2.4x |
| Free cash flow yield (calculated) | 6.7% |
| Real free cash flow yield (calculated) | 6.3% |
What this means. The enterprise value is higher than the market value because it includes the company’s debt after subtracting its cash.