Rio earnings: guidance, results and what to watch
MyStockButler's October 2026 analysis: Revenue recovered to US$57,638 million in 2025, while operating income was US$14,936 million. Next release, watch Pilbara and Simandou sales against guidance, not just mine output.
What has Rio guided for 2026?
For a miner, guidance means tonnes and costs, not profits: Rio can influence production and efficiency, but not copper or iron ore prices. Its 2026 targets include 800–870 thousand tonnes of consolidated copper and 343–366 million tonnes of total iron ore sales.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Copper production (consolidated) (kt) | Year to Dec 2026 | 800 | 870 | Jul 29, 2026 |
| Total iron ore sales (Mt, 100%) | Year to Dec 2026 | 343 | 366 | Jul 29, 2026 |
| Pilbara sales (100% basis) (Mt) | Year to Dec 2026 | 323 | 338 | Jul 29, 2026 |
| Simandou sales (100% basis) (Mt) | Year to Dec 2026 | 5 | 10 | Jul 29, 2026 |
| Total Group (US$ billions, up to) | Year to Dec 2026 | 11 | 11 | Jul 29, 2026 |
Has Rio kept its productivity promise?
Rio reported US$650 million of annualised productivity benefits early in Trott’s tenure and US$870 million realised by the first half of 2026. Annualised means projecting the current pace across a full year; realised means benefits achieved during the period. The figures are not automatically cash available to owners because maintenance, wages, taxes, commodity prices and growth spending still matter. Rio also acknowledged that favourable prices helped its results.
How have Rio revenue and profit changed?
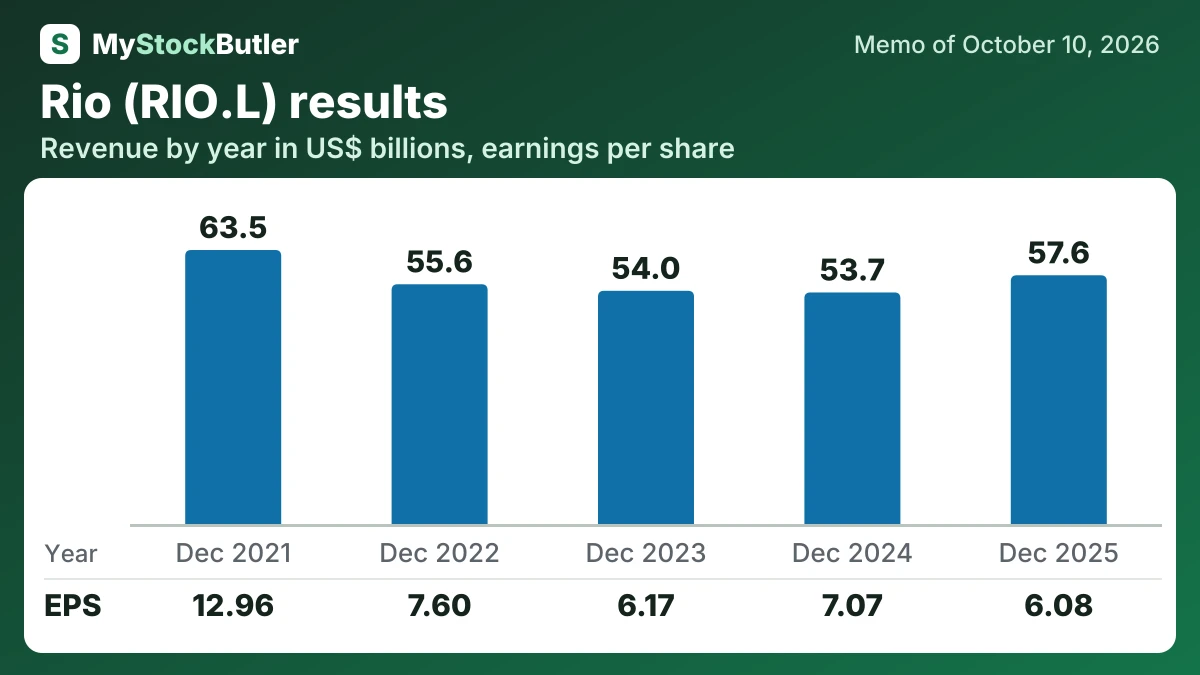
Rio is growing, but higher revenue does not prove that its established mines are performing better. Revenue recovered to US$57,638 million in 2025. Operating income was US$14,936 million, far below its 2021 level, because mining earnings depend heavily on the price received for each tonne while much of the cost base remains fixed.
Rio’s underlying earnings held steady in 2025, but reported returns weakened. Operating margin fell from 29.2% to 25.9%, while adjusted EBITDA rose from US$23,314 million to US$25,363 million. Adjusted net income barely moved because depreciation, financing and tax sit between operating performance and what shareholders receive.
| Year to Dec 2025 | Year to Dec 2024 | Year to Dec 2023 | Year to Dec 2022 | Year to Dec 2021 | |
|---|---|---|---|---|---|
| Revenue | 57,638 | 53,658 | 54,041 | 55,554 | 63,495 |
| Revenue growth (calculated) | 7.4% | -0.7% | -2.7% | -12.5% | 42.3% |
| Operating income | 14,936 | 15,653 | 14,823 | 19,933 | 29,817 |
| Net income | 9,966 | 11,552 | 10,058 | 12,392 | 21,115 |
| Net margin (calculated) | 17.3% | 21.5% | 18.6% | 22.3% | 33.3% |
| EPS, diluted | 6.08 | 7.07 | 6.17 | 7.60 | 12.96 |
What should I watch in Rio’s next release?
Through the rest of 2026, compare Pilbara and Simandou sales with guidance, not just mine output. Rising Simandou inventory could absorb cash if transport and crushing lag production. Costs will show whether extra tonnes came efficiently.