Mettler-Toledo earnings date and guidance
MyStockButler's October 2026 analysis: Mettler-Toledo's next results are expected on November 5, 2026. Watch whether improving demand produces enough cash to support both investment and repurchases.
What has Mettler-Toledo guided for 2026?
On July 30, MTD raised its full-year outlook to 4.0%–5.0% local-currency sales growth. It forecast adjusted EPS of $47.15–$47.50. Adjusted earnings exclude selected items such as purchased-intangible amortization and certain exceptional charges.
For the September quarter, MTD guided to 4.0% local-currency sales growth. It forecast adjusted EPS of $12.00–$12.15, implying EPS growth of 8.0%–9.0%.
| Period guided | Low | High | Date given | |
|---|---|---|---|---|
| Local currency sales growth — full year (%) | Year to Dec 2026 | 4.0% | 5.0% | Jul 30, 2026 |
| Adjusted EPS — full year | Year to Dec 2026 | 47.15 | 47.50 | Jul 30, 2026 |
| Adjusted EPS growth — full year (%) | Year to Dec 2026 | 10.0% | 11.0% | Jul 30, 2026 |
| Local currency sales growth — third quarter (%) | Quarter to Sep 2026 | 4.0% | 4.0% | Jul 30, 2026 |
| Adjusted EPS — third quarter | Quarter to Sep 2026 | 12.00 | 12.15 | Jul 30, 2026 |
| Adjusted EPS growth — third quarter (%) | Quarter to Sep 2026 | 8.0% | 9.0% | Jul 30, 2026 |
What this means. Other income means money the bank earns from fees, trading, and wealth management, rather than from interest.
Has Mettler-Toledo kept its past promises?
Management deserves 3/5 for its forecasting record. Sales beat initial guidance in three of five checked years. Adjusted EPS beat in four of five. In 2023, weaker demand led to reduced forecasts, followed by about $58 million of delayed European shipments that caused another miss. The record supports trusting management’s updates while testing the demand beneath them.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Local currency sales growth | 5 years | 3 | 1 | 1 |
| Adjusted EPS | 5 years | 4 | 0 | 1 |
What this means. The “Promises kept: 3/5” total does not match the rows, which show that four of five sales forecasts and four of five adjusted earnings-per-share forecasts were met or beaten.
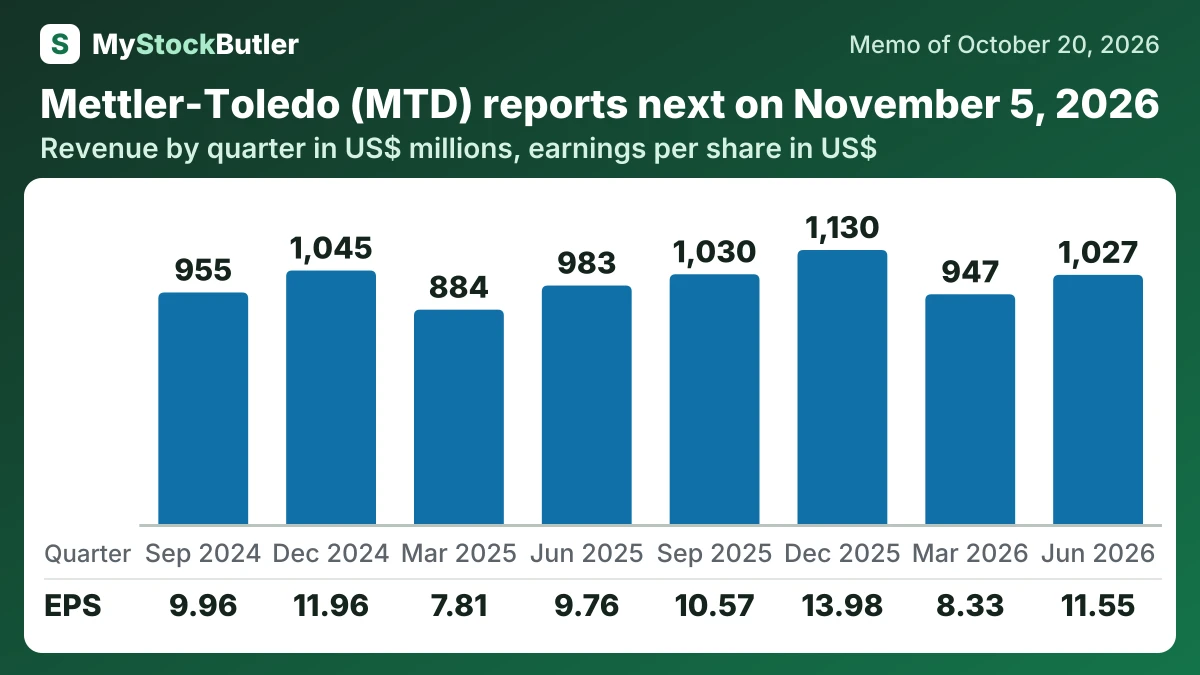
What has Mettler-Toledo's revenue and profit done over the last eight quarters?
Reported revenue grew 4.5% from the same quarter of 2025. Restoring the tariff-related customer repayments lifts the comparison to 7.3%. After removing currency, acquisitions and those unusual repayments, organic local-currency growth was 4% in the June 2026 quarter. Price realization was around 3%, so demand improved, but price and mix still explain much of the result.
The profit adjustment is essential. In June 2026, a government tariff refund reduced cost of sales by $52.4 million, while related customer repayments reduced revenue by $27.8 million. The combined pretax benefit was $24.6 million. Removing both sides reduces operating-income growth from the reported 17.9% to about 8.5%, and brings gross margin close to the prior-year level. Removing only one side would distort the underlying quarter.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 1,027,314 | 947,127 | 1,129,735 | 1,029,699 | 983,221 | 883,744 | 1,045,127 | 954,535 |
| Gross margin | 63.3% | 58.7% | 59.8% | 59.2% | 59.0% | 59.5% | 61.2% | 60.0% |
| Operating income | 309,019 | 219,333 | 338,765 | 283,928 | 262,155 | 215,774 | 331,554 | 275,699 |
| Net income | 232,899 | 169,454 | 285,765 | 217,493 | 202,348 | 163,587 | 252,301 | 211,516 |
| EPS, diluted | 11.55 | 8.33 | 13.98 | 10.57 | 9.76 | 7.81 | 11.96 | 9.96 |
What this means. The reported gross margin includes government tariff refunds, so it looks higher because the company received money back that it did not earn from selling products.