Mettler-Toledo stock forecast 2027–2029
MyStockButler's October 2026 analysis: Mettler-Toledo's weighted scenario is $1,692.39 in October 2027. It hinges on equipment orders, China demand, service renewals, and software adoption.
Where could Mettler-Toledo's shares be by 2029?
The forecast points to modest gains, with meaningful downside if equipment demand weakens. The probability-weighted price rises from today’s $1,625.73 to $1,692.39 in October 2027, $1,766.32 in October 2028 and $1,801.00 in October 2029. Including dividends, which are forecast at zero, those outcomes represent returns of 4%, 9% and 11%.
The 2029 range is much wider: $1,155.00 in the bear case to $2,728.77 in the bull case. The bear carries 25% probability, the base 57% and the bull 18%, because service provides resilience but equipment demand, China and valuation remain uncertain.
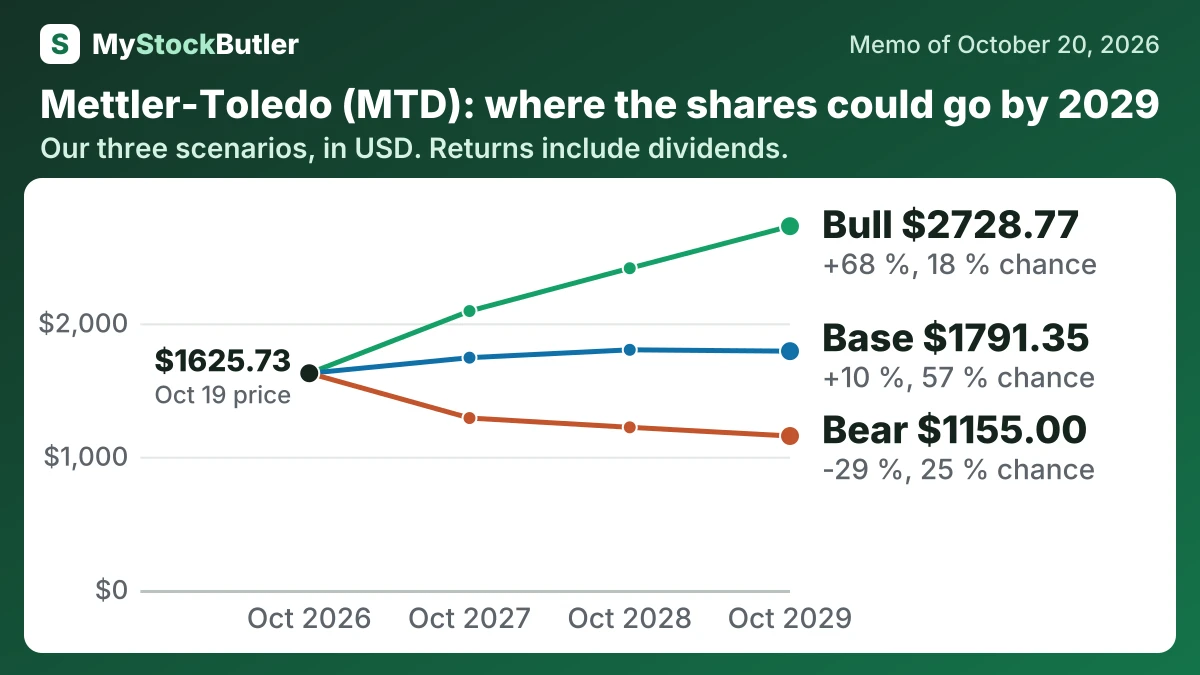
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 25 % | 1289.78 (-21 %) | 1220.19 (-25 %) | 1155.00 (-29 %) |
| Base | 57 % | 1742.70 (+7 %) | 1801.51 (+11 %) | 1791.35 (+10 %) |
| Bull | 18 % | 2092.25 (+29 %) | 2413.40 (+48 %) | 2728.77 (+68 %) |
| Weighted | 100 % | 1692.39 (+4 %) | 1766.32 (+9 %) | 1801.00 (+11 %) |
What this means. The weighted row is the probability-based average value across the bear, base, and bull cases.
What has to go right for Mettler-Toledo, and what could go wrong?
Earnings are the main operating variable. The base case rises from $1,034 million in October 2027 to $1,076 million in October 2028 and $1,118 million in October 2029. It assumes revenue of $4,400 million initially, then $4,600 million and $4,800 million, with net margins easing from 23.5% to 23.3%. The path follows management’s 4%–5% 2026 sales outlook, 4% organic growth in the latest quarter and the steadier service business.
The bear case gives earnings of $918 million, $918 million and $924 million. Weak replacement demand, China and laboratory budgets hold revenue near $4,270 million to $4,400 million, while margins decline from 21.5% to 21.0%. That reflects 2025 product growth of only 1% in local currency and the company’s history of cyclical sales, including a contraction in 2023. The bull case gives $1,069 million, $1,164 million and $1,251 million as equipment recovery broadens, China improves and margins reach 24.2%. It requires stronger cash conversion and sustained service growth.
How much cash does Mettler-Toledo really make?
MT converts most of its earnings into cash, but cash generation has been broadly flat and its preferred measure adds back genuine payments.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 955,772 | 968,346 | 965,874 | 859,067 | 908,825 |
| − Capital spending | 107,124 | 103,898 | 105,323 | 121,241 | 107,580 |
| = Free cash flow | 848,648 | 864,448 | 860,551 | 737,826 | 801,245 |
| − Stock pay | 22,512 | 19,979 | 17,928 | 19,661 | 19,595 |
| = Real free cash flow | 826,136 | 844,469 | 842,623 | 718,165 | 781,650 |
What this means. The company's own free cash flow is higher because it leaves out certain restructuring, acquisition, and transition-tax payments and includes money from selling assets and government-funded equipment spending.
What does an investor pay for Mettler-Toledo today?
| Today (Oct 20, 2026) | |
|---|---|
| Share price | 1625.73 |
| P/E, last 12 months (calculated) | 36.6x |
| P/E, next 12 months (calculated) | 31.4x |
| Free cash flow yield (calculated) | 2.6% |
| Real free cash flow yield (calculated) | 2.5% |
What this means. The very high price-to-book ratio is because the company has very little shareholders’ equity compared with its stock-market value.