EMCOR earnings date and guidance
MyStockButler's October 2026 analysis: EMCOR's next results are expected on October 29, 2026. Watch whether EMCOR's revenue growth arrives with healthy margins and cash.
What has EMCOR guided for 2026?
On July 30, management set revenue guidance at $20.00–$20.50 billion, operating margin at 9.5%–9.8%, and diluted earnings per share at $32.00–$33.25. Operating margin is the profit left from each sales dollar after project costs and corporate overhead. Diluted EPS is profit for shareholders divided by the share count, including potential shares from employee awards.
| The period guided | Low | High | The date it was given | |
|---|---|---|---|---|
| Revenues | Year to Dec 2026 | 20.00 | 20.50 | Jul 30, 2026 |
| Operating Margin | Year to Dec 2026 | 9.5% | 9.8% | Jul 30, 2026 |
| Diluted EPS | Year to Dec 2026 | 32.00 | 33.25 | Jul 30, 2026 |
What this means. The low and high numbers show the company's forecast range, not its actual results.
Has EMCOR kept its promises?
Management has also exceeded the ceiling of its initial revenue and GAAP diluted-EPS guidance in each year from 2021 through 2025. GAAP means the standard accounting rules used in financial statements. That supports a 4/5 assessment of promises kept, although guidance changed during some years.
| What management forecast | Checked | Above | Within | Below |
|---|---|---|---|---|
| Revenues | 5 years | 5 | 0 | 0 |
| Diluted earnings per share | 5 years | 5 | 0 | 0 |
What is EMCOR's trend in revenue and profit?
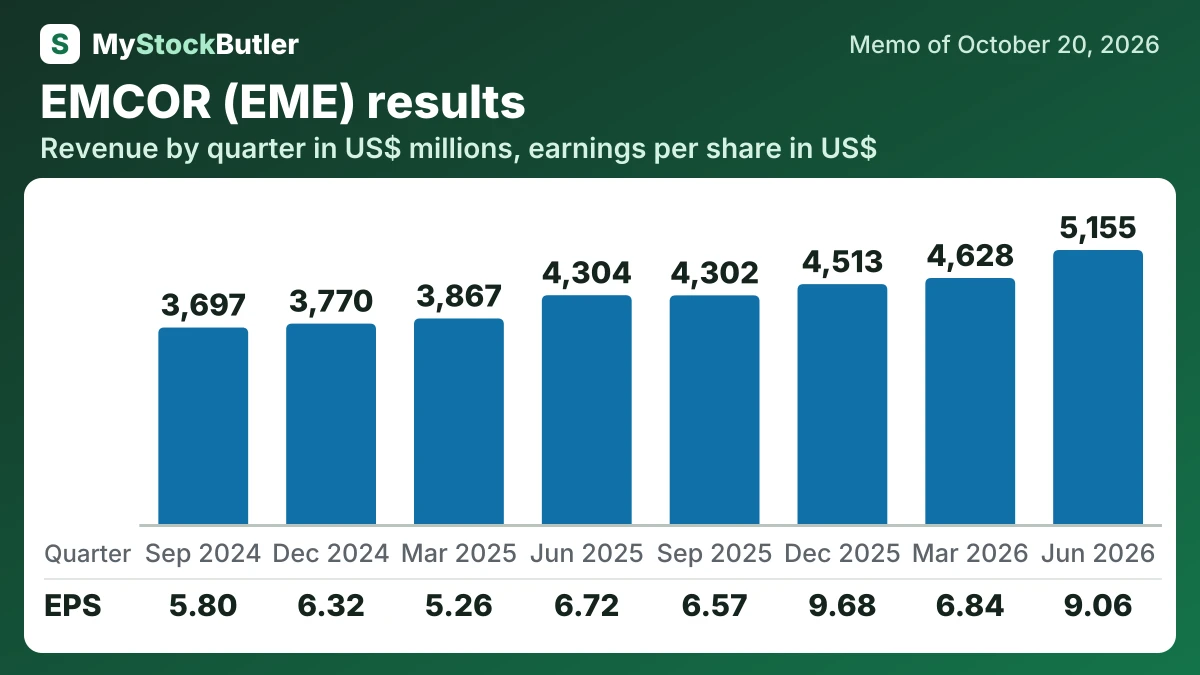
June 2026 showed broad operating strength, but its margin was unusually favorable and its cash recovery remained incomplete.
Profit grew faster than sales. Electrical, building services and industrial activity all contributed, while overhead grew more slowly than revenue. Repurchases also helped EPS grow faster than net income. The quarter was therefore strong across several operating measures, not merely a share-count effect.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 5,154,892 | 4,628,233 | 4,513,121 | 4,301,529 | 4,304,400 | 3,867,372 | 3,770,019 | 3,696,924 |
| Gross margin | 19.8% | 18.7% | 19.7% | 19.4% | 19.4% | 18.7% | 20.1% | 19.9% |
| Operating income | 547,340 | 403,845 | 573,754 | 405,696 | 415,212 | 318,756 | 388,564 | 363,538 |
| Net income | 403,694 | 305,484 | 434,607 | 295,373 | 302,160 | 240,677 | 292,161 | 270,263 |
| EPS, diluted | 9.06 | 6.84 | 9.68 | 6.57 | 6.72 | 5.26 | 6.32 | 5.80 |
What this means. The December 2025 profit per share is unusually high because it includes a one-time gain from selling the United Kingdom business.
What should EMCOR watch in its next results?
EMCOR plans to report third-quarter results before the market opens on October 29, 2026, followed by a 10:30 a.m. Eastern call. Investors should look for acquisition closings, cash consumed, project margins and customer collections. Revenue growth is more valuable when it arrives with healthy margins and cash.