DaVita stock forecast 2027–2029
MyStockButler's October 2026 analysis: DaVita's weighted scenario is $216.44 in October 2027 and $237.92 in October 2029. DaVita's outcome hinges on keeping payer mix and margins intact while turning scale and new care models into cash.
Where could DaVita's shares be by 2029?
The weighted price is $216.44 in October 2027, a 15% return including dividends. It is $237.92 in October 2029, a 27% return including dividends. The bear case has a 30% probability. The base case has 55%. The bull case has 15%.
By October 2029, the bear case reaches $142.71. The bull case reaches $388.38. Today’s reference price is $187.50, so the forecast spans a substantial range around the central path.
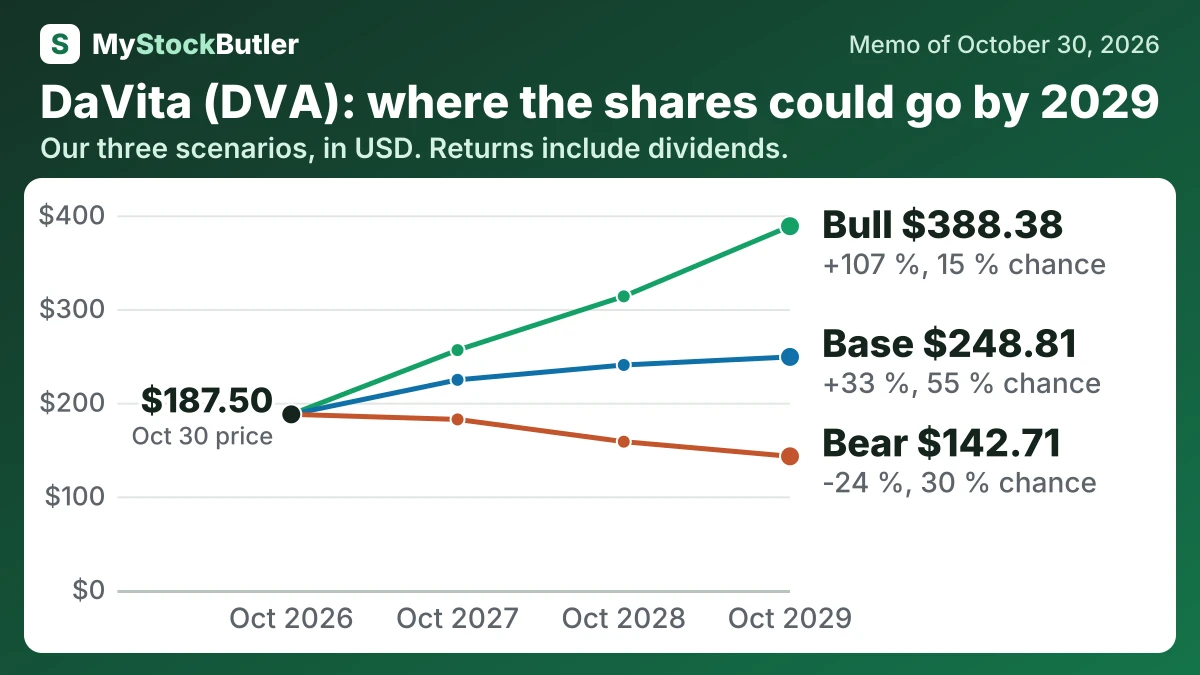
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 30 % | 182.10 (-3 %) | 158.32 (-16 %) | 142.71 (-24 %) |
| Base | 55 % | 224.36 (+20 %) | 240.23 (+28 %) | 248.81 (+33 %) |
| Bull | 15 % | 256.10 (+37 %) | 313.49 (+67 %) | 388.38 (+107 %) |
| Weighted | 100 % | 216.44 (+15 %) | 226.64 (+21 %) | 237.92 (+27 %) |
What this means. The weighted row is the average value after giving each possible outcome more or less importance based on its probability.
What could go right or wrong for DaVita's forecast?
Management’s 2026 adjusted EPS guidance is $14.30 to $15.20, providing the near-term anchor. The base case assumes modest revenue growth, stable core margins, profitable IKC and no material near-term benefit from expanded hemodialysis. The bear case falls from $880 million to $799 million as commercial mix worsens and costs outrun reimbursement. The bull case rises from $1.05 billion to $1.32 billion as treatment growth, cost control and expanded hemodialysis improve margins. Management expects the programme’s financial benefit in the second half of 2028, with a goal of at least 2% volume growth by 2029.
How much cash does DaVita really make?
About $412 million of capital spending maintained existing capacity, including equipment, renovations and technology. The boundary between maintenance and growth requires judgment. Stock compensation adds another economic cost because shares issued to employees can dilute owners. Subtracting $139.95 million of stock pay produces analytical “real free cash flow” of $1.17 billion.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 1,886,500 | 2,022,038 | 2,059,031 | 1,564,570 | 1,930,876 |
| Of which, freed from working capital | 43,882 | 208,543 | 66,251 | ||
| Of which, tied up in working capital | 230,336 | 107,520 | |||
| − Capital spending | 575,864 | 555,443 | 567,985 | 603,429 | 641,465 |
| = Free cash flow | 1,310,636 | 1,466,595 | 1,491,046 | 961,141 | 1,289,411 |
| − Stock pay | 139,953 | 102,788 | 112,375 | 95,427 | 102,209 |
| = Real free cash flow | 1,170,683 | 1,363,807 | 1,378,671 | 865,714 | 1,187,202 |
| Free cash flow — the company's own count | 1,024,000 | 1,162,000 | 1,236,000 | 817,000 | 1,133,000 |
| What its own count also takes out | 286,636 | 304,595 | 255,046 | 144,141 | 156,411 |
| Free cash flow, % of revenue | 9.6% | 11.4% | 12.3% | 8.3% | 11.1% |
| Real free cash flow, % of revenue | 8.6% | 10.6% | 11.4% | 7.5% | 10.2% |
What this means. The company's own free cash flow is lower because it uses different rules and removes additional cash items, such as payments to minority owners, that our count keeps.
What does an investor pay for DaVita today?
Free cash flow is closer to the shareholder claim, but its rolling period matters. DaVita reported $1.308 billion through June 30, 2026, and $980 million through September 30, 2026, so the earlier cash-flow yield needs updating. Berkshire Hathaway’s roughly 45% holding adds another complication: if DaVita retires public shares, Berkshire’s percentage rises even if it buys nothing.
| Today (Oct 30, 2026) | |
|---|---|
| Share price | 187.50 |
| Market value (calculated) | 11,887,500 |
| Enterprise value (calculated) | 22,090,313 |
| P/E, last 12 months (calculated) | 14.2x |
| P/E, next 12 months (calculated) | 12.7x |
| EV / revenue, last 12 months (calculated) | 1.6x |
| Price to book (calculated) | not meaningful |
| Free cash flow yield (calculated) | 11.0% |
| Real free cash flow yield (calculated) | 9.8% |
| Dividend yield (calculated) | 0.0% |
What this means. DaVita's price-to-book measure is not useful because the company owes more than its recorded assets, making shareholders' equity negative.