DuPont earnings: guidance and results
MyStockButler's October 2026 analysis: DuPont's next results are expected on November 3, 2026. Watch whether large water projects remain on schedule.
What has DuPont guided for the year?
On August 4, 2026, DuPont reported second-quarter 2026 sales growth of 4.0%, including 4.0% organic growth, and raised its full-year outlook. The guidance covers sales, operating EBITDA and adjusted EPS; the table gives the ranges. Operating EBITDA is operating profit before interest, taxes and depreciation and amortization, with selected exclusions. Adjusted EPS also removes specified items, so neither measure is cash in the bank.
| The period guided | Low | High | The date it was given | |
|---|---|---|---|---|
| Net sales — FY2026 | Year to Dec 2026 | 7,160 | 7,190 | Aug 4, 2026 |
| Operating EBITDA — FY2026 | Year to Dec 2026 | 1,750 | 1,770 | Aug 4, 2026 |
| Operating EBITDA — 2H2026 | 6 months to Dec 2026 | 890 | 910 | Aug 4, 2026 |
| Adjusted EPS — FY2026 | Year to Dec 2026 | 7.17 | 7.32 | Aug 4, 2026 |
| Adjusted EPS — 2H2026 | 6 months to Dec 2026 | 3.65 | 3.80 | Aug 4, 2026 |
| Organic sales growth — FY2026 | Year to Dec 2026 | Slightly above 4% | Aug 4, 2026 |
What this means. The 5 percent adjusted organic sales growth is higher than the reported 3 percent because last year's sales timing shifted, making this year's comparison look weaker than the underlying business.
Has DuPont kept its past promises?
Management has delivered some restructuring promises, but its operating promises remain unfinished. DuPont abandoned the planned water separation in January 2025 and accelerated the electronics separation, which departed as Qnity on November 1, 2025. At the September 2025 investor day, management promised annual organic sales growth of 3–4% and margin expansion of 150–200 basis points by 2028. Organic growth strips out currency and portfolio effects; pro forma figures rebuild earlier periods as if the post-separation company had existed then. Second-quarter 2026 organic growth was 4%, and management raised full-year guidance.
How have DuPont's revenue and profit trended?
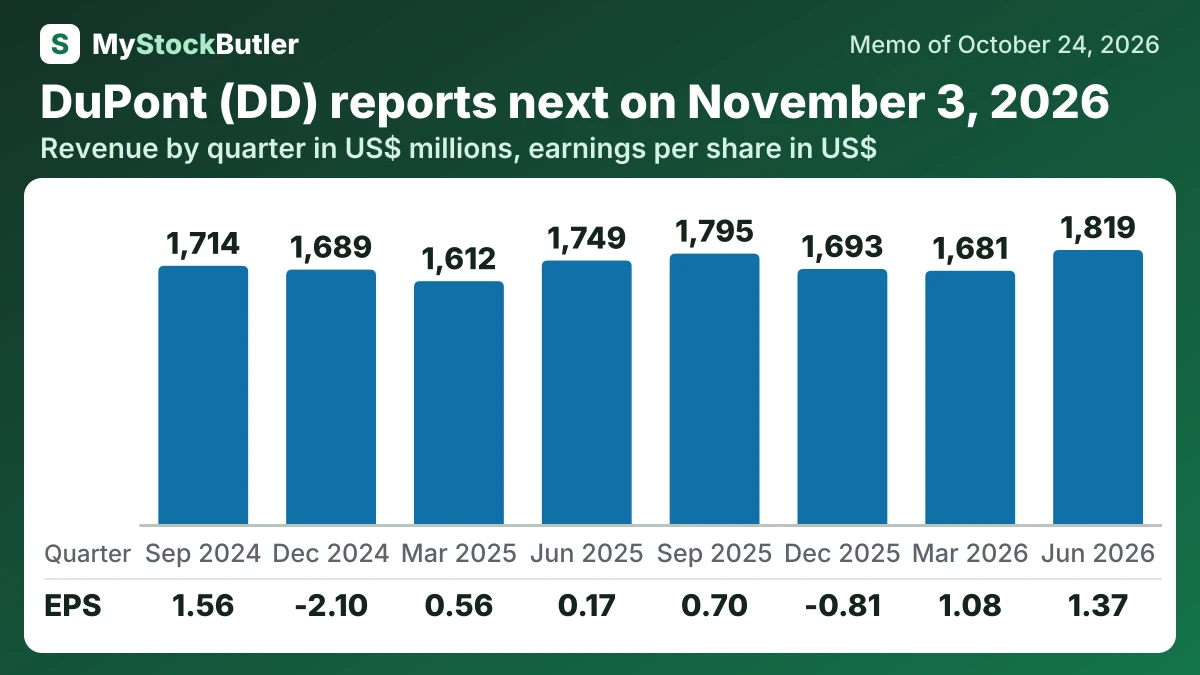
The June 2026 quarter showed broader growth, but earnings improved much faster than sales. Both segments grew organically: Healthcare & Water Technologies by 4% and Diversified Industrials by 3%. That is healthier than the 2025 pattern, when healthcare and water carried the recovery.
| Jun 2026 | Mar 2026 | Dec 2025 | Sep 2025 | Jun 2025 | Mar 2025 | Dec 2024 | Sep 2024 | |
|---|---|---|---|---|---|---|---|---|
| Revenue | 1,819 | 1,681 | 1,693 | 1,795 | 1,749 | 1,612 | 1,689 | 1,714 |
| Gross margin | 35.1% | 35.8% | 35.3% | 34.3% | 34.6% | 33.7% | 32.7% | 33.8% |
| Operating income | 256 | 186 | 97 | 152 | 162 | 95 | 131 | |
| Net income | 187 | 147 | -111 | 98 | 24 | 78 | -294 | 221 |
| EPS, diluted | 1.37 | 1.08 | -0.81 | 0.70 | 0.17 | 0.56 | -2.10 | 1.56 |
What this means. Free cash flow is not profit: it is the cash left after the business pays for equipment and buildings, so it can be negative even when net income is positive.
What should DuPont watch in the next release?
DuPont will release third-quarter results on November 3, 2026. The key question is whether the large water projects remain on schedule. Because most relevant revenue was expected in the fourth quarter, satisfactory third-quarter earnings alone would not prove that the year-end project forecast is secure.
The comparison also contains a timing effect. Third-quarter organic-growth guidance is 3.0% as reported, or 5.0% after adjusting for sales shifted into the prior-year quarter before the electronics separation. The corresponding fourth-quarter expectation, excluding that effect, is 7.0%. Analysts must separate this calendar change from genuine customer demand.