Centrica dividend
MyStockButler's October 2026 analysis: Centrica paid 5.50p per share in 2025, but its real free cash flow was negative £191m, so that year's dividend was not supported by cash on this definition. The company made £695m from operations, then spent £554m on capital spending, £95m on leases and £181m on interest.
How much does Centrica pay shareholders per share?
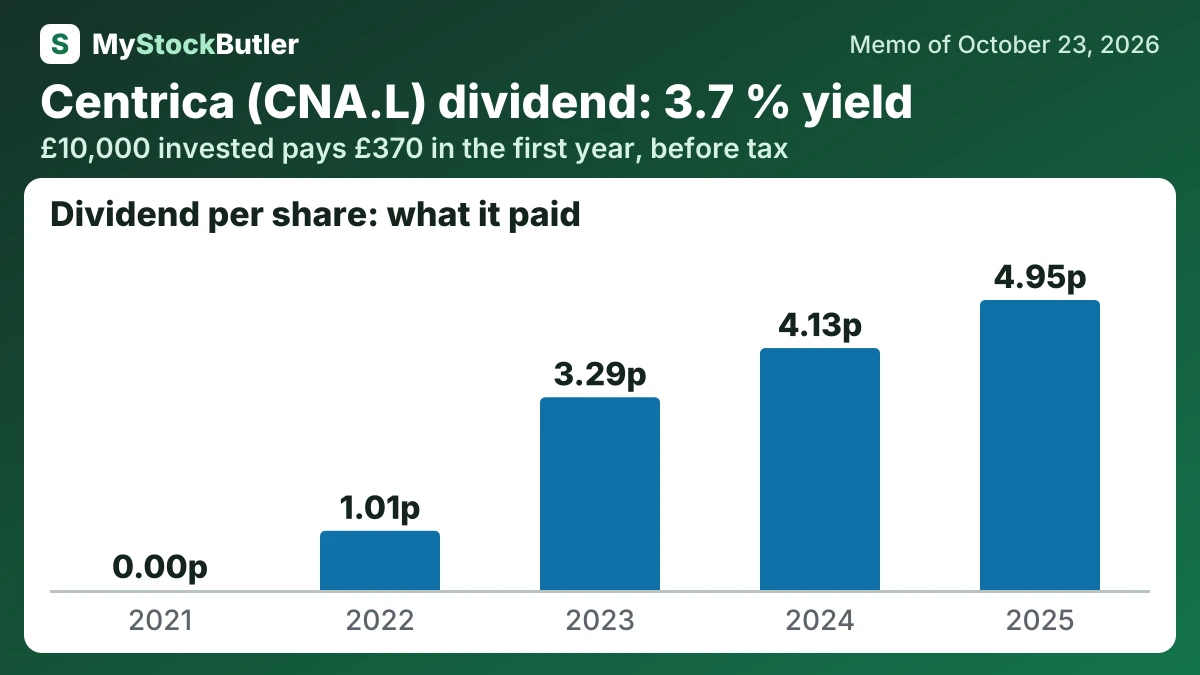
The five-year pattern matters. Real free cash flow reached £2,007m in 2023 before falling to £306m in 2024. Dividends reached 5.50p per share in 2025, so that distribution was not supported by that year’s free cash flow on this definition.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| EPS, diluted | -1.50 | 25.10 | 69.40 | -13.30 | 9.90 |
| − Dividends paid, per share | 4.95 | 4.13 | 3.29 | 1.01 | 0.00 |
| − Share buybacks, per share | 17.28 | 9.40 | 10.83 | 0.73 | 0.00 |
| = FCF not paid out, per share | 21.59 | 4.99 | 13.48 | ||
| = Paid out more than FCF, per share | 25.06 | 6.88 |
What this means. The company's own free cash flow per share differs from our count because it leaves out some cash movements, while our count also subtracts shares given to employees as pay.
How much would Centrica's dividend pay you?
£10,000 invested in Centrica at its 3.7% dividend yield (our report of October 23, 2026) pays £370.00 in the first year, before tax. If its dividend stays flat and the dividends are reinvested, year 10 pays £513.11, with £4,380.95 received in all.
Before tax. Past dividend growth is not a promise. Information only, not investment advice.
Does Centrica’s cash cover its dividend?
Cash from operations was £695m in 2025. After £554m of capital spending, £95m of lease payments and £181m of interest, free cash flow was negative £135m. Deducting £56m of stock-based pay gives real free cash flow of negative £191m. That last deduction treats equity compensation as an economic cost to shareholders, even though it is not another cash payment that year.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Free cash flow | -135 | 353 | 2,038 | 668 | 796 |
| − Dividends paid | 237 | 219 | 186 | 59 | 0 |
| − Share buybacks | 827 | 499 | 613 | 43 | 0 |
| = Free cash flow not paid out | 1,222 | 293 | 796 | ||
| = Paid out more than the free cash flow | 1,199 | 365 | |||
| Paid out, % of free cash flow | not meaningful | 203.4% | 39.2% | 15.3% | 0.0% |
What this means. The company's own net cash is lower because it also counts securities, hedging contracts, leases, and unpaid interest, while our figure only subtracts borrowings from cash and short-term investments.
What could change Centrica’s dividend?
That does not make the dividend automatically unsafe, but it means the dividend currently relies partly on balance-sheet capacity. Centrica’s free-cash-flow measure also excludes pension-deficit payments and movements in trading collateral, although those payments still affect the bank account. The dividend becomes durable only when ordinary cash generation covers maintenance, growth investment and shareholder distributions.
Buybacks increased each remaining shareholder’s percentage of the company, but they also used cash. Centrica spent £2bn repurchasing shares. The programme removed 25% of the shares at an average price of 136p, so each remaining share represented more of the business, provided the shares bought were worth more than the cash surrendered. Pausing buybacks shows that management now prefers funding investment.
What is Centrica’s dividend yield against its share price?
| Today (Oct 23, 2026) | |
|---|---|
| Share price | 150.55 |
| Market value (calculated) | 6,954.65 |
| Free cash flow yield (calculated) | -1.9% |
| Real free cash flow yield (calculated) | -2.7% |
| Dividend yield (calculated) | 3.7% |