GoDaddy stock forecast 2027–2029
MyStockButler's October 2026 analysis: GoDaddy's weighted scenario is $110.55 in October 2027. GoDaddy's outcome hinges on Airo renewals, margins and working-capital support.
Where could GoDaddy's shares be?
At October 2027, the weighted price is $110.55, a 5% loss including dividends. At October 2028, it is $135.84, a 17% gain. At October 2029, it reaches $167.01, a 44% gain.
The base case has the greatest weight at 55%. The bear case carries 25%, while the bull case carries 20%.
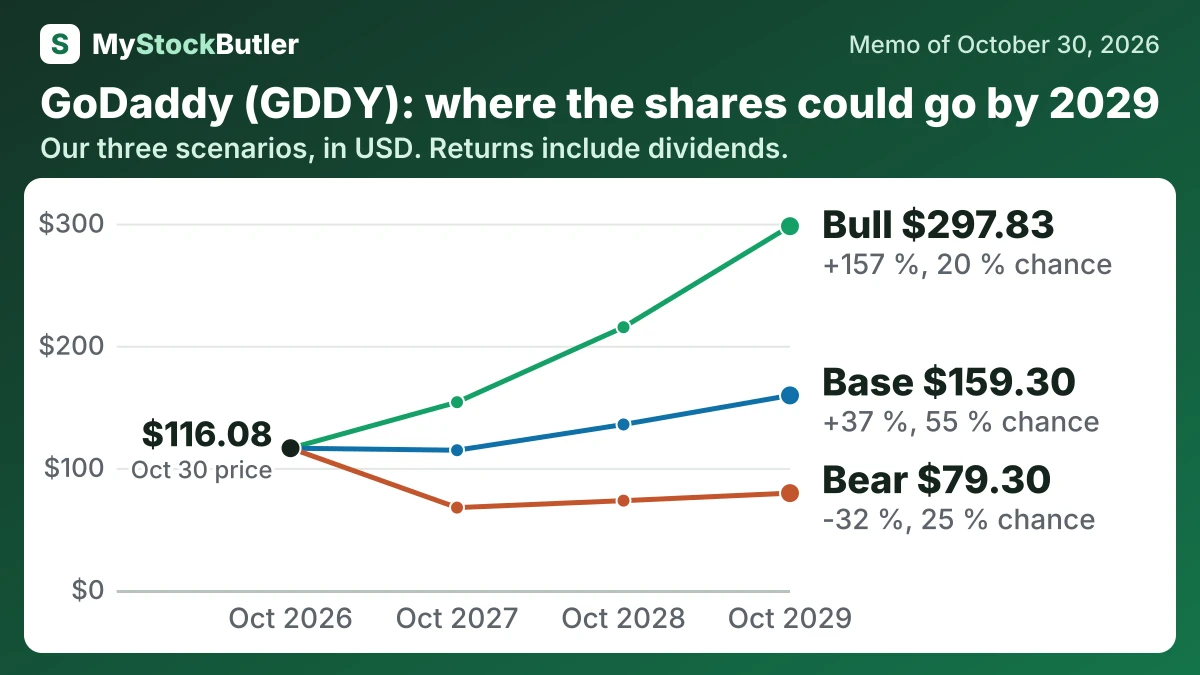
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 25 % | 67.46 (-42 %) | 73.15 (-37 %) | 79.30 (-32 %) |
| Base | 55 % | 114.42 (-1 %) | 135.51 (+17 %) | 159.30 (+37 %) |
| Bull | 20 % | 153.75 (+32 %) | 215.13 (+85 %) | 297.83 (+157 %) |
| Weighted | 100 % | 110.55 (-5 %) | 135.84 (+17 %) | 167.01 (+44 %) |
What has to go right for GoDaddy, and what could go wrong?
The base case assumes steady cash growth, continued buybacks, no dividend, and a stable valuation.
The bear case starts at $1,250 million, then grows 3% annually because Airo renewals, margins and working-capital support disappoint. The bull case starts at $1,620 million and grows 12% annually because paid attachment improves and AI delivery becomes more efficient. Those cases test the main uncertainty: bookings must become durable, profitable renewals.
| October 2027 | October 2028 | October 2029 | |
|---|---|---|---|
| Free cash flow after stock pay | 1,526 (1,250 / 1,620) | 1,618 (1,288 / 1,814) | 1,715 (1,327 / 2,032) |
| Shares (millions) | 114 (119 / 110) | 108 (118 / 101) | 103 (118 / 91.70) |
| Dividends per share | 0.00 (0.00 / 0.00) | 0.00 (0.00 / 0.00) | 0.00 (0.00 / 0.00) |
| Enterprise value to free cash flow after stock pay | 10.00 (8.00 / 12.00) | 10.00 (7.50 / 13.00) | 10.00 (7.00 / 14.00) |
| Net debt | 2,216 (1,966 / 2,466) | 1,572 (1,036 / 1,940) | 806 (-45.00 / 1,137) |
How much cash does GoDaddy really make?
Stock compensation complicates the picture. Cash-flow accounting adds back the expense because no cash leaves immediately, but employees receive ownership and existing shareholders may be diluted. Deducting $317.8 million of stock pay from conventional free cash flow produces the memo’s “real free cash flow.” That is an analytical measure, not GoDaddy’s own definition.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 1,599.4 | 1,287.7 | 1,047.6 | 979.7 | 829.3 |
| Of which, freed from working capital | 103.0 | 61.2 | 130.5 | 81.4 | 143.0 |
| − Capital spending | 23.9 | 26.6 | 42.0 | 59.7 | 51.1 |
| = Free cash flow | 1,575.5 | 1,261.1 | 1,005.6 | 920.0 | 778.2 |
| − Stock pay | 317.8 | 299.9 | 296.3 | 264.4 | 207.9 |
| = Real free cash flow | 1,257.7 | 961.2 | 709.3 | 655.6 | 570.3 |
| Free cash flow — the company's own count | 1,613.6 | 1,355.5 | 1,084.4 | 968.6 | 855.8 |
| What its own count adds back | 38.1 | 94.4 | 78.8 | 48.6 | 77.6 |
| Free cash flow, % of revenue | 31.8% | 27.6% | 23.6% | 22.5% | 20.4% |
| Real free cash flow, % of revenue | 25.4% | 21.0% | 16.7% | 16.0% | 14.9% |
What this means. The company's own free cash flow is higher because it adds back cash it actually paid for restructuring, other charges, and earlier acquisition costs.